Macro Extremes (week ending July 5, 2024)

A weekly Macro, Cross Asset review of prices trading at extremes which may generate future investment ideas and opportunities.

The following assets (on a weekly timeframe) either registered an Overbought or Oversold reading and/or have traded more than 2.5 standard deviations above or below its rolling mean.

* denotes multiple week inclusion

Extremes above the Mean (at least 2.5 standard deviations)

U.S. 10 year minus U.S. 5 year government bond yield spread

KOSPI

Singapore’s Strait Times Index

Overbought (RSI > 70)

Biodiesel *

Robusta Coffee

AUD/JPY

EUR/JPY

GBP/JPY *

USD/JPY

Netherlands AEX *

Hungary’s BUX *

Pakistan’s KSE *

Nasdaq Composite * 

Nasdaq 100 *

Philadelphia Semiconductor Index (SOX)

S&P 500 *

Turkiye’s BIST 100

and Taiwan’s TAEIX *

The Overbought Quinella (Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)

NIFTY *

SENSEX *

Extremes below the Mean (at least 2.5 standard deviations)

Shanghai Composite Index

China’s CSI 300 Index

Oversold (RSI < 30)

Cotton

North European Hot Rolled Coil Steel *

U.S. Midwest Hot Rolled Coil Steel *

Lumber *

Lithium Hydroxide *

Corn *

And the Chinese RMB *

The Oversold Quinella (Both Oversold and Traded at < 2.5 standard deviations below the weekly mean)

None

Notes & Ideas:

Government bond yields changed course and fell,

Except for the German, Swedish, Norwegian, Swiss and Polish 10’s, along with the Euro curve.

In fact, the Swiss 10’s yield broke their 4 consecutive weeks of decline. 

Furthermore, all of the bond yields and spreads which appeared last week are no longer so.

Against the yield trend, the Copper/Gold ratio bounced,

And the U.S. 2’s and 5’s yield had bearish outside reversal weeks.

Equities saw strength, again…..again….mostly !

For example, the Nasdaq Composite has risen for 10 out of the past 11 weeks, so much so to render it trading at 36% above its 200 week moving average.

China’s CSI 300 and Shanghai Composite have fallen for 7 consecutive weeks, while the KOSPI has risen for 5 straight weeks

Chile’s IGPA broke its 5 weeks of declines and Thailand’s SET broke its 6 week losing streak

Indonesia’s main index has climbed 8.2% over the past 3 weeks.

And the FTSE 250 and Vietnam’s VN Index both had bullish outside reversal weeks.

Commodities were mostly firmer, which is a change against the past weeks of weaker bias.

Coking Coal, Copper, Oil and Distillates, Tin, Precious Metals Orange Juice and Coffee featured amongst those who had a terrific week.

Gases, Urea, Rice and Lithium were the biggest losers for the week.

WTI Crude, Brent Crude, Heating Oil and Gasoline are in a 4 week winning streak.

Lean Hogs have slumped for 9 of the past 11 weeks, falling 14% over that time.

Lumber and Natural Gas (NG) prices have fallen for 4 consecutive weeks.  NG has posted a 26% loss during this streak.

The Copper/Gold Ratio bounced out of its 6 week losing streak.

Palladium has risen 15% over the past 3 weeks.

Soybeans and Wheat both broke their 5 straight weeks of declines.

Lumber has fallen for 11 weeks of the past 15 weeks.

And Lithium Hydroxide has now spent 51 consecutive weeks in weekly oversold territory.

Currencies continue to provide action, again and again.

Many currencies no longer appearing in extreme categories.

The AUD has risen for 4 consecutive weeks against the JPY, EUR, CAD, SGD, THB and USD.

The CAD/AUD has fallen for 4 weeks, while the Loonie against the USD has climbed for 4 straight weeks.

The U.S. Dollar (DXY Index) fell 1%, breaking its 4 week winning streak.

The Euro was mixed

The British Pound was stronger in a week when the United Kingdom held a general election.

And the Yen was weak, again.

The larger advancers over the past week comprised of;

Australian Coking Coal 7.6%, China Coking Coal 7.5%, WTI Crude Oil 2%, Copper 5.9%, Heating Oil 2.7%, Tin 3.3%, Newcastle Coal 2.8%, Orange Juice 4.9%, Palladium 6.3%, Platinum 3.2%, Robusta Coffee 4.3%, SPGSCI 1.5%, Brent Crude Oil 2.3%, Gasoil 2.8%, Silver in AUD 5.9%, Silver in USD 7.1%, Gold in CAD and CHF 2.5%, Gold in USD 2.8%, Gold in ZAR 3.1%, Soybean 2.3%, Wheat 3%, All World ex USA 2.1%, ATX 2.8%, CAC 2.6%, Egypt 2.2%, MIB 2.5%, BOVESPA 1.9%, IDX 2.1%, Nasdaq Composite 3.5%, KOSPI 2.3%, FTSE 250 2.5%, Nasdaq 100 3.6%, Nikkei 225 3.4%, SOX 3.4%, S&P 500 2%, STI 2.3%, TAIEX 2.3%, Vietnam 3%, ASX Materials 3.3%, BIST 1.9% and Israel’s TA25 rose 2.1%.  

The group of largest decliners from the week included;

Baltic Dry Index (4.1%), Cotton (2.4%), Lithium (3.6%), Natural Gas (10.8%), Dutch TTF Gas (4.1%),Urea U.S. Gulf (4.2%), Rice (5.4%), and the KRE Regional Banks Index fell 2.4%.

July 7, 2024

by Rob Zdravevski
rob@karriasset.com.au

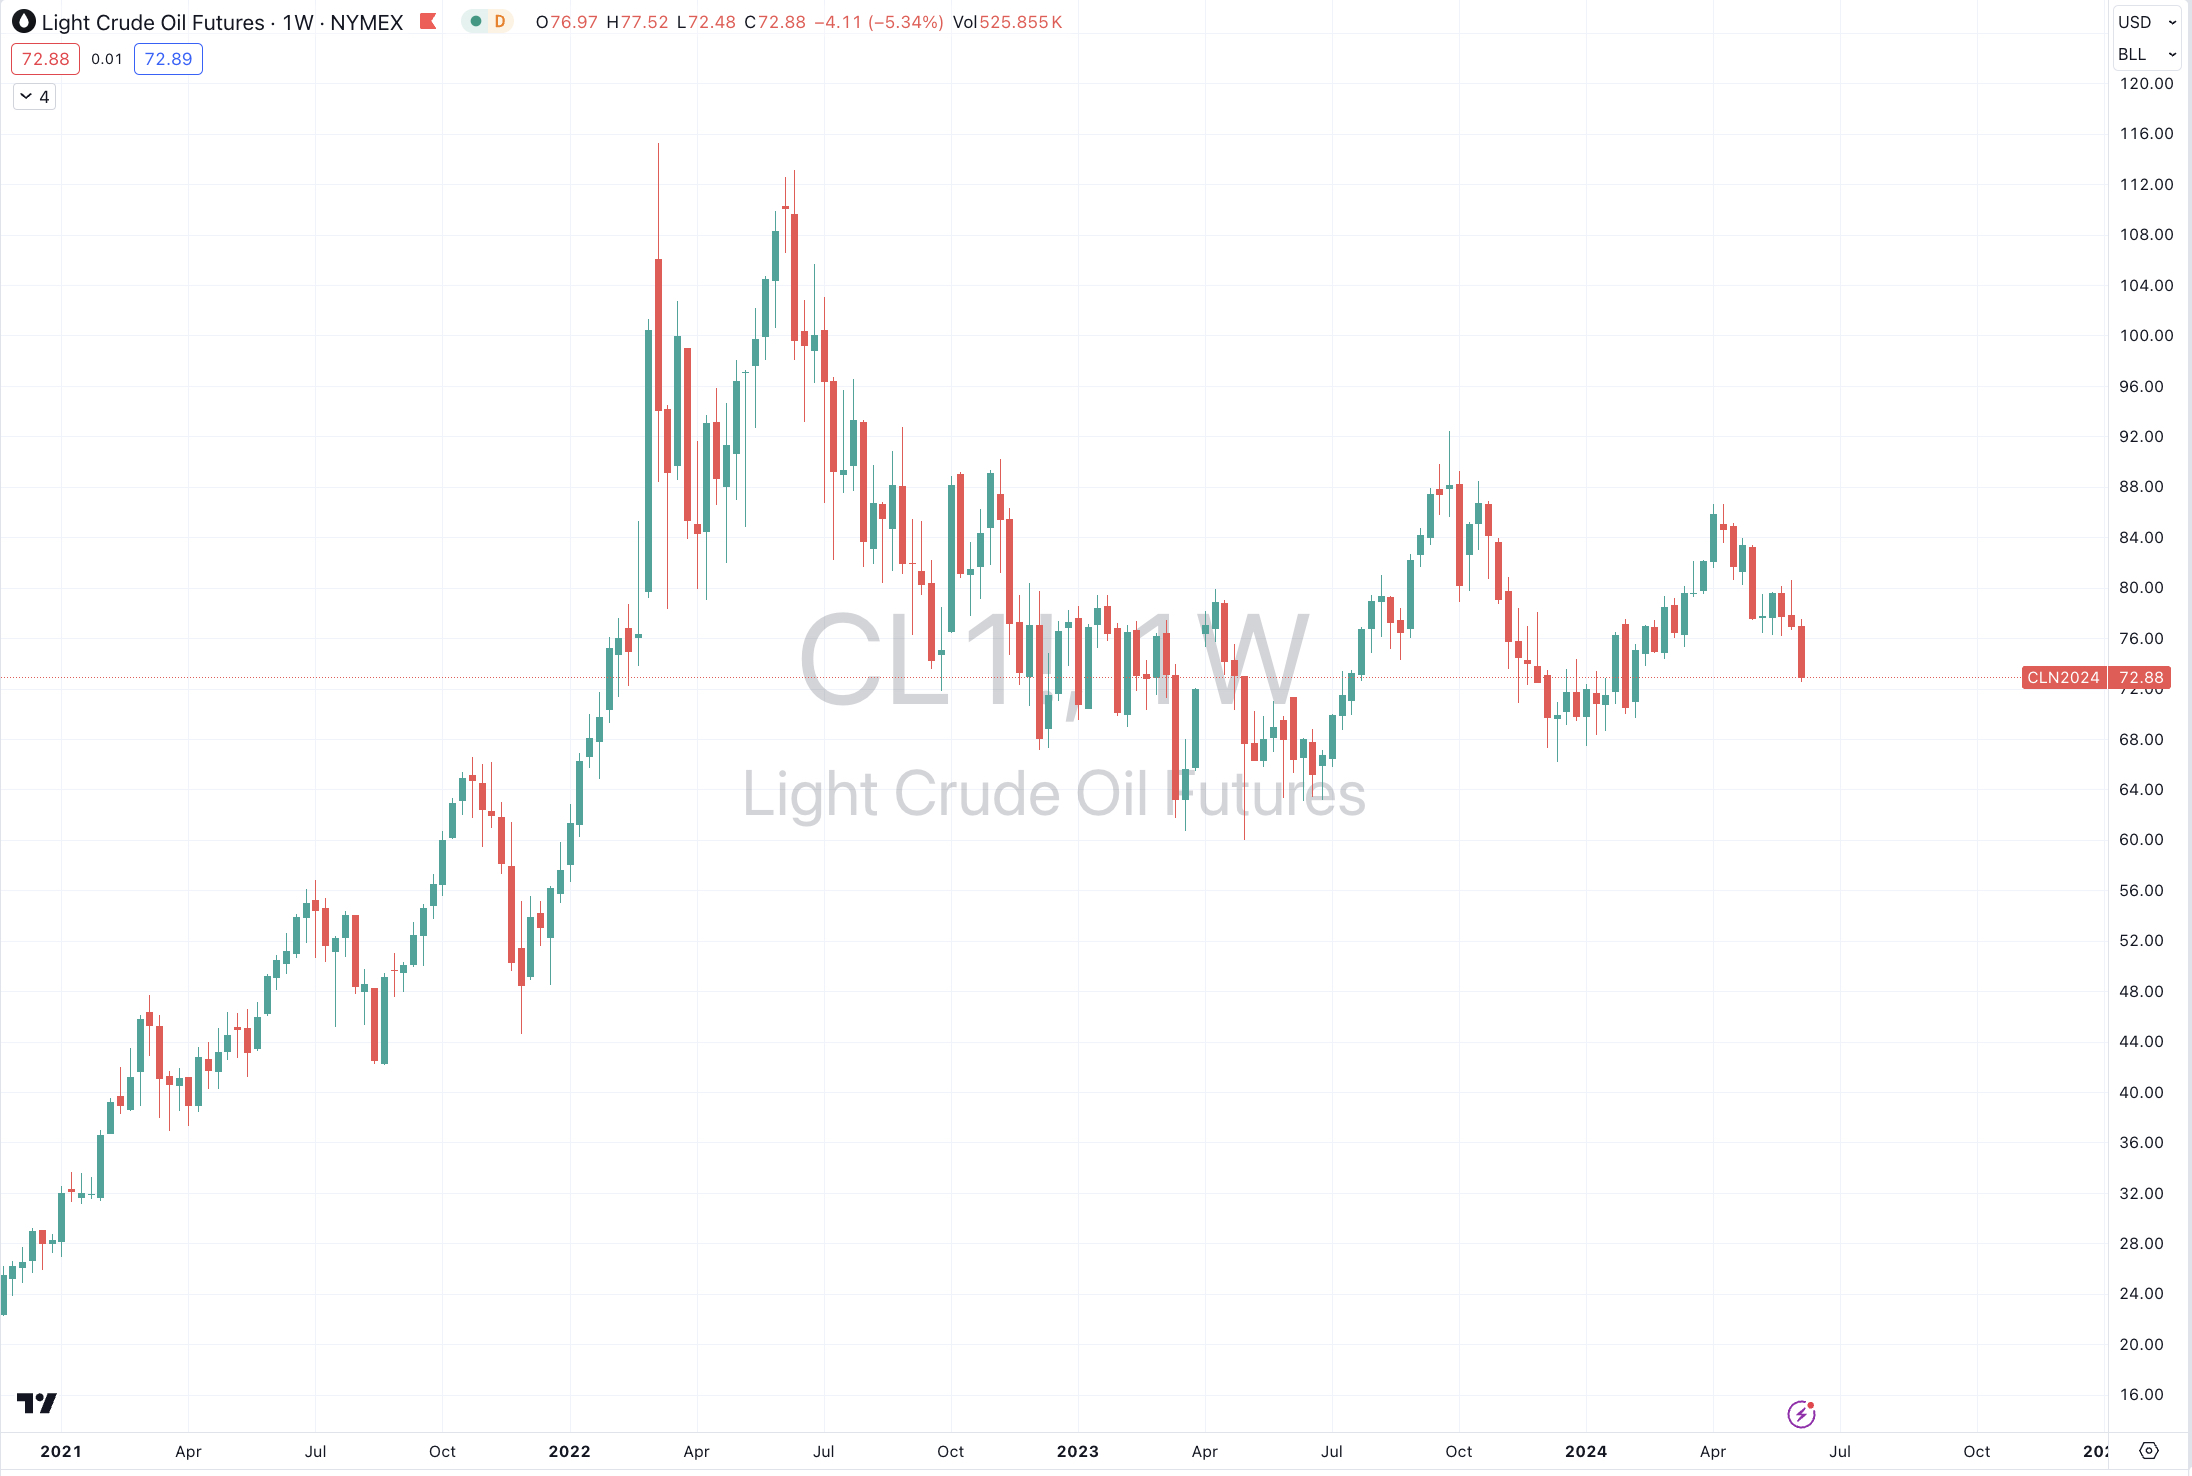
What if Oil prices halved?

WTI Crude Oil ain’t $80 anymore. It’s now $73.

In my note from mid-May, I opine that oil prices see $64 and perhaps $46.

June 4, 2024

by Rob Zdravevski

Karri Asset Advisors

rob@karriasset.com.au

Screenshot

Gold, bad times and inflation

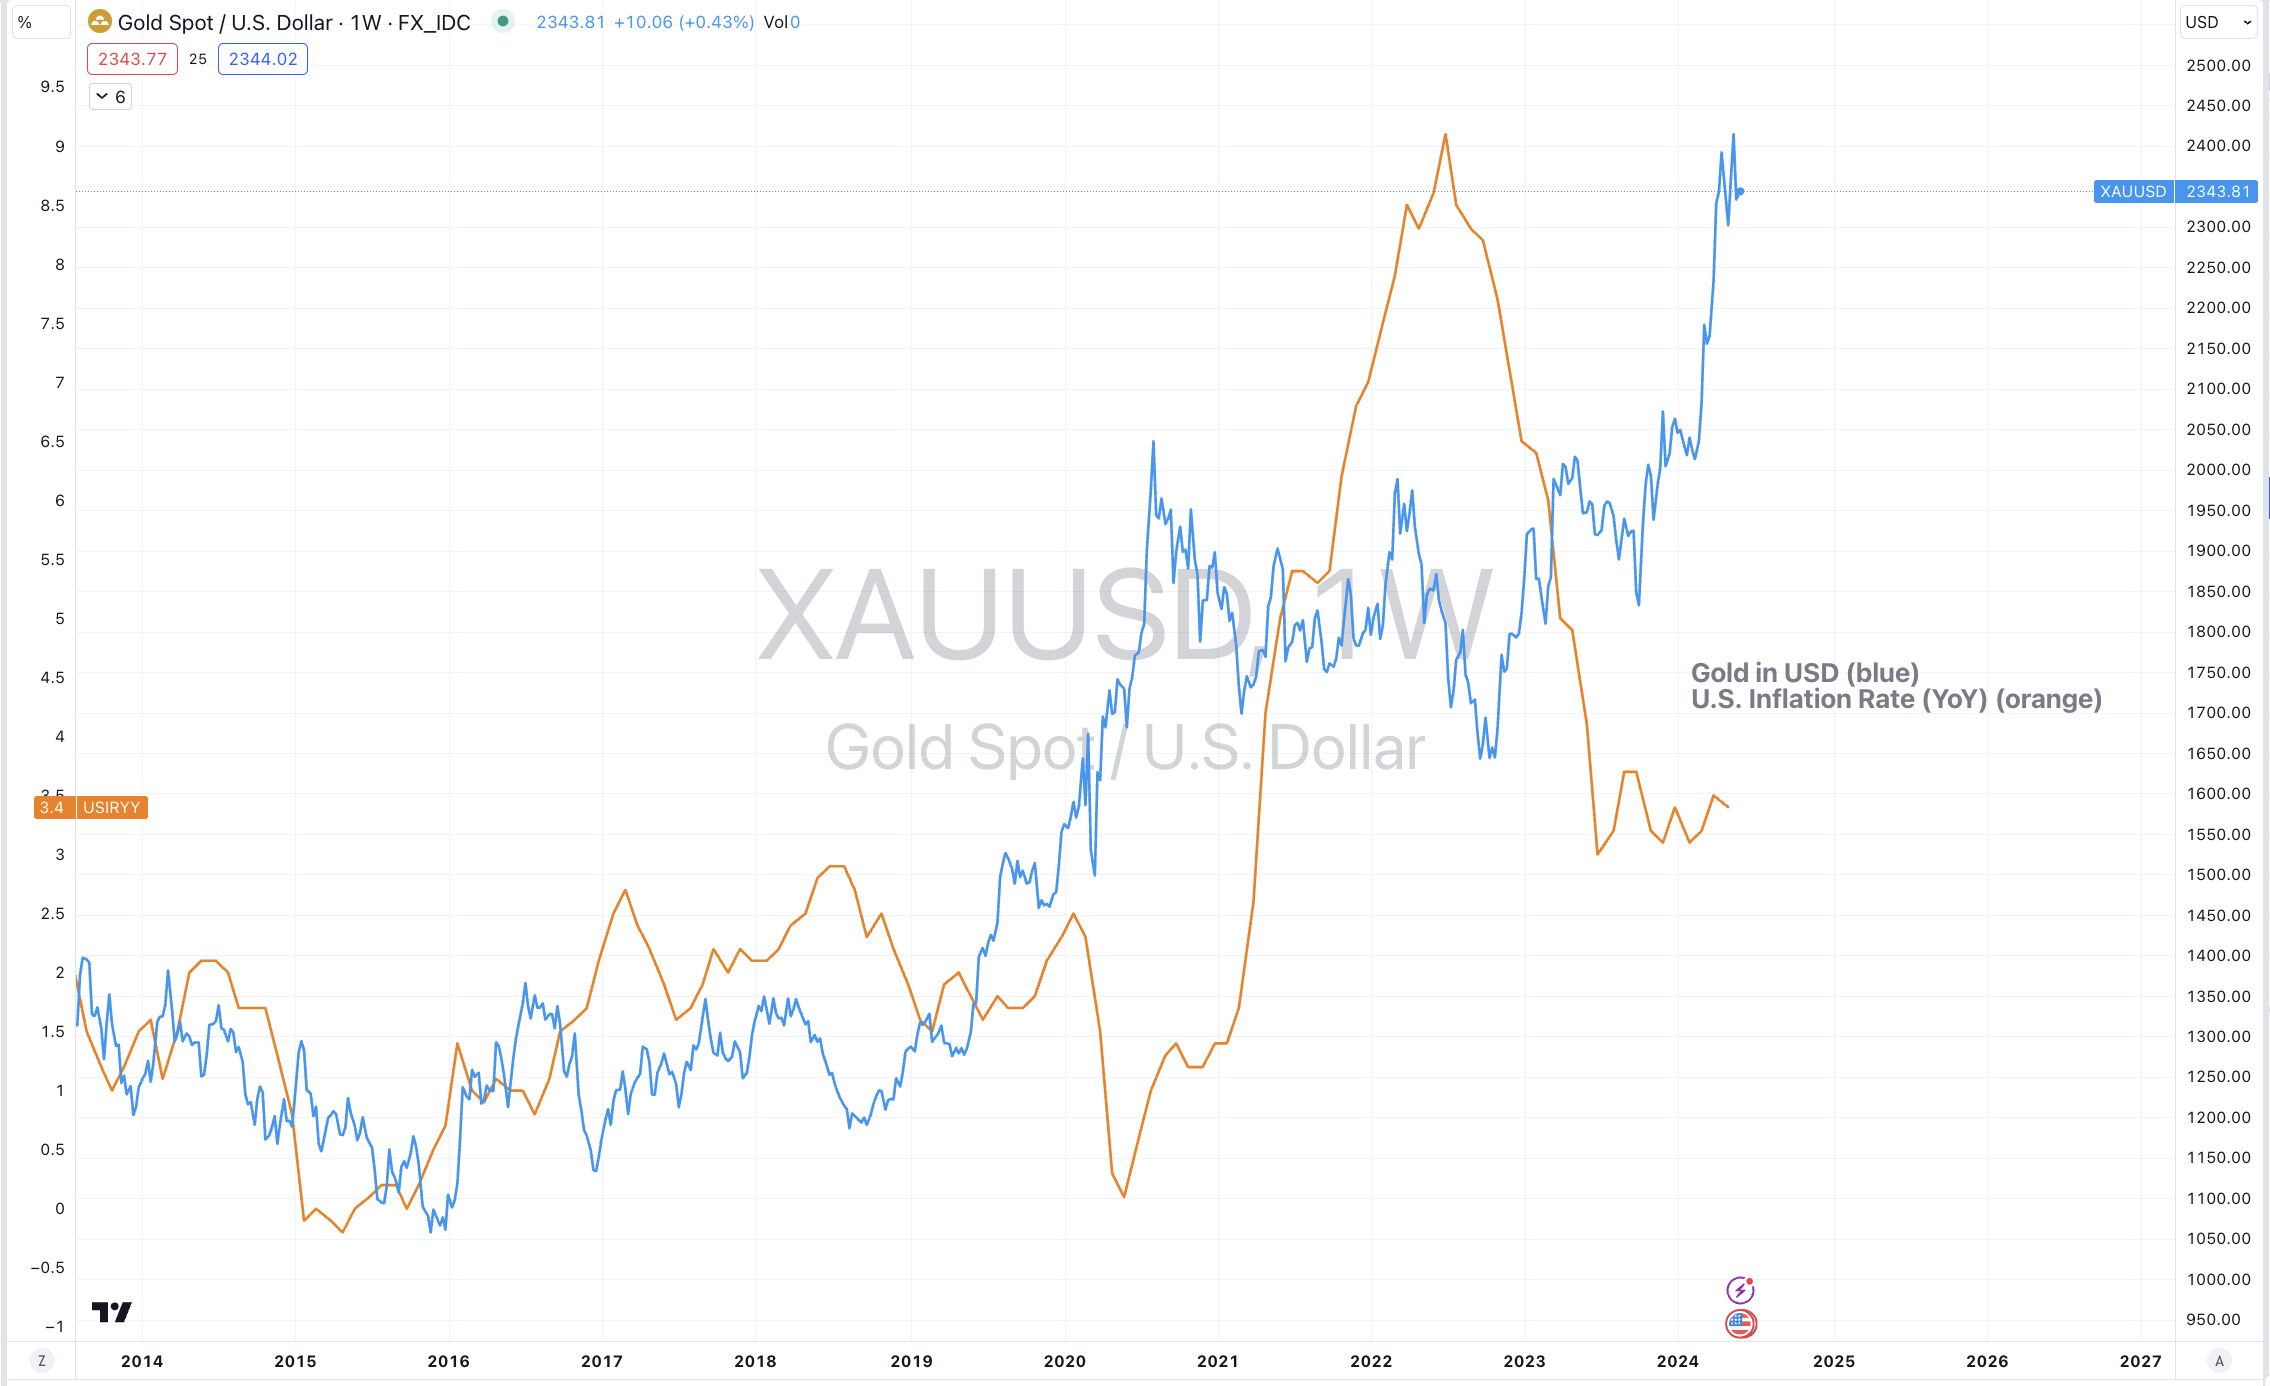
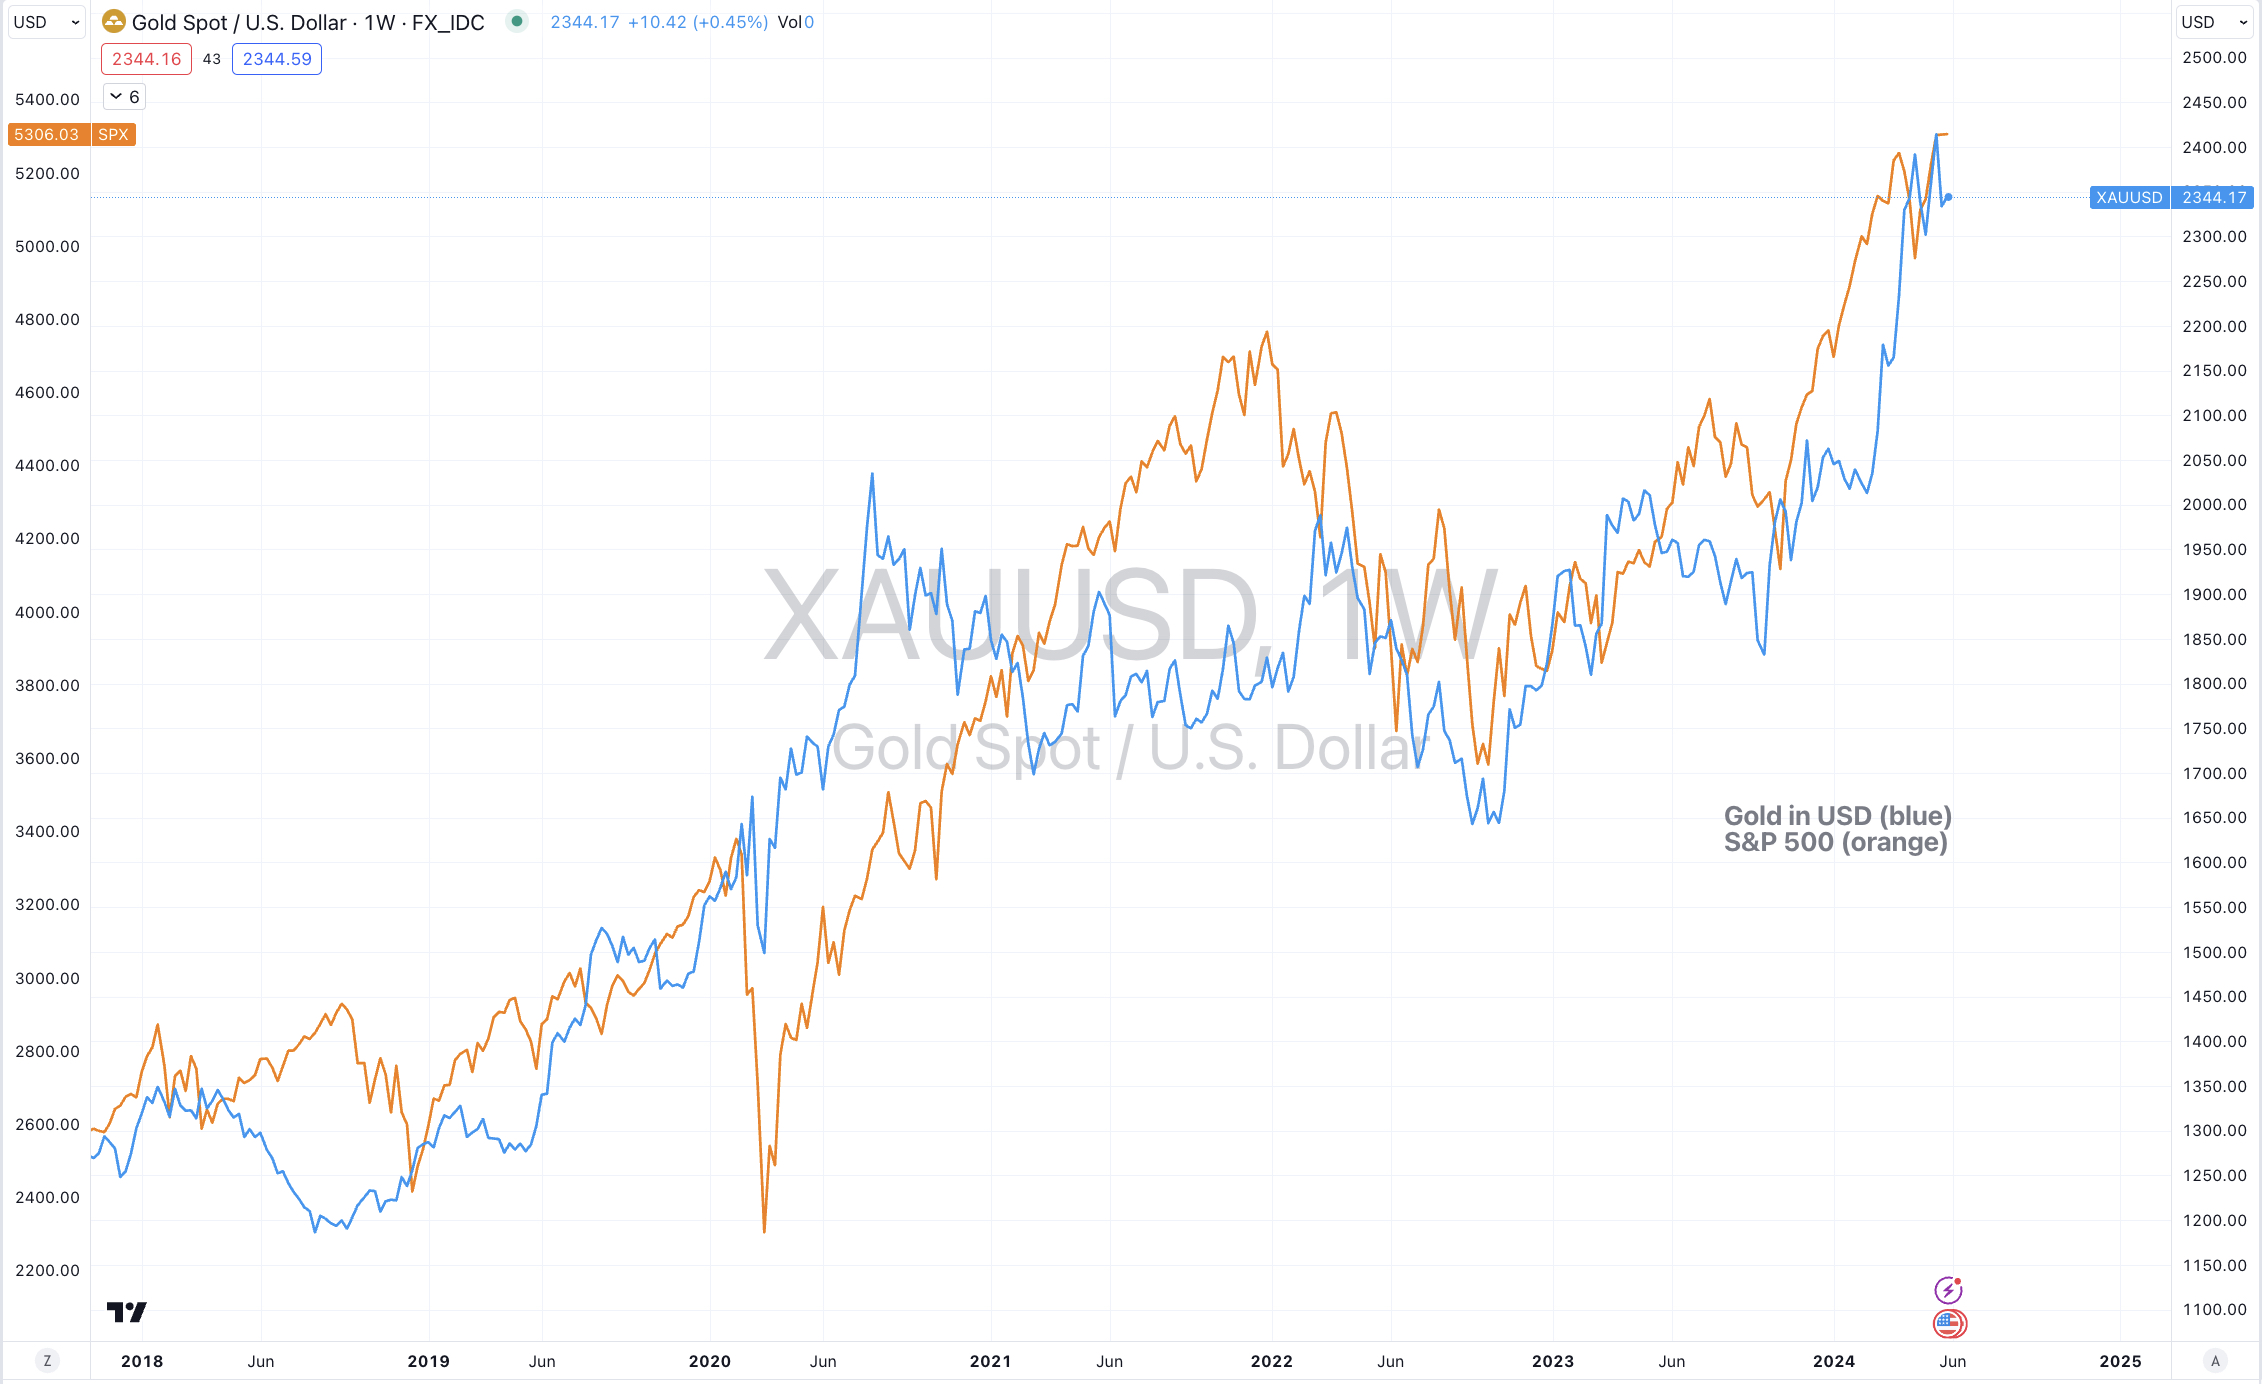
I recall ‘gold bugs’ commonly telling us that owning Gold is a hedge against inflation and a weak economy and stock market.

Lately, that story hasn’t been applicable.

Just keep this in mind when the next time that the financial media try to frame it as so.

May 29, 2024
by Rob Zdravevski
rob@karriasset.com.au

Screenshot
Screenshot

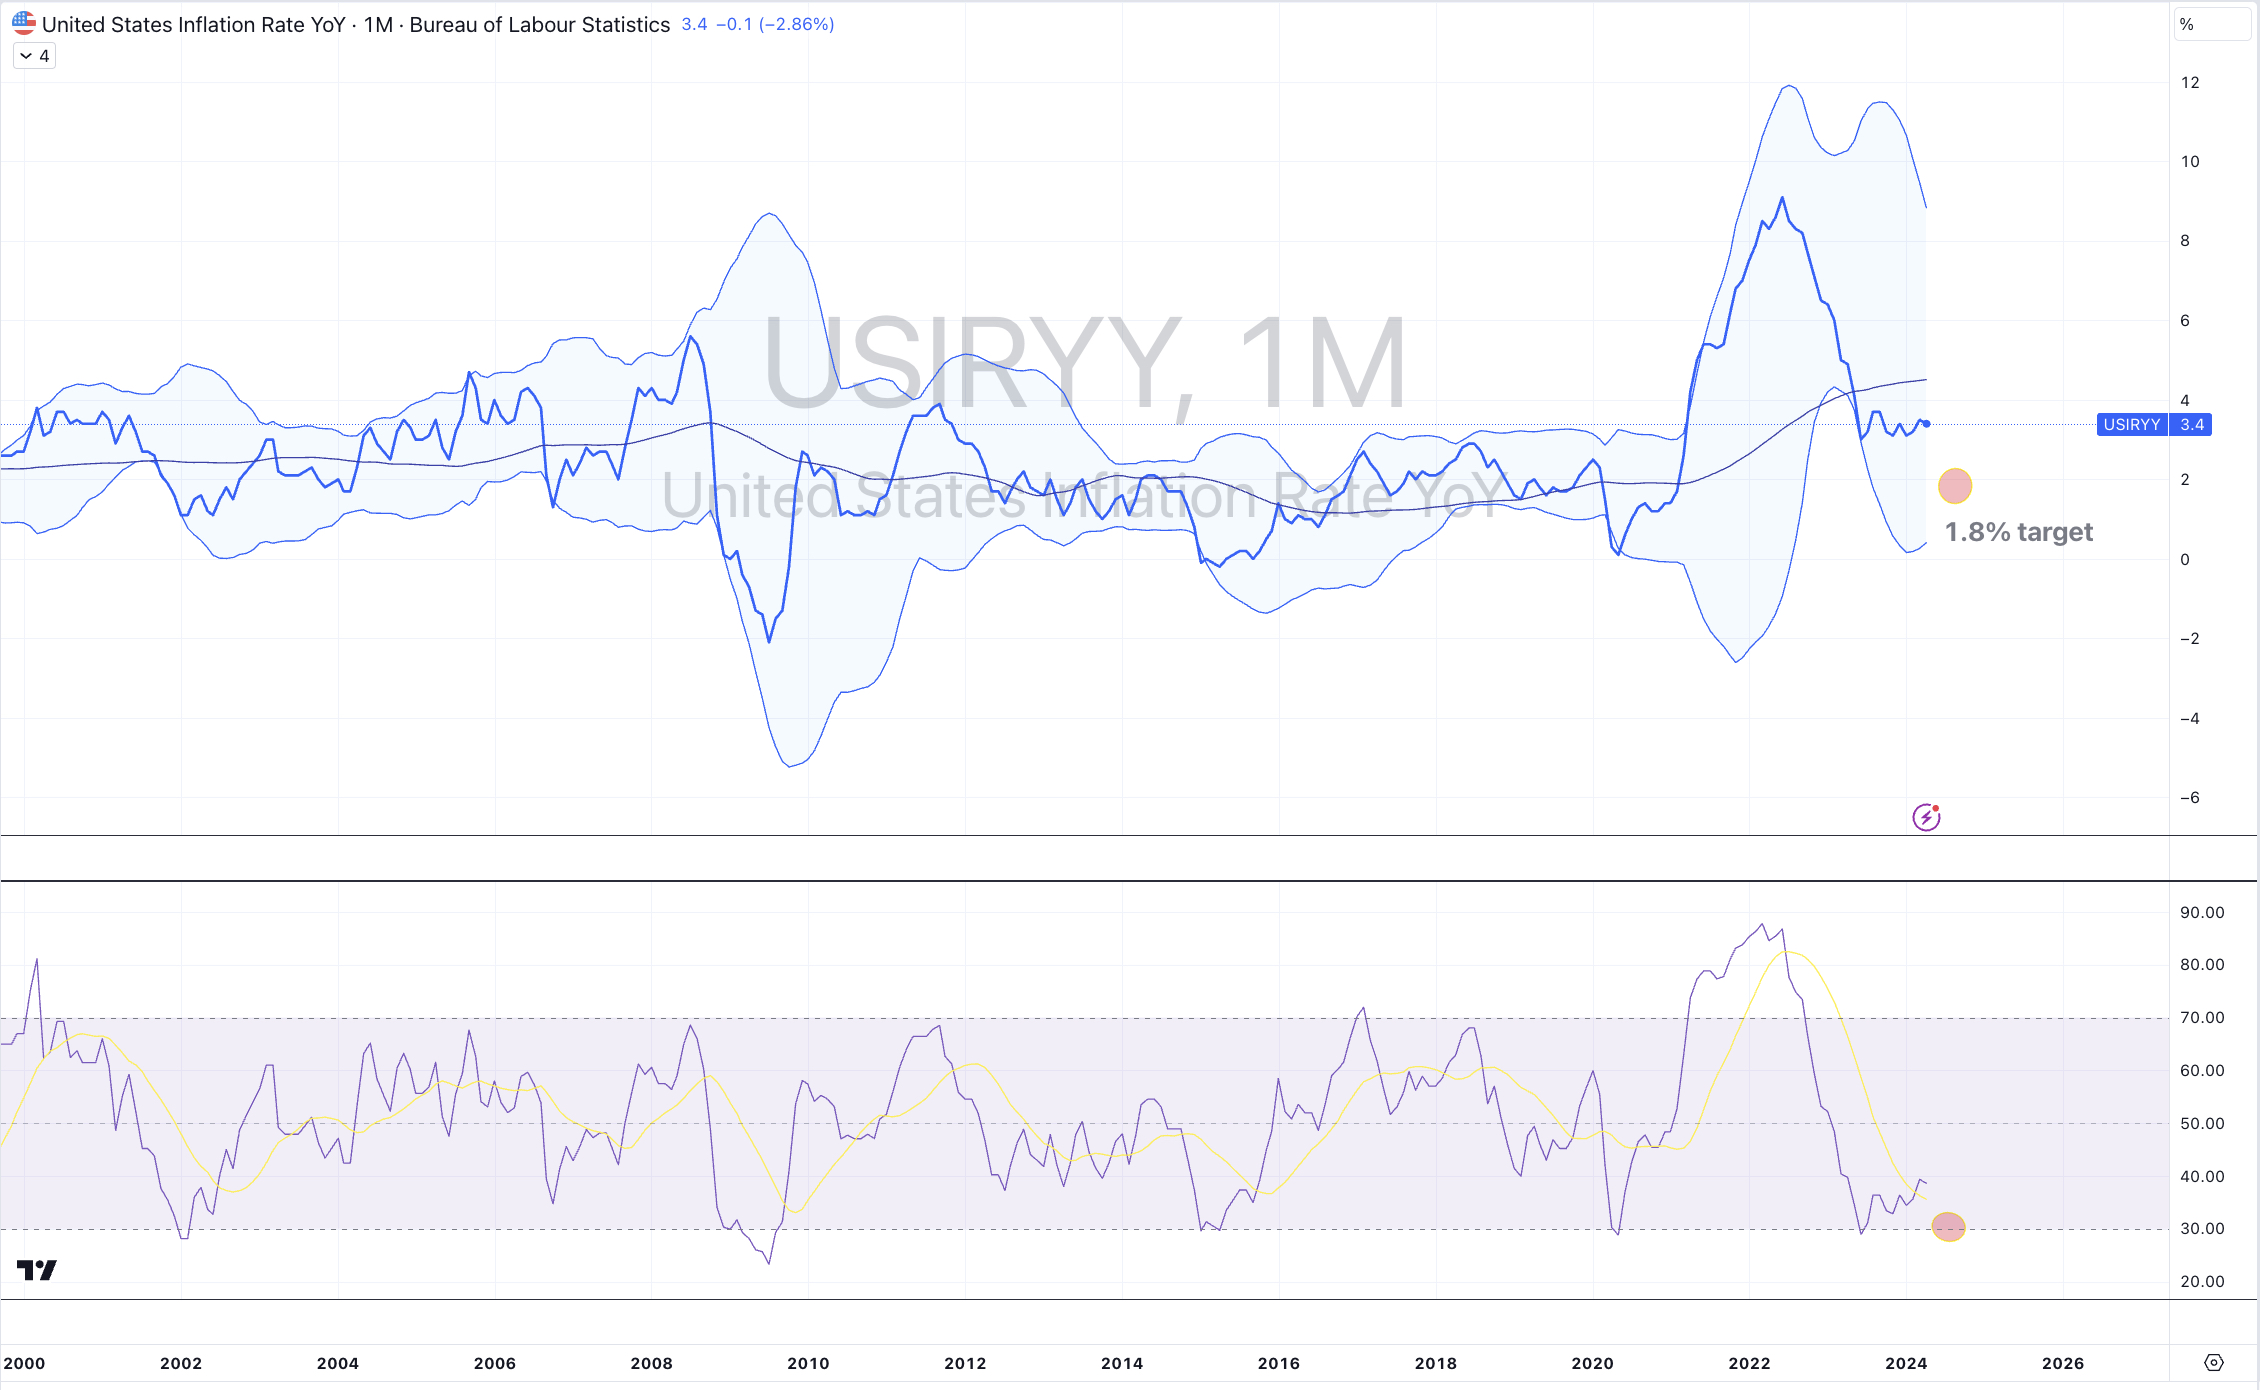
U.S. inflation to halve again

I think U.S. inflation can still decline to the 1.8% mark, somewhere around October 2024……

and all that comes with that for interest rates, commodity prices, growth equities and/or commercial real estate.

May 20, 2024

by Rob Zdravevski

rob@karriasset.com.au

For my past quips, search “inflation” at https://robzdravevski.com/?s=inflation

Screenshot

Macro Extremes (week ending April 19, 2024)

A weekly Macro, Cross Asset review of prices trading at extremes which may generate future investment ideas and opportunities.

The following assets (on a weekly timeframe) either registered an Overbought or Oversold reading and/or have traded more than 2.5 standard deviations above or below its rolling mean.

Extremes “above” the Mean (at least 2.5 standard deviations

U.S. 5-7 year corporate bond yield 

Australian, Brazilian, Chilean, Japanese, South Korean and U.S. 10 year government bond yield 

Japanese 2 year government bond yields 

U.S. 7 year government bond yields 

U.S. 20 and 30 year government bond yields 

TBT

U.S. 5 year government bond yield minus U.S. 5 year inflation breakeven rate

U.S. 5 year government bond yield minus U.S. 3 month bill yield

U.S. 10 year government bond yield minus U.S. 10 year inflation breakeven rate

Gold Volatility Index

Cocoa

Nickel

Overbought (RSI > 70)

U.S. 10 year bond yield minus Australian 10 year bond yield 

U.S. 10 year bond yield minus German 10 year bond yield 

U.S. 10 year bond yield divided by Australian 10 year bond yield 

Gold in CHF

CRB Index

Italy’s MIB

Russia’s MOEX 

And Pakistan’s KSE Index

The Overbought Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)

Coffee (Arabica)

Coffee (Robusta)

Aluminium

Copper

Tin

Silver in AUD and USD

and Gold as priced in AUD, CAD, EUR, GBP, USD and ZAR

Extremes “below” the Mean (at least 2.5 standard deviations)

IEF

IEI 

SHY

TLT

Australia 10 year yield minus U.S. 10 year yield

Urea (U.S. Gulf)

CAD/USD

GBP/USD

PHP/USD

DKK/USD

INR/USD

KRW/USD

SEK/USD

Dow Jones Transports

And Thailand’s SET Index

Oversold (RSI < 30)

Chinese 10 year government bond yields

Australian Coking Coal

Lithium Hydroxide

The Oversold Quinella – Both Oversold and Traded at < 2.5 standard deviations below the weekly mean)

Lumber

BRL/USD

IDR/USD

Notes & Ideas:

Government bond yields rose.

Chilean 10’s have risen for 6 consecutive weeks and have risen for 10 of the past 11.

Across the curve, British yields have climbed for 4 straight weeks as have South Korean and Japanese 10’s.

And Russian 10 year bond yields aren’t overbought anymore.

Equities broadly fell everywhere…..

with the exception of Chinese stocks and U.S. banks.

Impressively the Dow Jones Industrials were flat for the week.

The Russell 2000 has declined 2.8% for 3 consecutive weeks, enough to see it touch its 200 week moving average.

The DAX fallen for 3 straight weeks, while Copenhagen and Switzerland’s SMI have done so for 4 weeks.

Oslo broke its 7 week winning streak after last week’s posting of an outside bearish reversal.

And South Africa broke its 4 weeks winning streak.

Commodities were mixed.

We saw strength in base metals, softs and coals, again.

Weakness was seen in Oils, Lumber, Cotton, Soybeans, Sugar and the PGM’s.

Biodiesel and Brent Crude Oil isn’t overbought this week.

Gold, Aluminium, Copper, Coffee, Tin and Silver all appear in the overbought quinella column this week.

Gold’s weekly winning streak is at 5 while Silver has risen for 7 of the past 8 weeks.

Coffee prices were amongst the largest gainers for the week, again. Robusta Coffee has risen 31% over the past 8 weeks.

Cotton has fallen for 6 straight weeks, while Lumber’s declining streak is at 4 week.

Gasoline broke its 5 week winning streak.

The LNG JKM price (in Yen) has risen 20% over the past fortnight.

Cocoa has been overbought for 26 weeks, while putting together a recent 9 week winning streak.

Cocoa remains more expensive than Copper.

Aluminium has risen for 8 straight weeks, rising 24% over that time.

And Lithium Hydroxide has now spent 40 consecutive weeks in weekly oversold territory, however it rose 8%.

Currencies are seeing continued action.

U.S. strength is keeping many reciprocals in oversold territory.

The AUD and the Yen were weaker.

The CAD was firmer as was the Euro.

And the BRL has fallen for 7 straight weeks against the USD.

The larger advancers over the past week comprised of;

Australian Coking Coal 5.7%, Aluminium 10%, Baltic Dry Index 11%, Cocoa 9.4%, China Coking Coal 4.2%, Lean Hogs 2.5%, Copper 5.6%, Coffee 5.2%, JKM LNG in Yen 7.5%, Tin 3.5%, Newcastle Coal 6%, Nickel 9.5%, Robusta Coffee 4.7%, Shanghai Iron Ore 2.1%, Silver in AUD 3.6%, Silver in USD 2.9%, Gold in AUD 2.8%, Gold in EUR 1.9%, Gold in GBP 2.7%, Gold in USD 2.1%, Oats 2%, Rice 7.5%, Shanghai Composite 1.5%, CSI 300 1.9%, KBW Bank Index 2%, Chian A50 3.4% and Pakistan’s KRE Index rose 1.7%.

The group of largest decliners from the week included;

WTI Crude Oil (3.4%), Cotton (4.5%), Heating Oil (5.4%), Lumber (5.9%), Lithium (3.4%), Orange Juice (3.2%), Palladium (3.1%), Platinum (5.8%), Gasoline (3.3%), Biodiesel (2%), Sugar (3.5%), S&P GSCI (1.4%), Brent Crude Oil (3.3%), Gasoil (7%), Soybeans (2%), All World Developed ex USA (2.3%), AEX (2.7%), Budapest (3.3%), DJ Transports (2.7%), HSCEI (2.3%), Hang Seng (3%), IDX (4.4%), S&P SmallCap 600 (1.2%), Russell 2000 (2.8%), Nasdaq Composite (5.5%), KOSPI (3.4%), FTSE 250 (1.7%), S&P MidCap 400 (2.2%), Nasdaq Biotech (3.1%), Nasdaq 100 (3.4%), Nikkei (6.2%), Nifty (1.7%), Oslo (2.5%), PSE (3.3%), J’burg 40 (2.7%), SET (4.6%), SOX (9.2%), Chile (2.9%), S&P 500 (3.1%), TAIEX (5.8%), FTSE 100 (1.3%), Vietnam (8%), ASX 200 (2.8%), ASX Materials (2.2%), ASX Industrials (2.9%) and the ASX Small Caps fell 3.9%

April 21, 2024

by Rob Zdravevski

rob@karriasset.com.au

The S&P 500 rally continues when…..

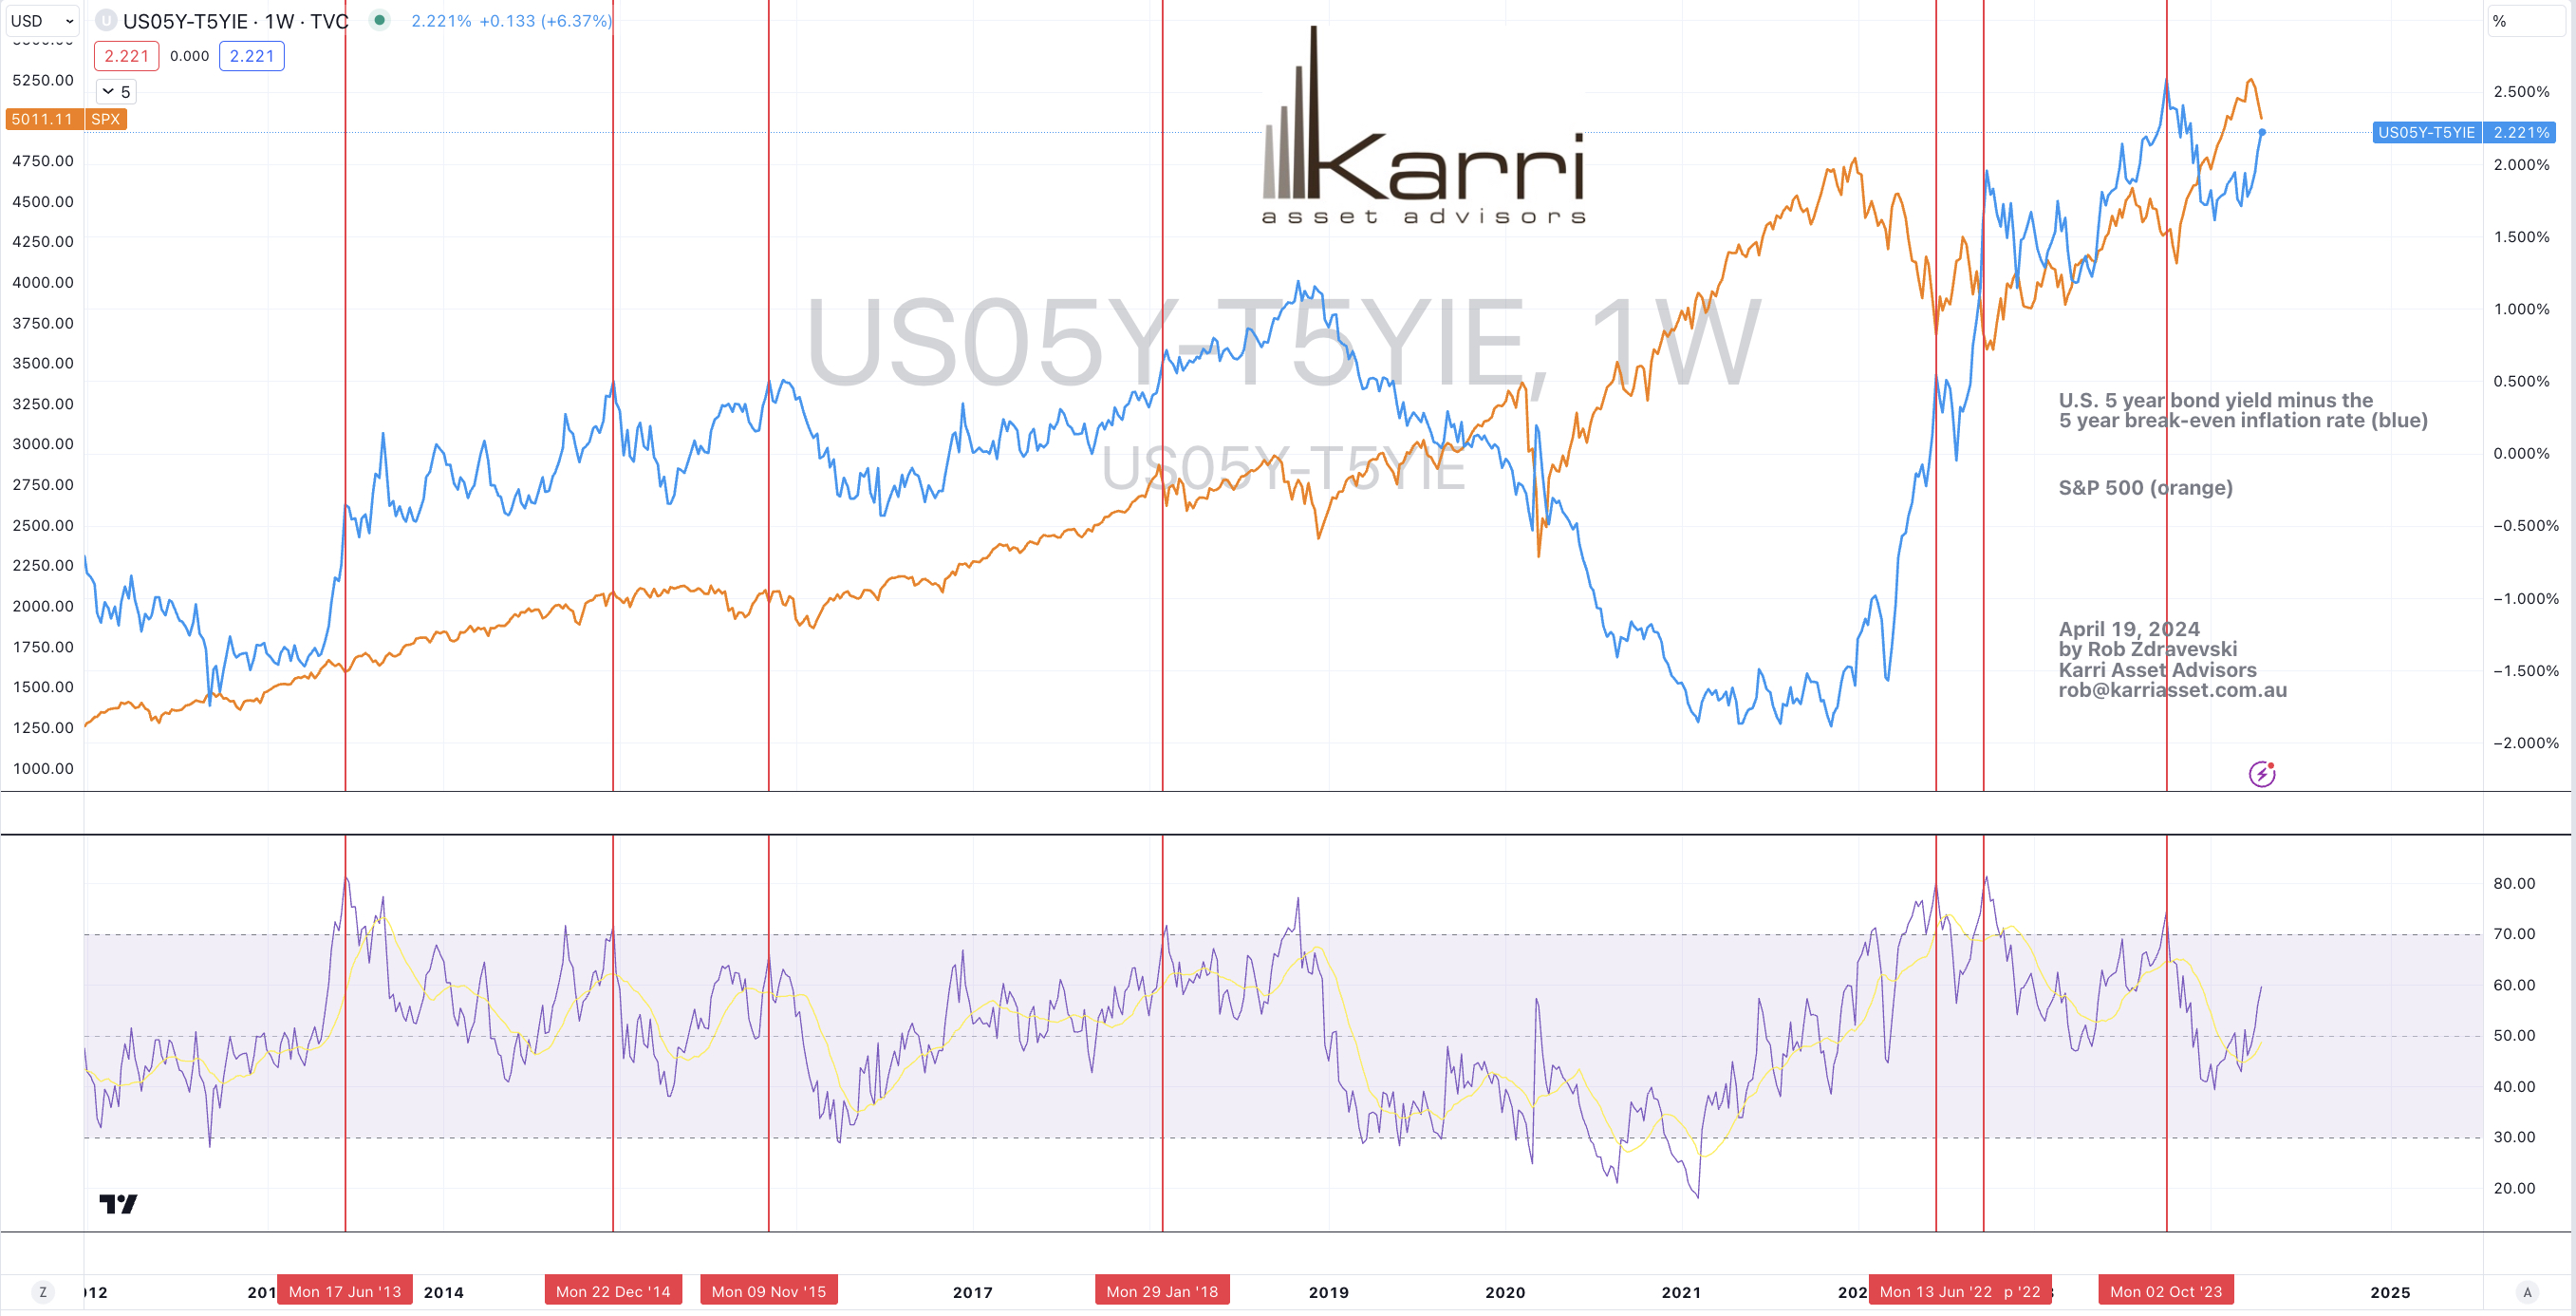
Here’s one for boffins;

My study of the U.S. 5 year government bond yields minus the 5 year breakeven inflation rate is close to hitting a combination of metrics which increases probability that the S&P 500 commences a new or extends an existing rally.

The red vertical lines denote previous such moments.

April 19, 2024

by Rob Zdravevski

rob@karriasset.com.au

Screenshot

More on British inflation

I am posturing for higher #inflation rates, again.

My expectations (found in my historical posts) for ‘lower’ inflation has occurred and is as good as being completed.

Following up my note dated April 11, 2024, suggesting the irrelevance of the U.K. March inflation report,

While inflation has abated, now it doesn’t matter so much whether this month’s #UnitedKingdom inflation rate of 3.2% is lower than last months (year on year) figure of 3.4%.

Keep in mind, that prices are still rising and I think that is mostly a cause of capacity and supply constraints rather than notable demand.

My thinking is that #UK inflation will move to 5% rather than 2%.

Slowing demand means companies will increases prices for goods and services, in order to maintain their shrinking margins.

April 17, 2024

by Rob Zdravevski

rob@karriasset.com.au

Screenshot

Macro Extremes (week ending April 12, 2024)

A weekly Macro, Cross Asset review of prices trading at extremes which may generate future investment ideas and opportunities.

The following assets (on a weekly timeframe) either registered an Overbought or Oversold reading and/or have traded more than 2.5 standard deviations above or below its rolling mean.

Extremes “above” the Mean (at least 2.5 standard deviations

U.S. 5-7 year corporate bond yield 

Brazilian 10 year government bond yield 

Japanese 2 and 10 year government bond yields 

TBX

U.S. 5 year government bond yield minus U.S. 5 year inflation breakeven rate

U.S. 5 year government bond yield minus U.S. 3 month bill yield

U.S. 2, 3, 5, 7, 10 and 20 year government bond yields 

U.S. 10 year government bond yield minus U.S. 10 year inflation breakeven rate

Bloomberg Commodity Index

U.S. Dollar Index

Gold Volatility Index

Copper

AUD/JPY

AUD/THB

COP/USD

Austria’s ATX

Russia’s MOEX

And India’s NIFTY 50

Overbought (RSI > 70)

Russian 10 year bond yield 

U.S. 10 year bond yield minus Australian 10 year bond yield 

U.S. 10 year bond yield divided by Australian 10 year bond yield 

Aluminium

Cocoa

Biodiesel 

CRB Index

Brent Crude Oil 

Coffee (Robusta)

AEX

Budapest

Italy’s MIB

TAIEX

And Turkiye’s BIST 100

The Overbought Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)

U.S. 10 year bond yield minus German 10 year bond yield 

Coffee (Arabica)

Tin

Silver in AUD and USD

Gold in AUD, CAD, CHF, EUR, GBP, USD and ZAR

Pakistan’s KSE equity index

Extremes “below” the Mean (at least 2.5 standard deviations)

IEF

IEI 

SHY

Lumber

Urea (U.S. Gulf)

Oats

EUR/USD

GBP/USD

JPY/AUD

DKK/USD

HKD/USD

KRW/USD

SEK/USD

Oversold (RSI < 30)

Australia 10 year yield minus U.S. 10 year yield

Chinese 10 year government bond yields

Australian Coking Coal

Chinese Coking Coal

Lithium Hydroxide

Shanghai Rebar

The Oversold Quinella – Both Oversold and Traded at < 2.5 standard deviations below the weekly mean)

None 

Notes & Ideas:

My immediate suggestion is to compare last week’s edition to this one. Readers will note many changes.

It seemed as government bond yields rose, which is mostly true in Australia, USA, Great Britain, Japan, South Korea and New Zealand……

However, we also saw declining yields in Switzerland, Spain, Germany, France & China.

Last week, I wrote, “many yields are showing signs of breaking north of their recent sideways pattern”. This was certainly the case.

Bonds provided an equal amount of action this past week, with my spreads and bond ETF’s entering the list.

The big news in Equities was observing many indices leaving overbought territory as prices declined.

A few winner still managed to appear in this week’s list, albeit only several.

Oslo is in a 7 week winning streak, while Mexico’s main index broker its 4 week run of consecutive higher prices. The latter also posted an outside bearish reversal week.

Toronto’s TSX broke its 8 week winning streak and posted a bearish outside reversal week.

South Africa has risen for 4 weeks straight as has the TAIEX. The latter has climbed higher for 12 of the past 13 weeks.

And last week’s reference to those equity indices which posted bearish outside reversal week’s held true.

Commodities were mixed.

We saw strength in precious metals, base metals, softs and coals.

It is worthy to note that many commodities which appear in todays overbought section saw those extremes tickled earlier in the week, before easing off in the last couple days.

Iron Ore isn’t overbought.

Gold prices across various currencies remains overbought.

Interestingly, Platinum has risen 10% over the past 3 weeks while Gold’s advance (in USD) has been 8%.

Renewed media noise about the rise in oil, gold, silver and copper prices coincides with them trading at overbought extremes.

Coffee prices were amongst the largest gainers for the week, again. Robusta Coffee has risen 26% over the past 7 weeks.

While it remains oversold, China Coking broke is 7 week losing streak.

Rice broke its 6 week losing streak with a 7% rise, nearly halving the 15% decline seen during that declining trend.

Oats mostly recovered last week’s 7% decline. 

Cotton has fallen for 5 straight weeks, inversely, Gasoline has risen for 5 consecutive weeks.

Cocoa has been overbought for 25 weeks, while putting together a recent 7 week winning streak.

Aluminium has risen for 7 straight weeks, rising 14% over that time.

And Lithium Hydroxide has now spent 40 consecutive weeks in weekly oversold territory, however it rose 8%.

Currencies extended last week’s activity with U.S. strength sending many reciprocals into oversold territory.

The effect of a rising USD, rendered weakest in the AUD and many others.

In its own right, the CAD was stronger.

The Yen was stronger against all, except the USD.

The Euro was weaker against everyone.

The British Pound was mixed for the week, again.

The BRL has fallen for 6 straight weeks against the USD.

And the Kiwi broke its 6 weeks of consecutive versus the Aussie.

The larger advancers over the past week comprised of;

Aluminium 1.7%, Rotterdam Coal 2.9%, Baltic Dry Index 6.2%, Cocoa 6.9%, Coffee 3.7%, JKM LNG in Yen 12.9%, Lithium 8.2%, Tin 15%, Newcastle Coal 2.7%, Orange Juice 2.6%, Palladium 5.2%, Platinum 6.5%, Shanghai Iron Ore 6.1%, Dutch TTF Gas 15.5%, Silver in AUD 3.3%, Silver in USD 1.4%, Gold in AUD 2.4%, Gold in USD 0.6%, Oats 6.1%, Rice 6.6%, Robusta Coffee 4.2%, KSE 2.8%, Oslo 1.8%, SET 1.5%, TAIEX 2%, FTSE 100 1.1%, Vietnam 1.7%, ASX Materials 2.9%, BIST 2% and the ASX Industrials rose 1.2%.

The group of largest decliners from the week included;

WTI Crude Oil (1.4%), Cotton (4.2%), Heating Oil (3.2%), Lumber (5.6%), Biodiesel (2.1%), Sugar (7%), Raw Sugar (1.7%), Urea U.S. Gulf (5.6%), Gasoil (2.7%), Urea Middle East (2.8%), Wheat (2%), Shanghai (1.6%), CSI 300 (2.6%), All Developed World ex USA (1.3%), KBW Bank Index (3.7%), China A50 (3%), DJ Industrials (2.7%), IBEX (2.1%), Indonesia (2.6%), S&P SmallCap 600 (2.9%), Russell 2000 (2.8%), Nasdaq Composite (0.5%), KRE Regional Banks (3.5%), S&P 400 Midcaps (2.9%), Mexico (2.6%), Nasdaq Biotechs (1.9%), SOX (1.5%), S&P 500 (1.6%), Nasdaq Transports (3.1%) and Toronto’s TSX fell 1.6%.

April 14, 2024

by Rob Zdravevski

rob@karriasset.com.au

U.K. inflation to see 5%, not 2%

It doesn’t matter if the March 2024 #UnitedKingdom inflation rate falls from 3.4% down to 3% or 2.6%……

This is small beans.

It is nearer the lower end of its travels.

The big call to make is when the #inflation rate is trading at ‘extremes’ to my illustrated moving average, appearing in the chart below.

Much like my American inflation note published yesterday, I think there is greater probability that #UK inflation rate should travel towards 5% rather than 1.8%……

and all that comes with it for interest rates and the equity prices of high growth (unprofitable) companies.

Incidentally, the U.K. inflation rate for March 2024 is due to be released on April 17th.

April 11, 2024

by Rob Zdravevski

rob@karriasset.com.au

Karri Asset Advisors

Screenshot

Macro Extremes (week ending March 22, 2024)

A weekly Macro, Cross Asset review of prices trading at extremes which may generate future investment ideas and opportunities.

The following assets (on a weekly timeframe) either registered an Overbought or Oversold reading and/or have traded more than 2.5 standard deviations above or below its rolling mean.

Extremes “above” the Mean (at least 2.5 standard deviations

US10 year minus Australian 10 year yield spread

US10 year divided by Australian 10 year yield spread

WTI Crude Oil

Copper

Tin

S&P GSCI

Brent Crude Oil

Silver in AUD, USD & EUR

Gold in USD

AUD/JPY

AUD/THB

FTSE 100

Overbought (RSI > 70)

Biodiesel

Robusta Coffee 

AEX

Budapest

CAC 30

DAX

Dow Jones Industrial Average

Italy’s MIB

Nasdaq Composite

Nikkei 225

Stockholm

Philadelphia SOX

TAIEX

Nasdaq Transports

Toronto’s TSX

Vietnam

And the S&P 500 Index

The Overbought Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)

Russian 10 year bond yield 

Gold in AUD, CAD, EUR, GBP & CHF

Cocoa

IBEX

Extremes “below” the Mean (at least 2.5 standard deviations)

AU10Y – US10Y yield

Australian Coking Coal

CHF/AUD

Chinese RMB

INR/USD

Oversold (RSI < 30)

Chinese 10 year government bond yields

Lithium Hydroxide

The Oversold Quinella – Both Oversold and Traded at < 2.5 standard deviations below the weekly mean)

None

Notes & Ideas:

Government bond yields mostly fell except for the Japanese 2’s and 5’s.

The Japanese 5’s winning streak extends to 7 weeks.

Russian 10 year yields have risen for 8 consecutive weeks.

The Chinese 10’s are the notable oversold extreme in this week’s list.

Equities were higher.

Shanghai is in a 6 week winning streak while the CSI 300 broke its 5 week advance.

Toronto’s has sneakily put together 6 straight rising weeks. 

The DAX is in a 7 week winning streak, the MIB advance extends to 8 consecutive weeks.

The Nasdaq is 34% above its 2090 week moving average while the S&P 500 is 27% above the same measure.

Egypt’s 30 Index isn’t overbought anymore.

Spain’s IBEX has registered an overbought quinella as it trades at its highest point since June 2017.

The FTSE 100 returns to the overbought territory.

The CAC and DAX are still making new all-time highs.

The Dow Jones Industrial Average re-enters overbought territory.

And Italy’s MIB has traded to its highest point since May 2008.

Commodities were generally higher.

While Rotterdam Coal is in a 5 week winning streak, Most coal prices had a terrible week.

Crude Oil makes a return to overbought land, while Copper and Tin extend their stay there.

Rubber isn’t overbought this week.

Gold prices across various currencies remains overbought.

Cocoa has now spent 22 weeks in overbought land.

Nickel broke its 5 weeks winning streak.

Uranium and the Baltic Dry Index broke their 6 week losing streaks.

And Lithium Hydroxide has now spent 37 consecutive weeks in weekly oversold territory.

Currencies saw a firmer CAD again as was the USD.

The AUD was firmer against all except versus the Yen.

The Euro was mixed.

The Yen as did the Kiwi.

The latter is in a 4 week losing streak again the AUD.

The larger advancers over the past week comprised of;

Aluminium 2.8%, Cocoa 11.5%, LNG JKM in Yen 4%, Dutch TTF Gas 2.8%, Uranium 4%, Gold in CHF 2%, Wheat 5%, All World Developed ex USA 1.2%, AEX 2.9%, Austria 2.6%, KBW Bank 3.7%, DAX 1.5%, DJ Industrials 2%, DJ Transports 3.3%, IBEX 3.3%, Nasdaq Composite 2.9%, KOSPI 3.3%, S&P MidCap 400 2.2%, Nasdaq 100 3%, Nikkei 225 5.6%, Russell 2000 1.5%, SOX 3.2%, S&P 400 2.3%, TAIEX 2.8%, Nasdaq Transports 2.9%, FTSE 100 2.6%, ASX 200 1.3%, BIST 3.2% and the ASX Materials rose 2.4%

The group of largest decliners from the week included;

Australian Coking Coal (2.8%), China Coking Coal (2.8%), Rotterdam Coal (2%), Baltic Dry Index (5.5%), Cotton (2.6%), Lean Hogs (2.6%), Copper (3%), Heating Oil (2.4%), Tin (2.3%), Newcastle Coal (4.3%), Nickel (2%), Palladium (8.4%), Platinum (4.8%), Gasoil (1.8%), Silver (2%), Oats (2.1%), Rice (2.7%) and Egypt’s 30 equity index tanked 7.2%.

March 24, 2024

by Rob Zdravevski

rob@karriasset.com.au