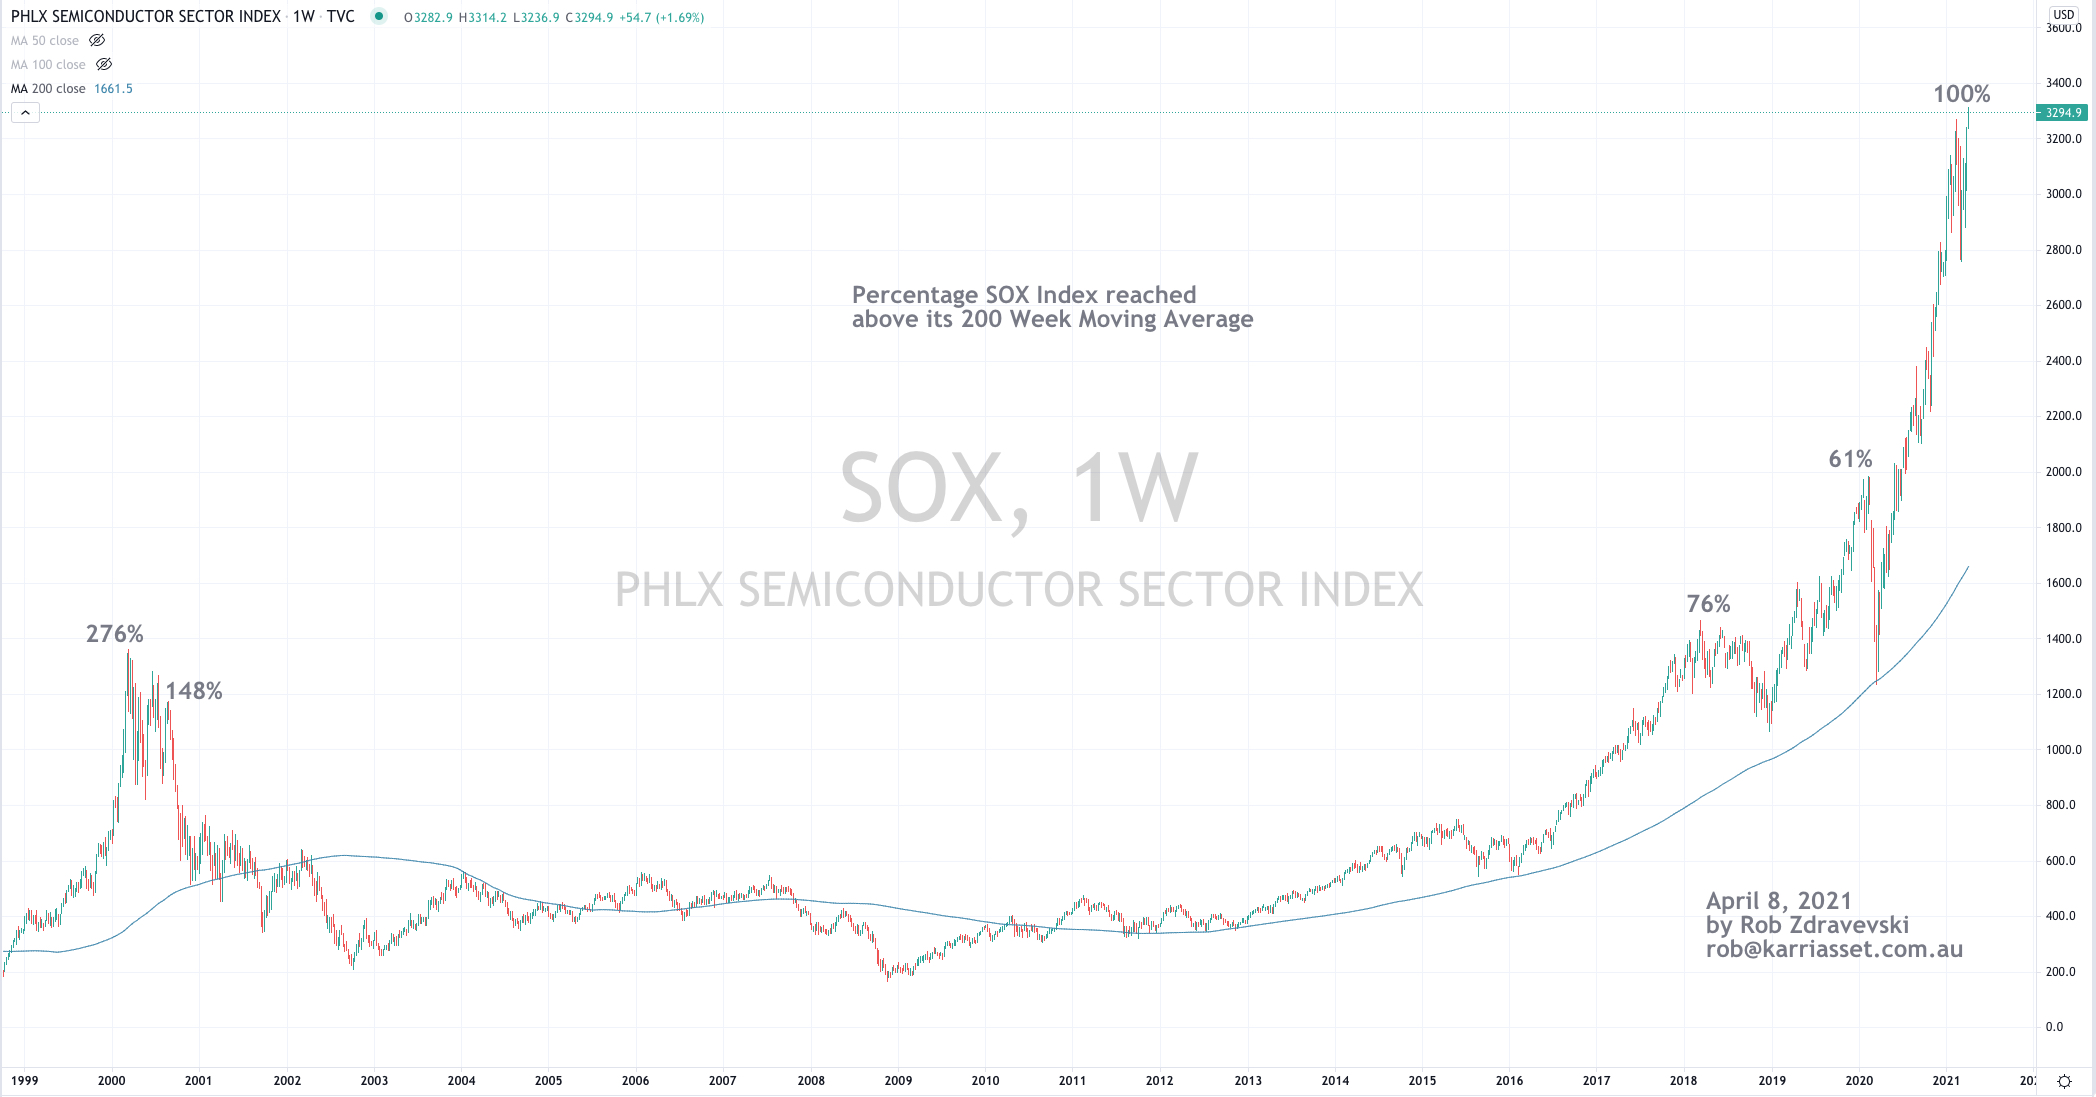
Parabolic? Mean Reversion? A semiconductor chip shortage is news recently, but going “long” now is something some may be doing at the wrong end of the cycle or story….
The SOX index is now trading 100% above its 200 Week Moving Average….that’s its weekly average, not daily.
This week’s list has shortened suggesting that many assets breaching ‘extremes’ have since eased to resume trading within a normal range’.
And so, during the past week, the following assets (on a weekly timeframe) registered an Overbought reading or traded more than 2.5 standard deviations below its rolling mean
.
Extremes “above” the Mean (at least 2.5 standard deviations)
<None>
Overbought (RSI > 70)
Canadian 10 year bond yields (for 7th consecutive week)
Korean 10 year bond yields
U.S. Government 5 & 10 year bond yields (for 7th consecutive week)
Aluminium (for 6th consecutive week)
Lean Hogs (for the 7th consecutive week and its highest price since October 2014)
Corn (for the 16th consecutive week & trading 46% above its 200 Week Moving Average)
AUD/JPY (an important risk indicating currency)
USD/TRY (Turkish Lira)
USD/DKK (a weaker Danish Krone makes your Vestas wind turbines, Lurpak butter & LEGO cheaper)
U.S. KBW Banking Index (5th consecutive week)
Nasdaq Transportation Index (4th consecutive week)
Dow Jones Transport Index
S&P Mid Cap 400 (4th consecutive week)
Sweden’s OMX 30 Index (4th consecutive week)
Bitcoin, Ethereum & Monero
The Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)
USD/HKD
USD/JPY
(in both cases, suggesting the USD is strong versus the weakness of the opposing currencies)
Assets (securities) within my immediate universe which touched the other side of the extreme, being Oversold (where the RSI is < 30) or were at least 2.5 standard deviations below its mean are;
EUR/GBP
EUR/USD
(meaning a weak EUR suggests selling British Pounds or U.S. Dollars in order to accumulate Euro)
Cocoa
Notes & Ideas:
Last week’s edition was laden with commentary and ideas still worthy of noting and digesting.
Assets such as Tin & Copper have pulled back from recent loftiness, thus t’s worthy to highlight the streaks in this weeks list where the ‘extremes’ seem to be extended, such as….Transports, Banking, Aluminium, U.S. MidCaps, Canadian and American Government bond yields & Lean Hogs.
I am paying too much for bacon !
Some other macro ideas are;
Buy U.S. 5 & 10 Year Bonds (expecting prices to rise and yields to fall)
Sell USD / Buy Yen (there are some interesting Japanese equity ideas in my equities universe)
I think the Mid-Cap 400 and , U.S. banks & Transports are next to pullback.
That 2 year and 10 year bond yield spread has fallen from 1.59% to 1.51%
And, Bitcoin continues to trade at 430% above its 200 Weekly Moving Average.
A taste of capital market observations and trades I may position for;
EUR/GBP is nearly Oversold, should occur in the coming weeks, near 0.8512 level, then selling British Pounds and Buying Euro’s would be the trade.
Looking for leg lower in Natural Gas.
Oil has seen a healthy mean reversion, maintaining bullish stance. $58.80 in Brent means adding to Long’s.
Short in the Semiconductor Index (SOX) makes for market hedge?
Shorting Corn and/or Soybeans
The Gold Volatility Index is close to Oversold. If the RSI touches 30, probability of Gold rally increases. Been accumulating gold related securities for 6 weeks.
Although watch the price action in Silver. Silver’s trend is bearish.
Looking to re-enter the Long Platinum trade at lower prices.
I see risk in Iron Ore (62% Fe, CFR China) prices to $125 and $118. Its currently trading at $167
ASX 200 poised to break ‘hard’ either way, with odds suggesting higher prices, but let’s wait for the break.
Although some major equity indices made higher weekly closing highs, some made made lower highs and lower lows.
French 10 Year bond yields negative since June 2020.
German 10 bonds have been negative since April 2019
During the past week, the following assets (on a weekly timeframe) registered an Overbought reading or traded more than 2.5 standard deviations below its rolling mean.
No assets (securities) in my immediate universe touched the other side of the extreme being Oversold (where the RSI is < 30) or were at least 2.5 standard deviations below its mean.
Extremes “above” the Mean (at least 2.5 standard deviations)
USD/TRY, meaning the Turkish Lira weakened notably.
Overbought (RSI > 70)
Canadian 10 year bond yields
U.S. Government 5 & 10 year bond yields (for 6th consecutive week)
Aluminium (for 5th consecutive week)
Lean Hogs (reaching their highest price since October 2014)
Copper (and on a longer-term ‘Monthly’ basis, it’s at most overbought since September 2006)
Corn
Soybeans
USD / JPY
U.S. KBW Banking Index (4th consecutive week)
Nasdaq Transportation Index
S&P Mid Cap 400 (3rd consecutive week)
Sweden’s OMX 30 Index
The Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)
Dow Jones Transport Index
Notes & Ideas:
There are many trade ideas to extract from the list such as an expected mean reversion in Aluminium, Copper and Pork prices which would benefit product manufacturers as falling prices would improve their margin (lowering ‘input’ costs) while Aluminium producers, Copper miners and Pig farmers should lock in their gains as prices are hitting extended peaks.
Weekly readers would’ve noticed Corn and Soybeans have also been in the ‘extreme high’s’ list for the past few weeks.
A decline and mean reversion in Corn would be welcomed news for cereal makers such as Kellogg.
Lower soybean prices means poultry farmers get to buy cheaper soybean meal, of which their industry consumes 60% of it, as feed.
Some other macro ideas are;
Buy U.S. 5 & 10 Year Bonds (expecting prices to rise and yields to fall)
Sell USD / Buy Yen (there are some interesting Japanese equity ideas in my equities universe)
Specific stock and other ideas are being sent to clients over the weekend.
Many of the recently ‘Overbought’ bonds, commodities, currencies and equity indices have now eased away from those extremes readings.
The Russell 2000 was hitting such extremes 2 weeks ago and has since declined 5%.
I think the Mid-Cap 400 and , U.S. banks & Transports are next to pullback.
Tin, the Nikkei 225, the CRB Index, AUD/JPY have also fallen from those Overbought levels.
Wheat has declined 10% and Natural Gas more so, since their “quinella’ readings 6 weeks ago.
And most notably, Australian, UK & Korean bond yields have fallen 5%-10% for the week.
The spread between the 2 year and 10 year bond yield continues to widen, now sitting at 1.53%, something not seen since September, 2015.
Although the bigger macro story is not the ’steepening’ of the yield curve, it is more so that 10 Year bond yields have Quadrupled in the past 12 months, as described in a recent thesis.
The crowded trade is to Short 10 year Government Bonds. I like the opposite with my preference being to Buy the 5 Year bond.
And, Bitcoin is trading at 428% above its 200 Weekly Moving Average, down from last week’s 448% reading.
At some time during the past week, the following assets (on a weekly timeframe) registered either Overbought, Oversold or traded more than 2.5 standard deviations either side of its rolling mean.
There are no assets (securities) in my immediate universe which are either Oversold (where the RSI is < 30) and/or trading at least 2.5 standard deviations below its mean.
Everything else in my list is in the “Overbought” territory
Extremes “above” the Mean (at least 2.5 standard deviations)
USD/JPY (The Yen is weak relative to the U.S. Dollar)
Dow Jones Industrial Average (the ‘most’ since September 2018)
Overbought (RSI > 70)
AUD / JPY (for the 3rd consecutive week)
Swedish, British, New Zealand and Australian 10 year bond yields
the CRB Index and the Bloomberg Commodity Index (for the 7th consecutive week)
Copper (for the 6th consecutive week)
Tin
Lean Hogs
Corn
Soybeans
Nikkei 225
S&P MidCap 400 (2nd consecutive week)
U.S. KBW Banking Index (3rd consecutive week)
Dow Jones Transport Index (again)
Stockholm OMX 30 Index (Volvo, Assa Abloy and Electrolux have big weeks)
Bitcoin & Ethereum
The Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)
Korean 10 year bond yields
Canadian 10 year bond yields
U.S. 5 & 10 year bond yields (i.e. bonds are being sold heavily, thus inversely yields are rising)
Aluminium
Notes & Ideas:
The spread between the 2 year and 10 year bond yield continues to widen, now sitting at 1.52%, something not seen since September, 2015.
Although the bigger macro story is not the ’steepening’ of the yield curve, it is more so that 10 Year bond yields have Quadrupled in the past 12 months, as described in a recent thesis.
The crowded trade is being Short 10 year Government Bonds. I like the opposite.
Specifically, Buying the 5 Year Bond, meaning I think the yields will fall from its current 0.87% back to 0.54%.
Korean and Canadian bond yields have been overbought for 4 consecutive weeks and the U.S. 5’s and 10’s overbought streak is now at 6 weeks.
The previously unloved “long Gold” trade has garnered some popularity as Gold (in USD) held US$1,677 and risen 4% to US$1,740;
while AUD Gold bounced 3% from its A$2,189 low.
Inversely, over the past week, Crude Oil corrected its overbought ‘extreme’ by falling 11% at its lowest level. Brent never managed to close the week above $70, in order to allow it to entertain the $74, $76 and $82 region.
Accordingly, downward moves in Crude, Heating Oil and Gasoil resemble a reversion to the mean.
France’s CAC-40 and Germany’s DAX are approx. 2.5% away from recording ‘extreme’ readings.
China’s Shanghai Composite has seen its lowest weekly close since December 14, 2020.
The weak Yen encourages buying, especially using your Strong USD or AUD.
p,s, there are some interesting Japanese stocks in my equities universe.
And, Bitcoin is only trading at 443% above its 200 Weekly Moving Average, down from last week’s 500% stretch.
The latest chatter about the steepening of the yield curve between the yield of the US Government 10 year bond (minus) and the 2 year bond is no big deal.
That differential (“the spread”) is currently at 1.56%,
(that’s how much the 10 year bond is yielding above the 2 year bond and it is represented in a plotted graph, we call the yield curve)
Yes, it’s the widest spread since September 2015, but it’s not extraordinary.
It has been twice that amount (3%) on several occasions over the past 30 years. (see chart below)
There is some exaggeration about how steep the curve is…it actually isn’t.
Don’t worry too much about that yield curve at the moment.
My story is about when the spread actually touched Zero (which is when the 10 year bond was offering the same yield as the 2 year bond) and not so much the actual spread nor the yield of the 10 year bond.
And then I have added comments to what happened to the equities market afterwards.
Example #1
In April 1998 the spread touched Zero,
but the S&P 500 continued to rise until the S&P 500 peaked in March 2000; some 21 months later.
A year earlier, in April 1997, the 10 Year Bond (“the 10’s) was yielding 7%.
By April 1998 it had fallen to 5.6% (when the spread was Zero)…..
the yield would decline a little more, down to 4.4%.
By March 2000, it had climbed back to 6.66% to coincide with a peak in equities market.
Example #2
In January 2006, the spread was at Zero again, but stocks rallied for a further 17 months until the S&P 500 peaked in October 2007.
From that moment in January 2006, the 10’s rose from 4.3% to 5.3% on a couple occasions, reaching that same 5.3% peak in July 2007, just as economies were about to experience the ‘Global Financial Crisis’.
For a period of 6 weeks, the 5.3% yield did break above the downward sloping trend line (see the chart below) but the precedent of a Zero spread being registered 17 months earlier held sway.
Example #3
By December 2008, 10’s had fallen to 2% (although the spread didn’t flirt with Zero, it never went below 1.2%).
From this ebb, the yield doubled to 4% over the next 18 months (April 2010).
The stockmarket fell 20% over the next few months.
Example #4
Through stages of the GFC recovery, 10’s were back to 1.4% in July 2012.
Within the next 18 months (by December 2013), the 10’s doubled to 3%
The stockmarket rally was stifled and went sideways for 5 months.
Even though rates doubled, equities remained in a bull market because we never saw a Zero spread registered.
Equities resumed their rally as 10’s commenced a new decline in yields from 3% down to 1.7% over the next 14 months, being until January 2015.
Note: The United States Federal Reserve kept the Fed Funds Rate at Zero between 2008 and 2015.
Example #5 (the anomaly)
By July 2016, 10’s eased a little more to 1.35%. From there, they nearly doubled again (to 2.6%) within 5 months and then touched 3.2% by November 2018.
Although rates nearly trebled…..they never registered a Zero spread reading. Furthermore, the anomaly is that the 10’s yield broke above the sloping downtrend resistance line (see chart below), which gave the S&P 500 ‘carte blanche’ to rally….all until the 10’s yield crossed back beneath that (now and new) support line in the month of August 2019.
Example #6
In the next month, September 2019, saw another Zero spread registered.
While absorbing an abrupt correction, the S&P 500 has soared and continually set new all-time highs, 18 months hence.
Today, the 10’s have Quadrupled from their 0.40% March 2020 low, to its current 1.72%.
Uncannily, we are 18 months further along since the spread touched Zero and we have seen an equity market participate in extraordinary gains…….
I will re-iterate…….the interest cost of government debt has Quadrupled within 12 months.
That matters to investors and to the government servicing the interest payments.
But we are at a moment, similar to the anomaly explained in Example #5.
Forget the ’spread’ and steepening yield curve, but let’s say the 10 year bond yield reaches 2% and decisively breaks above that sloping downward line, then it’s plausible that the S&P 500 rallies for a further 18 months.
This bullish scenario may represent the ‘last leg’ in the 11 year bull run which commenced at the March 2009 low.
Although, greater probability suggests (coinciding with fundamental valuations and various sentiment and anecdotal indicators) that the quantum of quadrupling interest rates will prove a greater weight on equities plight for further gains.
This is the measured reason why I have shifted client equity portfolios to 35% cash position and hedged portfolios with put options. This was mentioned in my January 2021 newsletter.
In another review of past posts and investment calls,
the linked note talks about performance and my decision to sell some stocks which already produced very pleasing returns (you’ll see the original cost basis in the graphic within the original post).
Of the subject stocks written about, I definitely sold a couple “early”;
Zillow, which was bought at $27 AND sold at $87 and carried on climbing to $212. It’s now $138,
(in fairness, even if I held, I would’ve surely sold before $110)
PayPal was purchased at $34 then sold at $204, rallied up to $309. It’s currently trading at $238.
Spotify was dumped at $284, it did decline to $225 soon after, although rose to $370. Today’s it closed at $271 which is slightly lower than my sale price.
Docusign was sold soon after the August 2020 post at $240 and since then it has traded sideways and weakened to $205.
Portfolios continued to hold GOOGL (Alphabet) which has risen 23% since August 28, 2021 from $1,639 to $2,021.
At some time during this past week, the following assets (on a weekly timeframe) registered either Overbought, Oversold or traded more than 2.5 standard deviations above its rolling mean.
For the second consecutive week, the only assets in my immediate universe which was either Oversold (where the RSI is < 30) and or trading at least 2.5 standard deviations below its mean are…..
Gold (priced in USD and AUD)
U.S. 2 Year Treasury Bond Yields
Everything else in my list below is in the “Overbought” territory
Extremes “above” the Mean (at least 2.5 standard deviations)
USD/JPY (The Yen is weak relative to the U.S. Dollar)
USD / Korean Won
Australian Government 2 Year Bond Yields
Overbought (RSI > 70)
AUD / JPY
USD / JPY (i.e. Yen is weak)
WTI Oil
Brent Crude Oil
CRB Index (we’ve already seen an impressive 6 month commodity rally)
Heating Oil (again)
Gasoil
Copper
Aluminium
Tin
U.S. KBW Banking Index (again)
Dow Jones Transport Index (again)
Swedish, British, Australian, U.S. and Canadian 10 year bond yields
Corn
Soybeans
Nikkei 225
Russell 2000
S&P MidCap 400
Bitcoin
Ravencoin
Ethereum
The Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)
Korean 10 year bond yields
U.S. 5 year bond yields (i.e. the trade is to Buy the bond)
Stockholm OMX 30 Index
Notes:
The spread between the 2 year and 10 year bond yield continues to widen, now sitting at 1.48%, something not seen since October, 2015.
The uncrowded trade is to be Long Gold while Short 10 year Government Bonds is awfully popular.
Bitcoin is still trading at more than 500% above its 200 Weekly Moving Average.