Pasta consumption still growing

Lately, I’ve been writing about the price of wheat, which prompted a review of a post I wrote in 2012 where I discuss one of my favourite uses of (durum) wheat, being Pasta.


In the original 2012 post I was willing Great Britain to lift its consumption game.

https://robzdravevski.com/2012/09/02/global-pasta-consumption-room-for-growth/


The source of the figures below is from possibly one of the world’s most important organisations, being the International Pasta Organisation. Watch out OPEC…..


They have a clear mission…… THEY ARE NON PROFIT ASSOCIATION DEDICATED TO INCREASE PASTA CONSUMPTION AND AWARENESS…….


Here is a list of the average amount of kilograms of pasta each resident in the following country consumed in 2011


Italy 26.0 kg 

Venezuela 13.0 kg

Tunisia 11.9 kg
Greece 10.4 kg

USA 8.8 kg
Chile 8.4 kg

France 8.0 kg
Germany 7.9 kg
Argentina 7.2 kg

Iran 7.0 kg

Portugal 6.6 kg

Turkey 6.4 kg
Brazil 6.4 kg

Czech Republic  6.0 kg
U.K. 2.5 kg

Then. in 2019, they consumed…..


Italy 23.1 kg 

Tunisia 17 kg

Venezuela 12 kg

Greece 11.4 kg

Chile 9.5 kg

USA 9 kg
Argentina 8.7 kg

Turkey 8.6 kg

Iran 8.7 kg

France 8.1 kg

Germany 7.7 kg

Portugal 6.5 kg

Czech Republic  6.5 kg

Brazil 5.8 kg

U.K. 3.5 kg


Surprisingly, Italian and Brazilian consumption declined through the decade.

Argentine and Turkish consumption increased handsomely, while Tunisians and Brits ate 40% more pasta on a per capital basis.


Incidentally, the largest pasta consumption market is the United States at 2.7 million tons, followed by Italy at 1.4 million tons and then Brazil is third at 1.2 million tons.

Overall, total global pasta production has grown from 12.5 million tons in 2011 to 16 million in 2019.

I wonder if many Italians emigrated to Argentina over that time to account for the decline in Italy and an increase in Argentina ??

January 7, 2021

by Rob Zdravevski

rob@karriasset.com.au
Bitcoin on support but converging to WMA

Bitcoin needs to hold $42,333 for now.
It’ll be telling for other risk assets,
Bitcoin could see the $26,000 – $23,000 level
More on other support levels #bitcoin later,
but isn’t trading at 500% above its 200 weekly moving average anymore, instead it’s now 126%.

Below is a weekly chart, the 200 week moving average has risen from $15,000 to $20,000 over the past 4 months, which is in keeping with my price and moving average convergence post dated, October 18, 2021.

January 6, 2021

by Rob Zdravevski

rob@karriasset.com.au
Cheaper Wheat is good for Kellogg’s

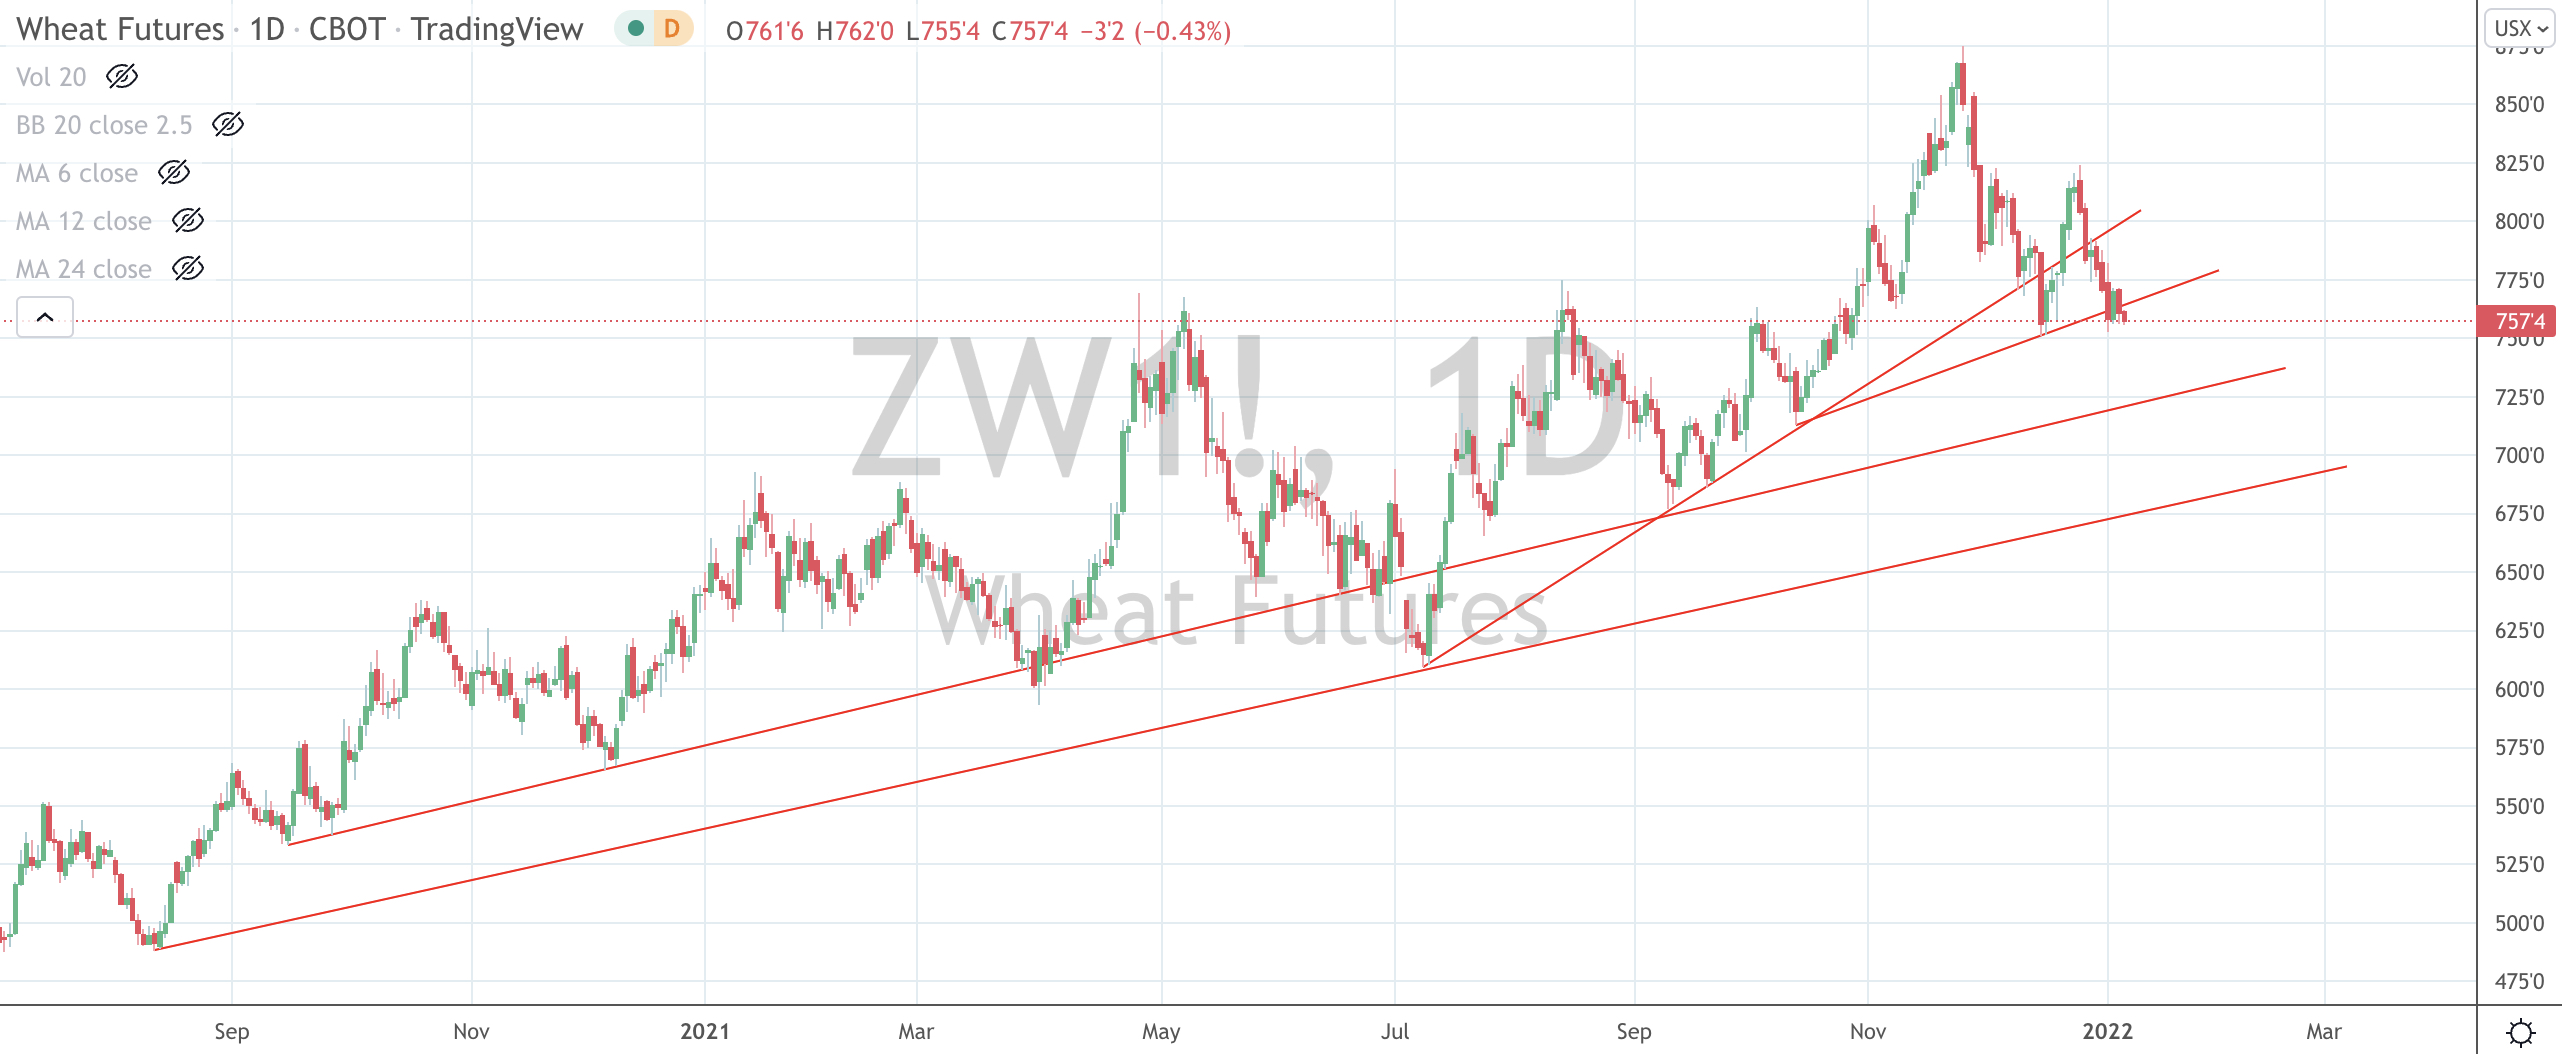
On November 25, 2021, when Wheat was trading at $8.50, I suggested Selling.

Soon after, it traded down to the range mentioned in that post.

Now it’s $7.54.

Should it trade below $7.51, then I think it’s on its way to its next level lower, towards the $7.21 region.

If the medium term downtrend strengthens, I’ll look for the price of Wheat to visit to $6.78.

That would represent a 78.6% retracement of the advance which commenced in early September and it coincides with a 61.8% pullback of the larger rally which began in July 2021.

The notes (see links) below were written in July 2021, predicting the bounce in Wheat.

and written slightly before this,

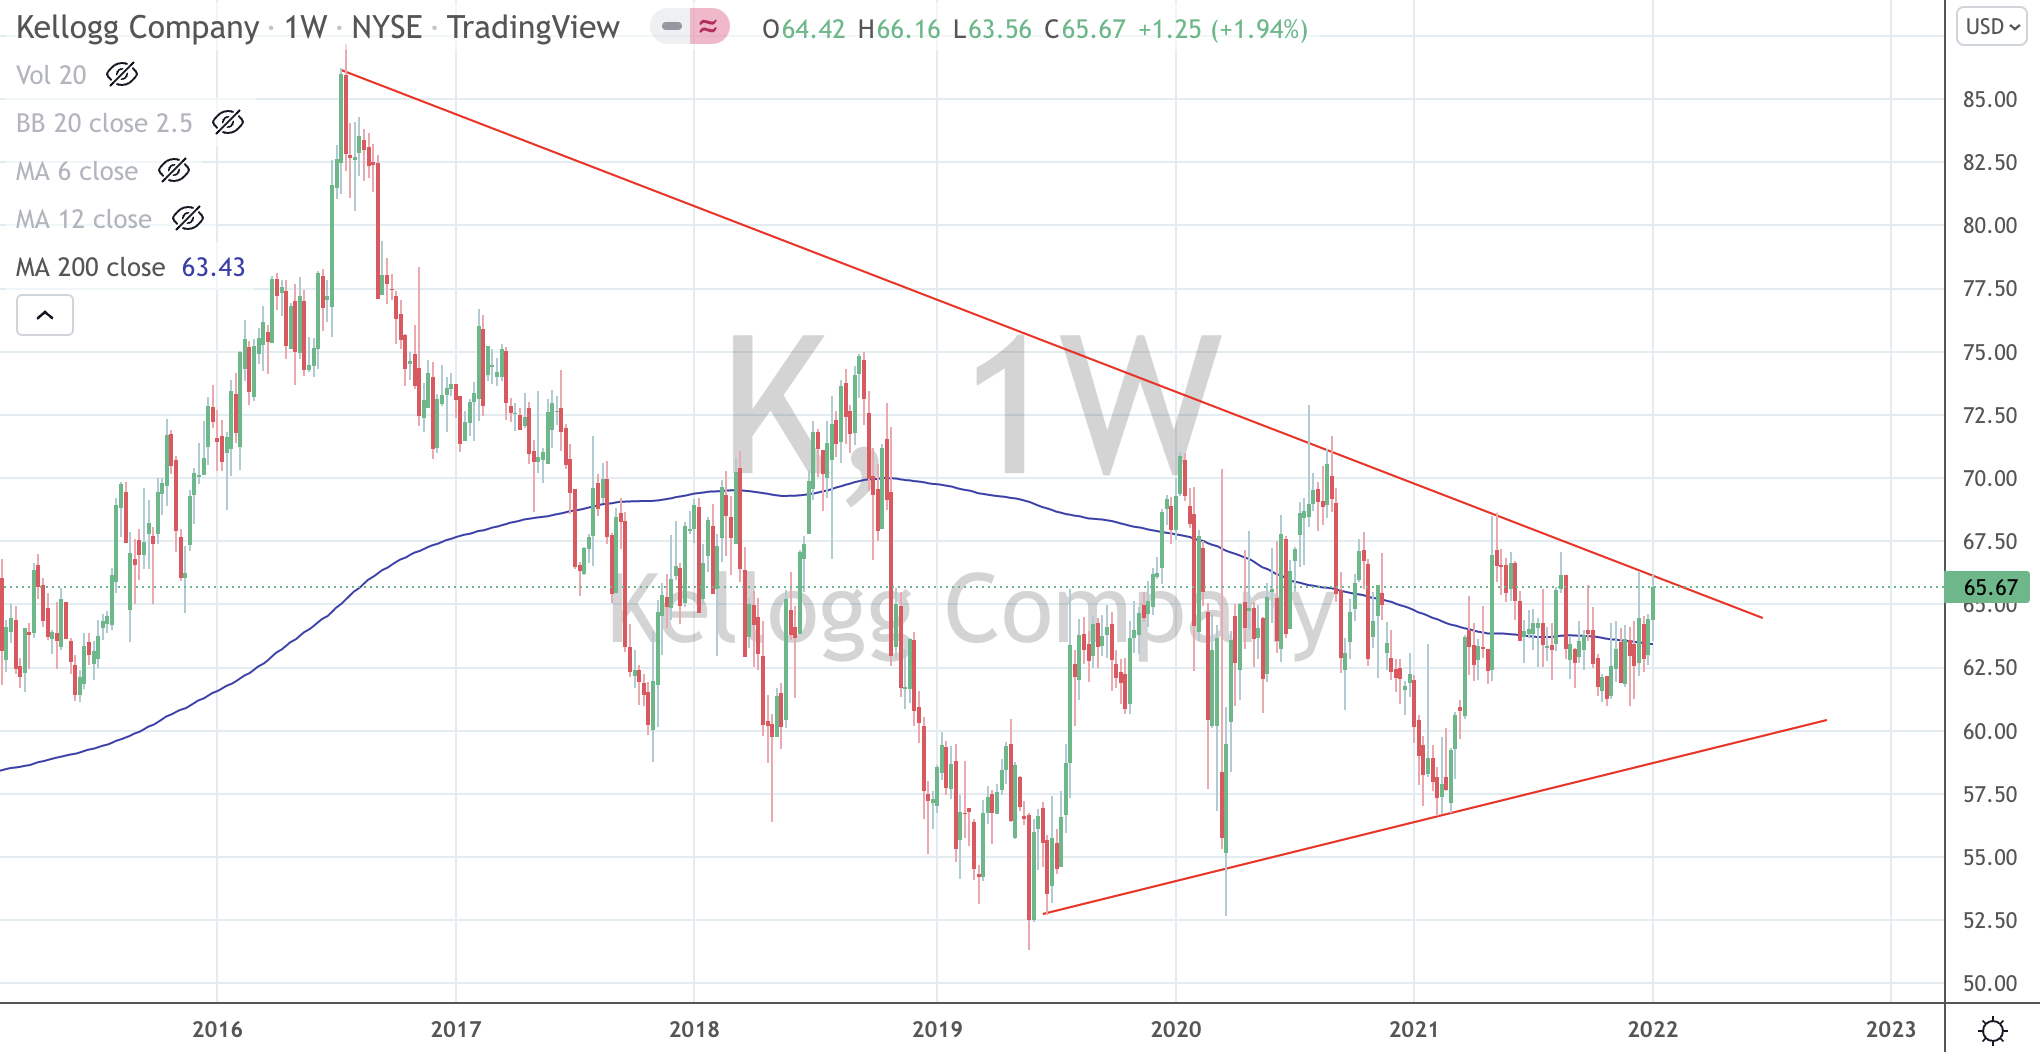
And the winner is and will be…..Kellogg’s share price.

‘As a grain-based food company, the success of Kellogg Company is dependent on having timely access to high quality, low cost ingredients,….’ – source: Kellogg Company 2020 annual report.

December 6, 2021

by Rob Zdravevski

rob@karriasset.com.au
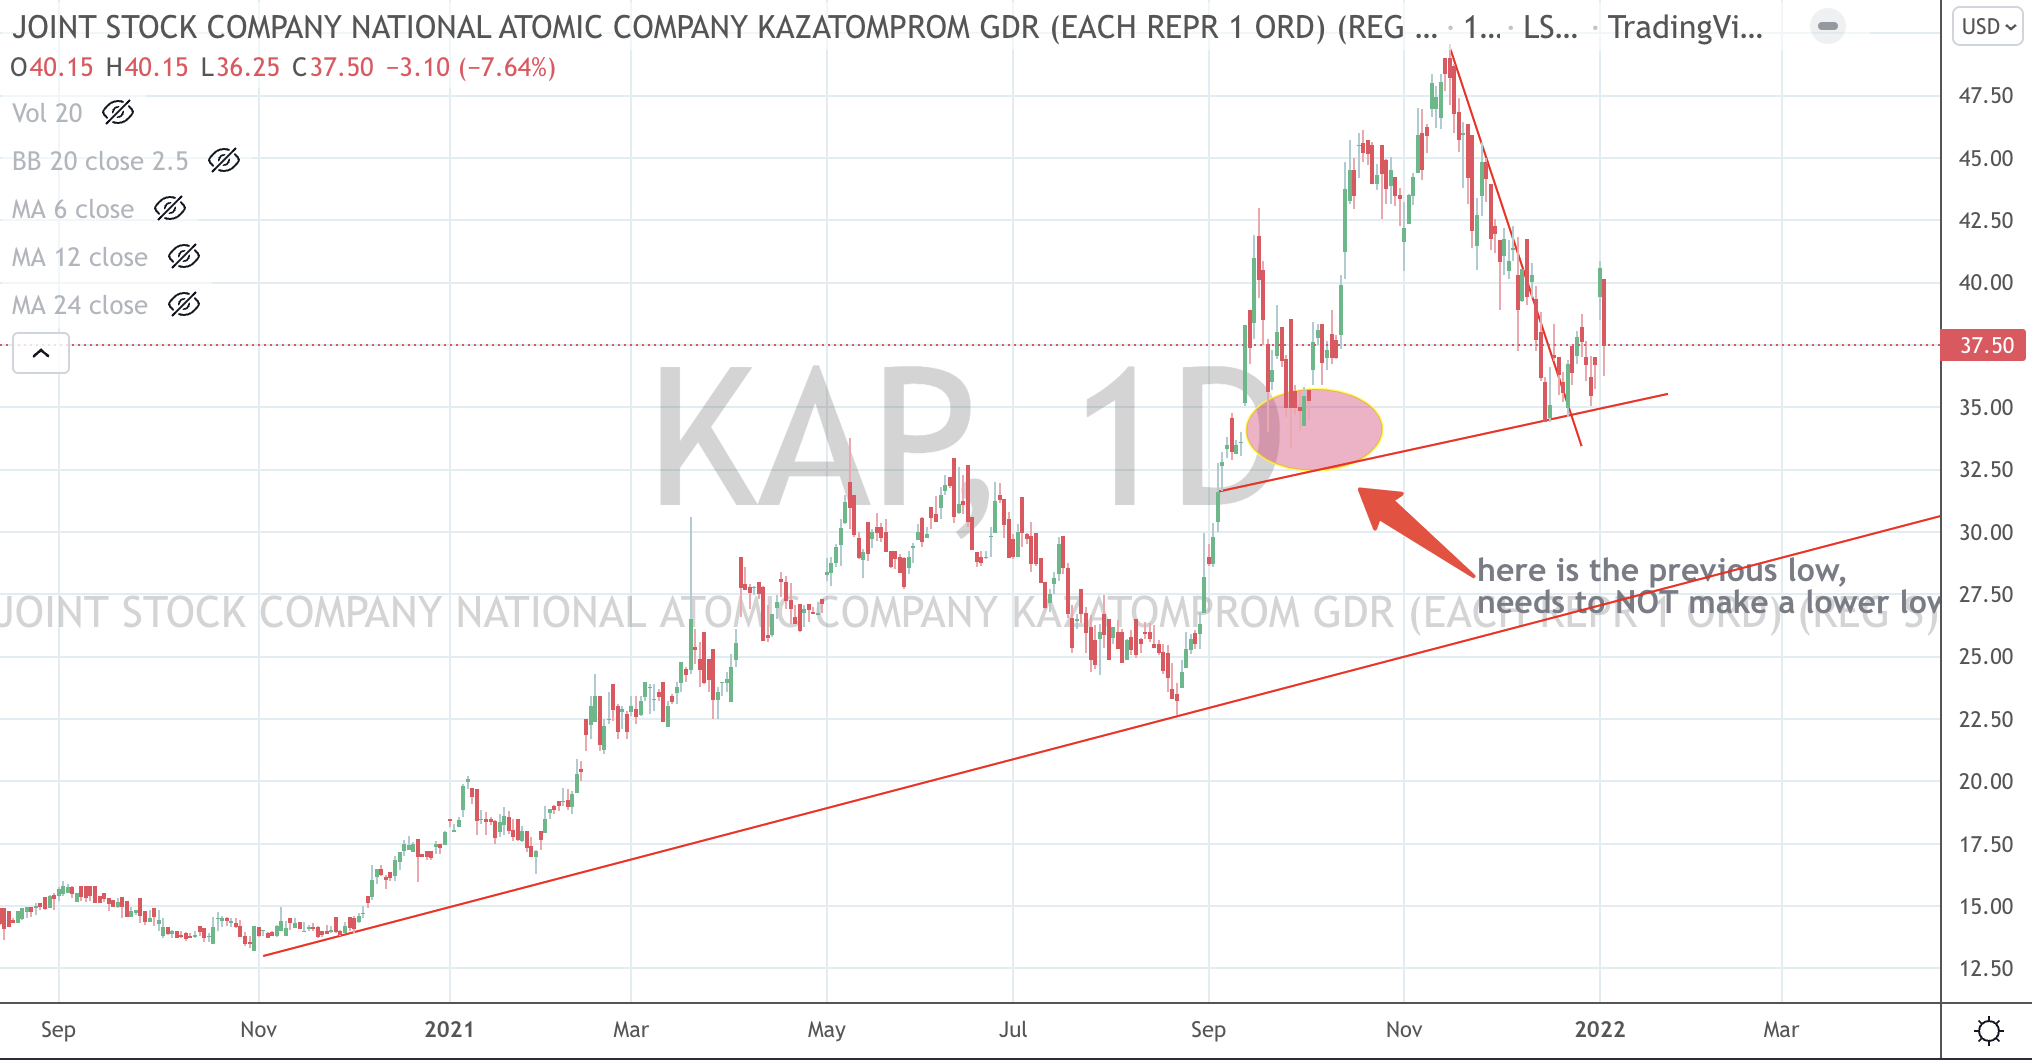
Kazakh Unrest and Uranium Prices

Unrest in Kazakhstan has seen shares in Kazataprom fall 8% overnight. The Uranium (front contract) price spiked 9%. Equity prices of uranium producers/explorers also jumped before settling below their intraday highs.

“Kazatomprom is the world’s largest producer and seller of natural uranium, providing over 40% of global primary uranium supply.”

As per chart below, I’m watching it makes a new ‘lower low’ below the recent low of US$33.35.

If so, Kazatomprom will be a better buy around the US$28 mark.

December 6, 2021

by Rob Zdravevski

rob@karriasset.com.au

Conditioning For Lower Returns

Most of the investing world measures annual performance at the end of December 31st.

The media and pundits make themselves seem clever by reporting what has already happened.

You must remember that they are reporters and not market professionals or investors.

What is the difference?  

Journalists and commentators seldom (if at all) take any risk with their own or while advising and managing other people’s money.

While it’s informative, it’s not visionary and it doesn’t help anyone’s past nor prepare anyone for the future.

What is more important that simply reporting the past 3 years of performance figures….

S&P 500

2019 29%

2020 16%

2021 27%

Nasdaq 100

2019 36%

2020 50%

2021 27% 

…..is to ponder what to expect in the coming year or so.

While that prediction is impossible, the best guidance I can offer readers is that these type of returns are not to be taken for granted and certainly not to be extrapolated or ‘banked on’ in the future.

It’s more plausible to expect 2022 numbers to come in at +7% or (5%).

Consider conditioning oneself for lower returns.

Why?

Unscientifically;

Winning streaks come to an end,

Many think it’s their god-given right to earn 20% every 2 months, 

Those type of returns are extraordinary when compared to the cash rate,

Persistent extraordinary performance are eventually subdued,

Elastic Bands and Pendulum snap back and 

When I posed an investment idea which I thought may provide a 15% return over the next 18 months, the investor responded with “it’s hardly worth making that investment for such an average result”.

Mathematically, we may argue whether earnings expand, investors pay even higher prices for those future earnings or what has been or isn’t already factored or discounted.

Meanwhile the ASX 200 Index performance has been;

2019 19%

2020 (2%)

2021 13%

January 3, 2022

by Rob Zdravevski

rob@rkarriasset.com.au

Macro Extremes (week ending December 31, 2021)

The following assets (on a weekly timeframe) registered an Overbought reading or traded more than 2.5 standard deviations above its rolling mean.

Extremes “above” the Mean (at least 2.5 standard deviations)

Italian 10 year government bond yields

Soybeans

Rice

Overbought (RSI > 70)

U.S. 2 year bond yields

Cattle

USD/JPY

The Overbought Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)

None

Assets (securities) which touched the other side of the extreme, being Oversold (where the RSI is < 30) or were at least 2.5 standard deviations below its mean are;

Extremes “below” the Mean (at least 2.5 standard deviations)

EUR/GBP


Oversold (RSI < 30)

None

The Oversold Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean.

Hot Rolled Coil Steel (HRC)


Notes & Ideas:

Notable news in market action included Urea and the JKM LNG Marker are no longer Overbought.

It was the mildest of weeks not only considering the movements over the past 12 weeks but also the lighter than usual volume which can exacerbate price volatility.

I’m encouraging readers to review past few editions of ‘Macro Extremes’ contains some basics of the framework which I am watching and they are still intact, from Gold, Silver, Currencies and Bonds.

The biggest weekly mover in global markets was the declines in Coal and Gas related commodity prices. JKM LNG fell 22%, Rotterdam Coal declined 16%, Dutch TTF Gas was walloped 47%, while Hot Rolled Coil (HRC) Steel gave up 11%.

All of these assets are falling following parabolic ascents, which remains something to watch, although HRC Steel is the first commodity to have reached an Oversold level for many months, after ‘only’ declining 26% from its August all-time high.

Interestingly, Dutch TTF Gas has fallen 61% from its parabolic peak and not close to touching an extreme low.

The price of Rice has touched its highest level in 20 months. The previous time it saw this level was mid-2014.

It’s worth pondering the effect of these higher prices for producing and exporting nations along with those countries where Rice is a notable staple.

China and India produce 29% and 23% of the globe’s annual crop, while the latter is the largest exporter.

In other milestones, the Japanese Yen has closed at its weakest price (versus the U.S. Dollar) since March 13, 2017.

More on these topics and their relationship to other assets in separate posts.

And Crude Oil, Gasoil (diesel), U.S. Transports and the S&P 500 all gained, adding to and confirming last week’s bullish outside reversal weeks.

The larger advancers over the past week comprised of; 

Australian Coal 3.1%, Cocoa 1.9%, WTI Crude 1.9%, Gasoil 2.1%, Lumber 9.4%, Cattle 1.9%, Silver 1.8%, Brent Crude 2.7%, Rice 4.5%, Dow Jones Transports 1.8%, IBEX 1.8%, S&P 400 Midcap 1.7%, MOEX 2.3%, Sensex 2.1% and Copenhagen 25 index rose 1.8%.

The group of decliners included ;

Aluminium (2%), Rotterdam Coal (15.5%), China Coal (7.3%), Lean Hogs (2.1%), HRC (11.2%), JKM (21.5%), Coffee (2.2%), LNG Nymex (33.8%), Sugar (1.9%), Dutch TTF Gas (47%), Urea (9.8%), Corn (2.1%), Wheat (5.4%), Oats (3.4%).

Lastly, and editorial comment.

Bitcoin and Ethereum both declined 8% for the week, while they seem to synchronise their weekly movements lately, it seems difficult to consolidate the concept that they can be considered a ‘currency’….but then again, the Turkish Lira did fall 18% for the week and many still call it a currency.


January 2, 2022

by Rob Zdravevski

rob@karriasset.com.au   

Wow ! Accenture Wow !

Back then, when I was a broker at Salomon Smith Barney, the firm was part of the new IPO in Accenture.

This was the new name for Andersen Consulting after the partners voted to become independant from Arthur Andersen

My job was to be the broker contact for the Australian partners and anything involving their Stock, Options and ESOP. The main focus was the “Founders Shares” which were priced at 1 cent.  

The IPO was priced at $14.50 per share on July 18, 2001


Back then Accenture’s numbers looked like this;

Revenues $10 billion

Net Profit: $2.4 billion

Number of employees: 75,000

Market Cap: $14 billion

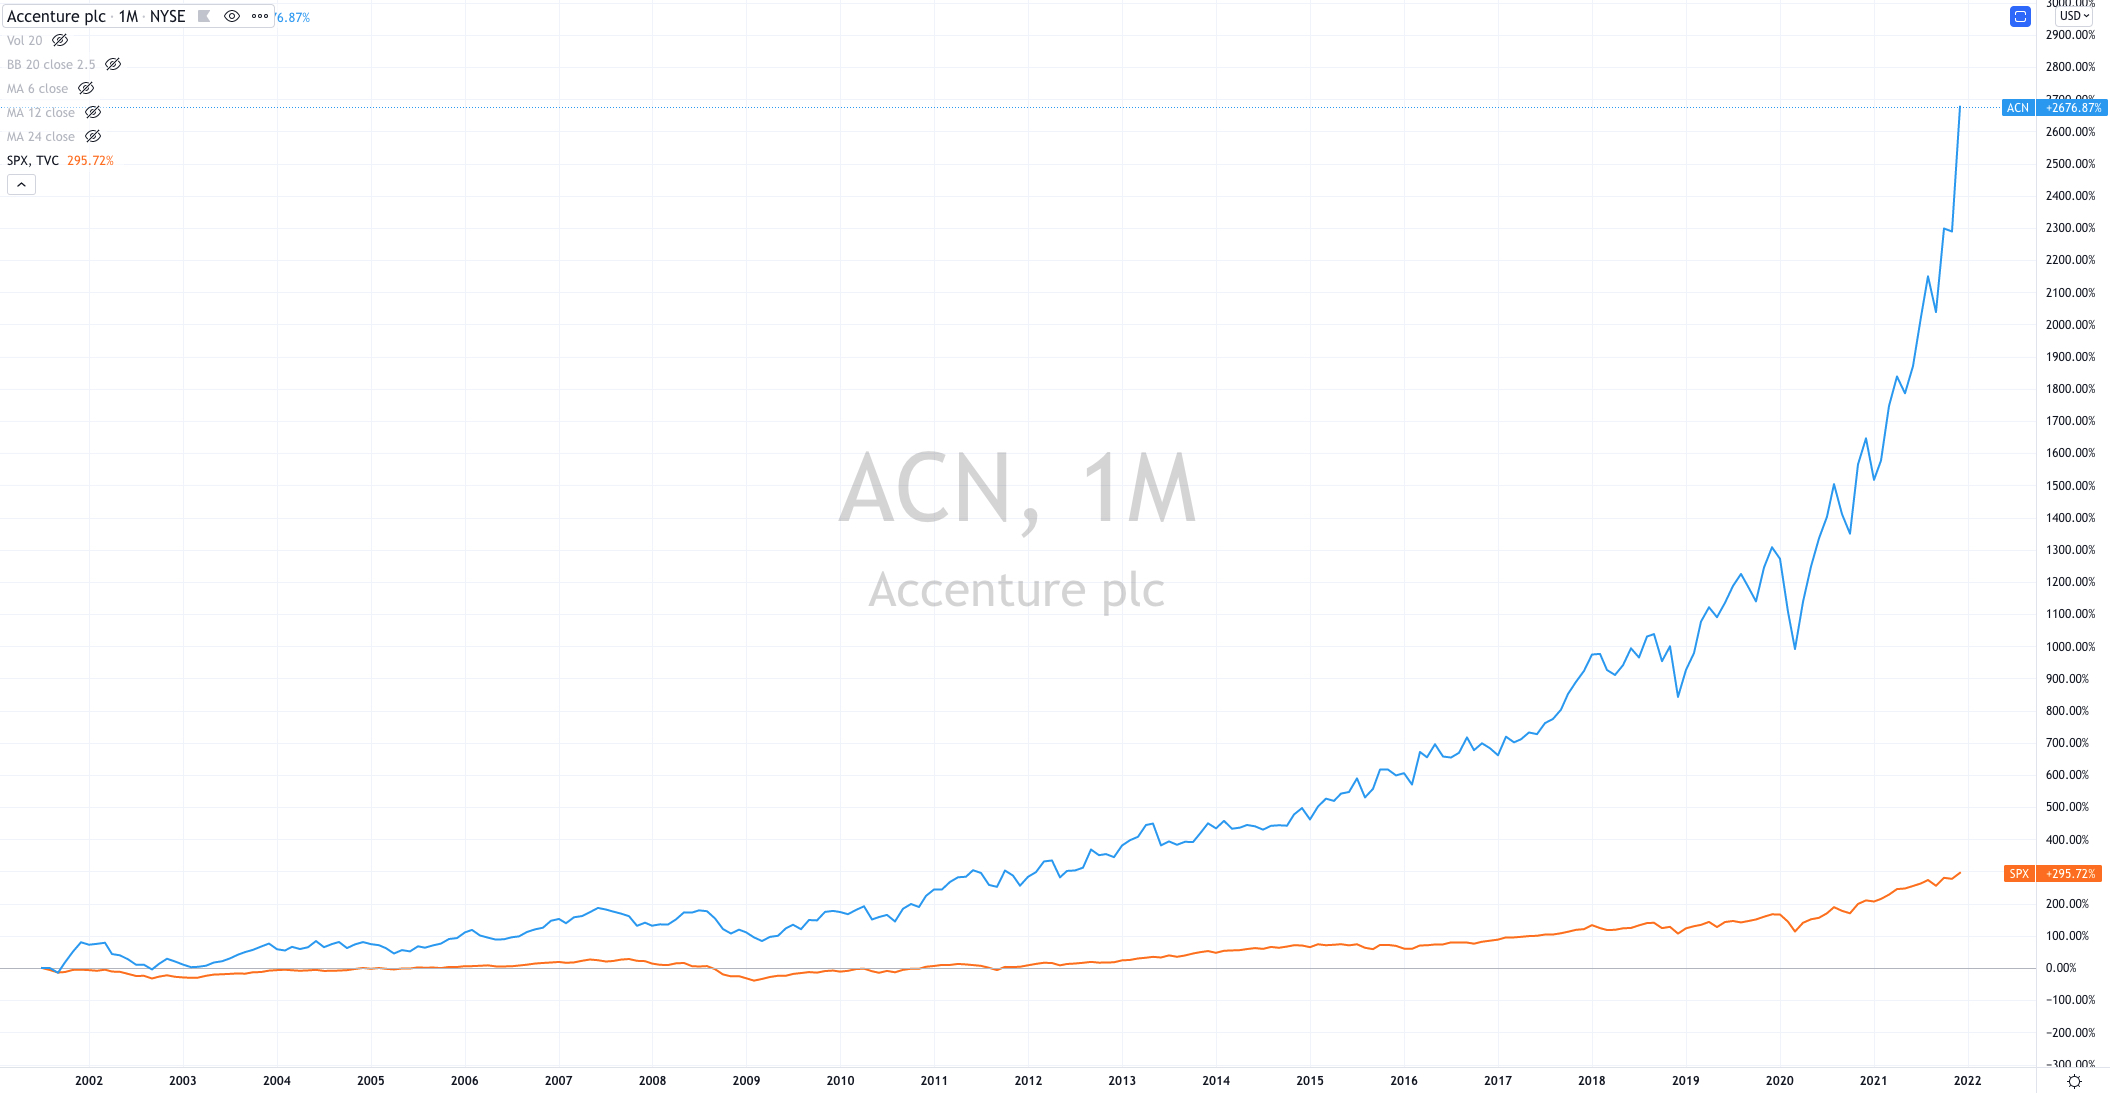
The chart below shows Accenture stock price is now trading at $415.

I remember the IPO day well and 20 years on, some of those Australian partners are still clients or remain within my network.

While some have sold all their holdings, I’m sure many have divested along the way and perhaps there are those who haven’t sold a single share.

Today’s Accenture numbers are;

Revenues $51 billion

Net Profit $6 billion

Number of employees: 674,000

Market Cap: $272 billion

It’s simply amazing to watch the stock price of this company rise 20 fold over the past 20 years and furthermore, outperform the S&P 500 by a factor of 10, as seen in the 2nd chart presented below.

Incidentally, Accenture’s stock has tripled over the past 20 months and its price rise now resembles a parabola along with a few indicators spitting out Overbought signals.

I guess the biggest problem selling now is finally triggering a taxable event.

Finally, it’s nice to see a stock appreciate and adding most of its value in its guise as a public company.

More on this later.

December 31, 2021

by Rob Zdravevski

rob@karriasset.com.au

My final newsletter for 2021

My final newsletter for 2021 is here……

https://mailchi.mp/karriasset/a-distorted-sp-500-amongst-extreme-peaks

Lower Shipping Costs

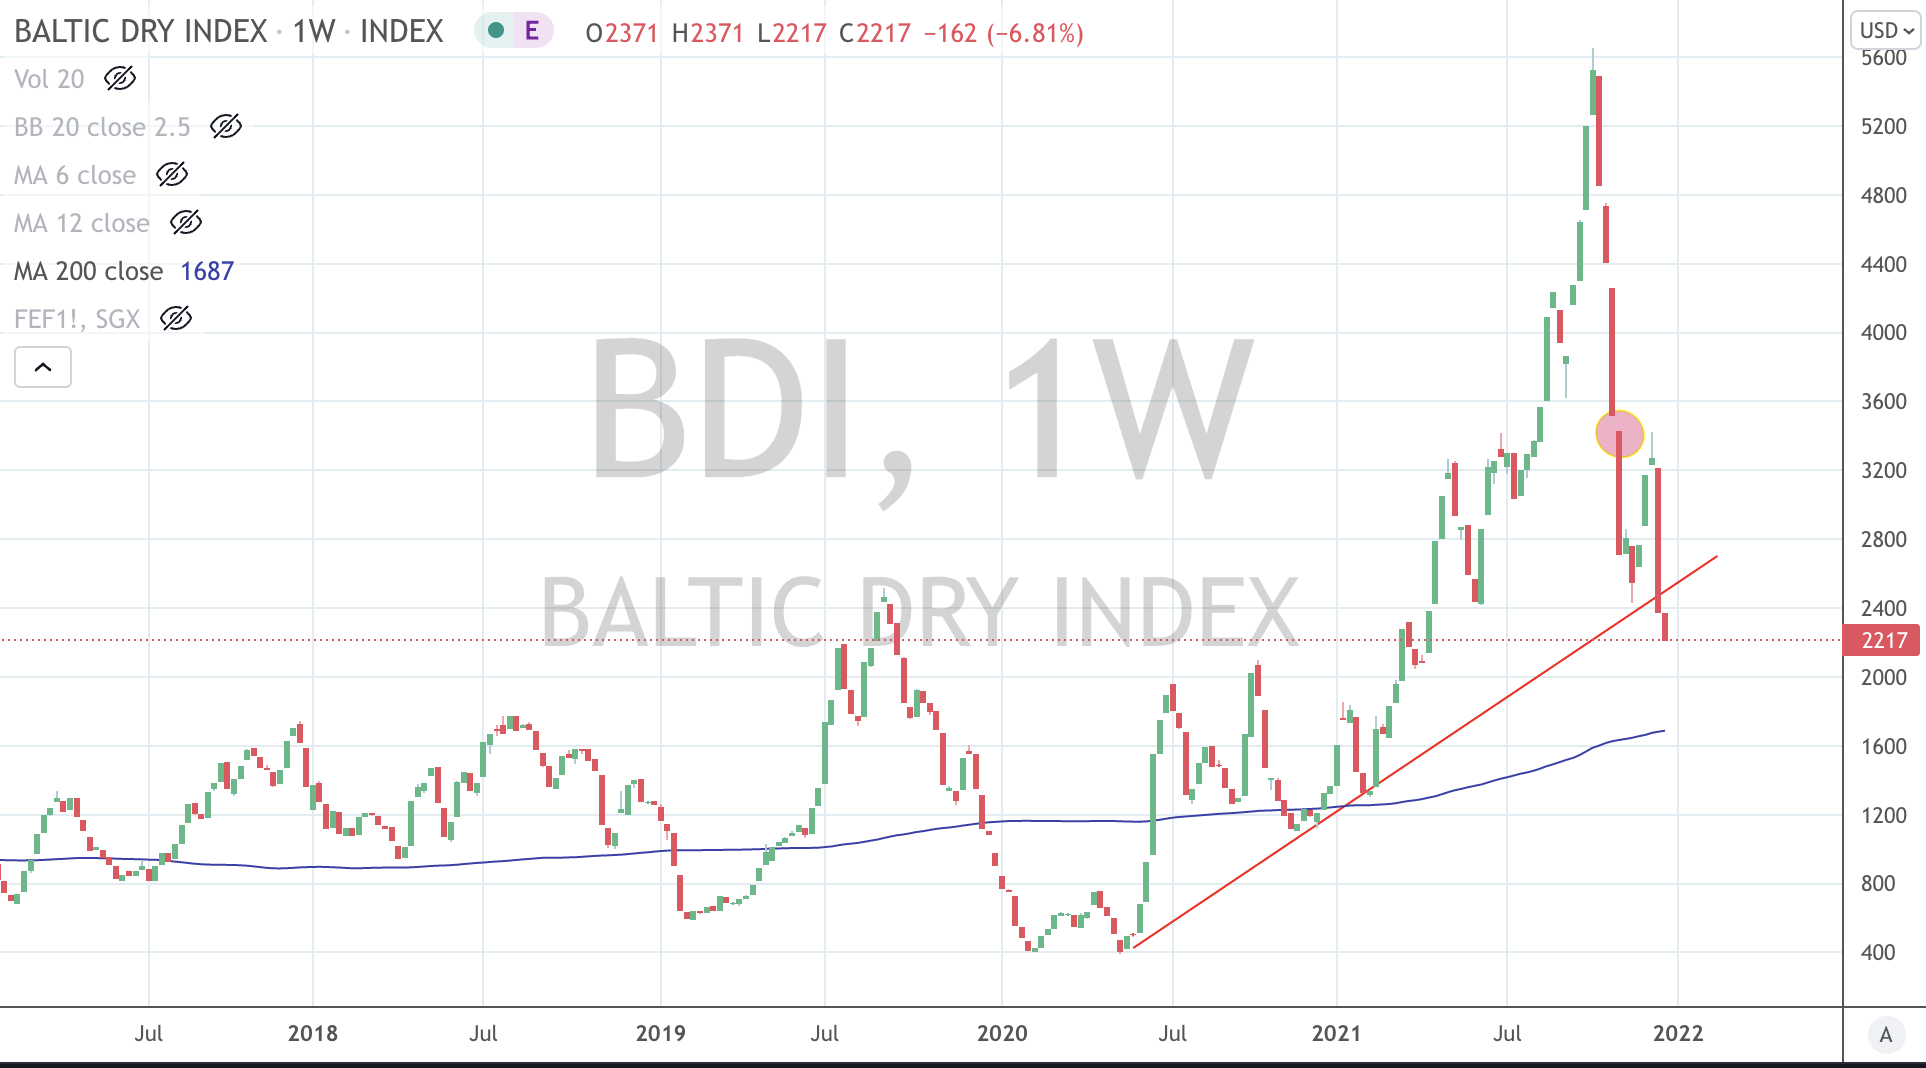
Below is a chart of the Baltic Dry Index, which has risen 12 fold in 18 months.

Such a parabolic rise is often met with a severe retracement.

Recently, it couldn’t trade above a recent mark (as noted in the ellipse) to make a ‘higher high’ but last week, it broke beneath a trend line and made a ‘lower low’.

Other indicators are also bearish.

I’ll look for it to mean revert to its 200 week moving average (blue line) but I think $900 is plausible. Look out below.

Then the next chart I have overlaid the nice correlated Iron Ore price.

The case for a lower Baltic Dry Index increases the probability of lower Iron Ore prices.

We are seeing may assets and securities in a battle to make a ‘higher high’ and if they can’t, we’ll see them making a double dip to recent lows.

Where parabolas have existed, expected lows to be tested but also broken. Reversion to the mean will be a more notable thing to look for.

With that, I think about mining companies exposed to this theme. 

I believe that lower shipping prices will more than offset a new 20% decline in Iron Ore prices.

December 27, 2021

By Rob Zdravevski

rob@karriasset.com.au.

#mining #shipping #RIO #FMG #BHP #ironore

Macro Extremes (week ending December 24, 2021)

The following assets (on a weekly timeframe) registered an Overbought reading or traded more than 2.5 standard deviations above its rolling mean.

Extremes “above” the Mean (at least 2.5 standard deviations)

None

Overbought (RSI > 70)

U.S. 2 year bond yields

Turkish 10 year bond yields

the JKM “Japan/Korea (LNG) Marker”

Urea 

The Overbought Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)

Dutch TTF Natural Gas (it fell 23% of Friday alone)

Assets (securities) which touched the other side of the extreme, being Oversold (where the RSI is < 30) or were at least 2.5 standard deviations below its mean are;

Extremes “below” the Mean (at least 2.5 standard deviations)

Russia’s MOEX equity index

Spain’s IBEX equity index

HSCEI Index

Hang Seng Index

Sugar


Oversold (RSI < 30)

None

The Oversold Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean.

None


Notes & Ideas:

It was a mild week considering the movements over the past 12 weeks.

There isn’t much to report. 

The past few editions of ‘Macro Extremes’ contains some basics of the framework which I am watching and they are still intact, from Gold, Silver, Currencies and Bonds.

The U.S. 10 year bond yield is still in a downtrend while it holds the 1.34% support line.

From previous week’s commentary, I’ll reiterate watching the difference between the U.S. 10 year bond yield minus the U.S. 2 year bond yield.

The biggest weekly mover in global markets was the Turkish Lira rising 52% following continual weeks of making new historic lows.

Look out for a note on the Baltic Dry Index, which fell a further 7% this week, adding to last week’s 27% decline and it’s part of a story which I am telling is an example of 2nd chance selling pressure which will eventuate in a double dip in many assets.

Another notable mover was (NYMEX traded) U.S. LNG prices, which rose 19% as a flotilla of cargoes are heading to Europe chasing higher spot prices on the continent. 

I’ll continue to highlight the peril of chasing parabolic moves such as the one seen in Dutch TTF Gas price, which after more than doubling in 6 weeks, fell 23% on Friday alone.

While Crude Oil, Gasoil (diesel), U.S. Transports and the S&P 500 all made outside bullish reversal weeks.

The larger advancers over the past week comprised of; 

Oslo +2.3%, Stockholm +3.5%, Philadelphia SOX +4.6%, S&P 500 +2.3%, Transports +3.5%, AUDJPY +2%, AEX +2.4%, CAC +2.3%, DJ Transports +2.3%, IBEX +3%, S&P Midcap 400 +2.6%, Nasdaq 100 +3.2%, Russell 2000 +3.1%, Aluminium +5.8%, Bloomberg Commodity Index +2.6%, WTI Crude +4.3%, Iron Ore +2.2%, Gasoil +1.8%, Lean Hogs +3%, Copper +2.3%, Heating Oil +5%, Cattle 1.8%, LNG +19.5%, Platinum +4.3%, Gasoline +4%, Silver +1.8%, CRB Index +2.6%, Brent Crude +4%, Corn +2.1%, Rice +1.8%, Soybeans +4.1% and Wheat +5.1%.

The group of decliners included ;

Baltic Dry Index (6.8%), Hot Rolled Coil Steel HRC (2%0, JKM (8.5%), Lumber (2.5%), Dutch TTF Gas (3.2%), Rotterdam Coal (2.7%), Bovespa (2.2%) and Istanbul’s BIST (9.5%)


December 27, 2021

by Rob Zdravevski

rob@karriasset.com.au