A weekly Macro, Cross Asset review of prices trading at extremes which may generate future investment ideas and opportunities.
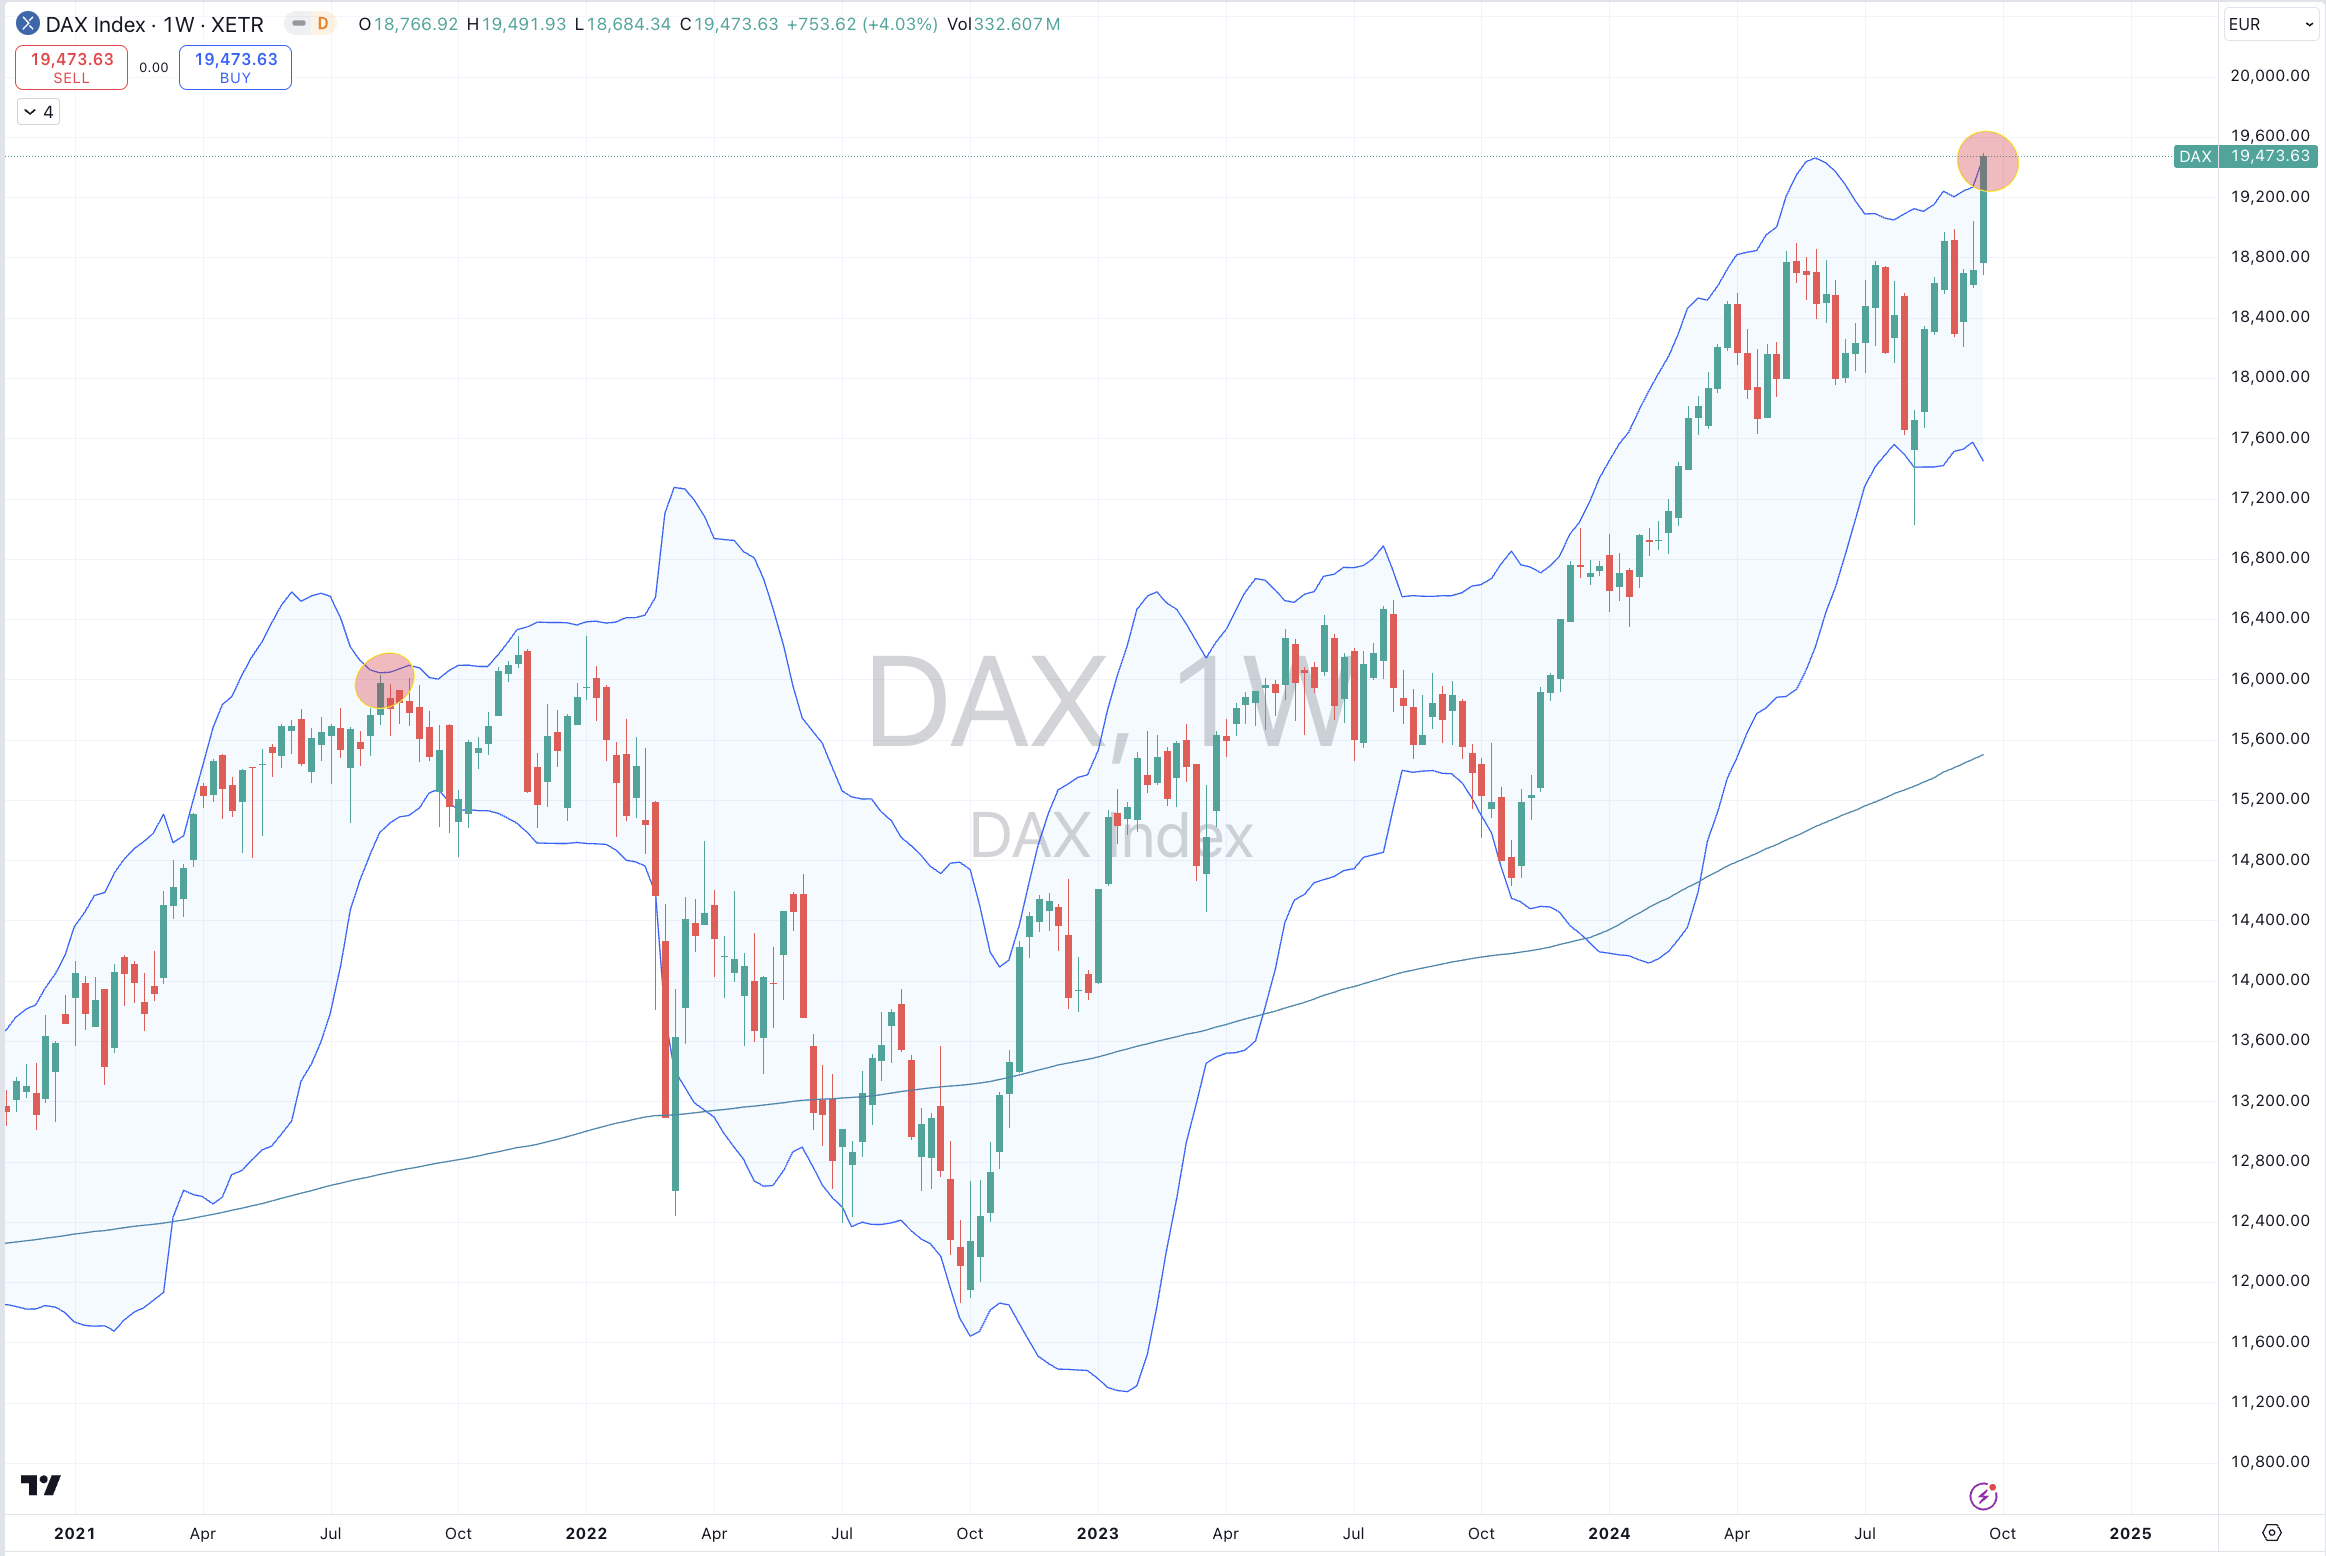
The following assets (on a weekly timeframe) either registered an Overbought or Oversold reading and/or have traded more than 2.5 standard deviations above or below its rolling mean.
* denotes multiple week inclusion
Extremes above the Mean (at least 2.5 standard deviations)
Palladium
Sugar
AUD/CAD
ZAR/USD
IBEX
Copenhagen
PSE
Nasdaq Transportation Index
Thailand’s SET Index *
And Australia’s ASX 200
Overbought (RSI > 70)
U.S. 10 year minus U.S. 2 year government yield
U.S. 10 year minus U.S. 5 year government yield
Arabica and Robusta Coffee *
Gold as priced in AUD, CAD, EUR & USD *
MYR/USD *
NIFTY *
SENSEX *
And the ASX Financials Index *
The Overbought Quinella (Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)
Singapore’s Strait Times Index
Extremes below the Mean (at least 2.5 standard deviations)
None
Oversold (RSI < 30)
U.S. 2 year government bond yield *
Australian Coking Coal *
U.S. Midwest Hot Rolled Coil Steel *
North European Hot Rolled Coil Steel *
Lithium Carbonate *
Lithium Hydroxide *
CFR China Iron Ore *
USD/CNH
USD/IDR
USD/SGD *
Shanghai Composite *
The Oversold Quinella (Both Oversold and Traded at < 2.5 standard deviations below the weekly mean)
U.S. 3 month bill yield
Notes & Ideas:
During a week when the investors were awaiting a lowering of the American central bank interest rates…….. Global government bond yields rose.
Chilean and Swiss 10’s yields aren’t oversold anymore.
Short dated Japanese yields bucked the global weekly trend. They fell.
The U.S. yield curve remains overbought (10 year – 2 year) as is the U.S. 10Y – 5Y spread.
The U.S. 5 year minus 5 year breakeven inflation rate is nearing an oversold extreme.
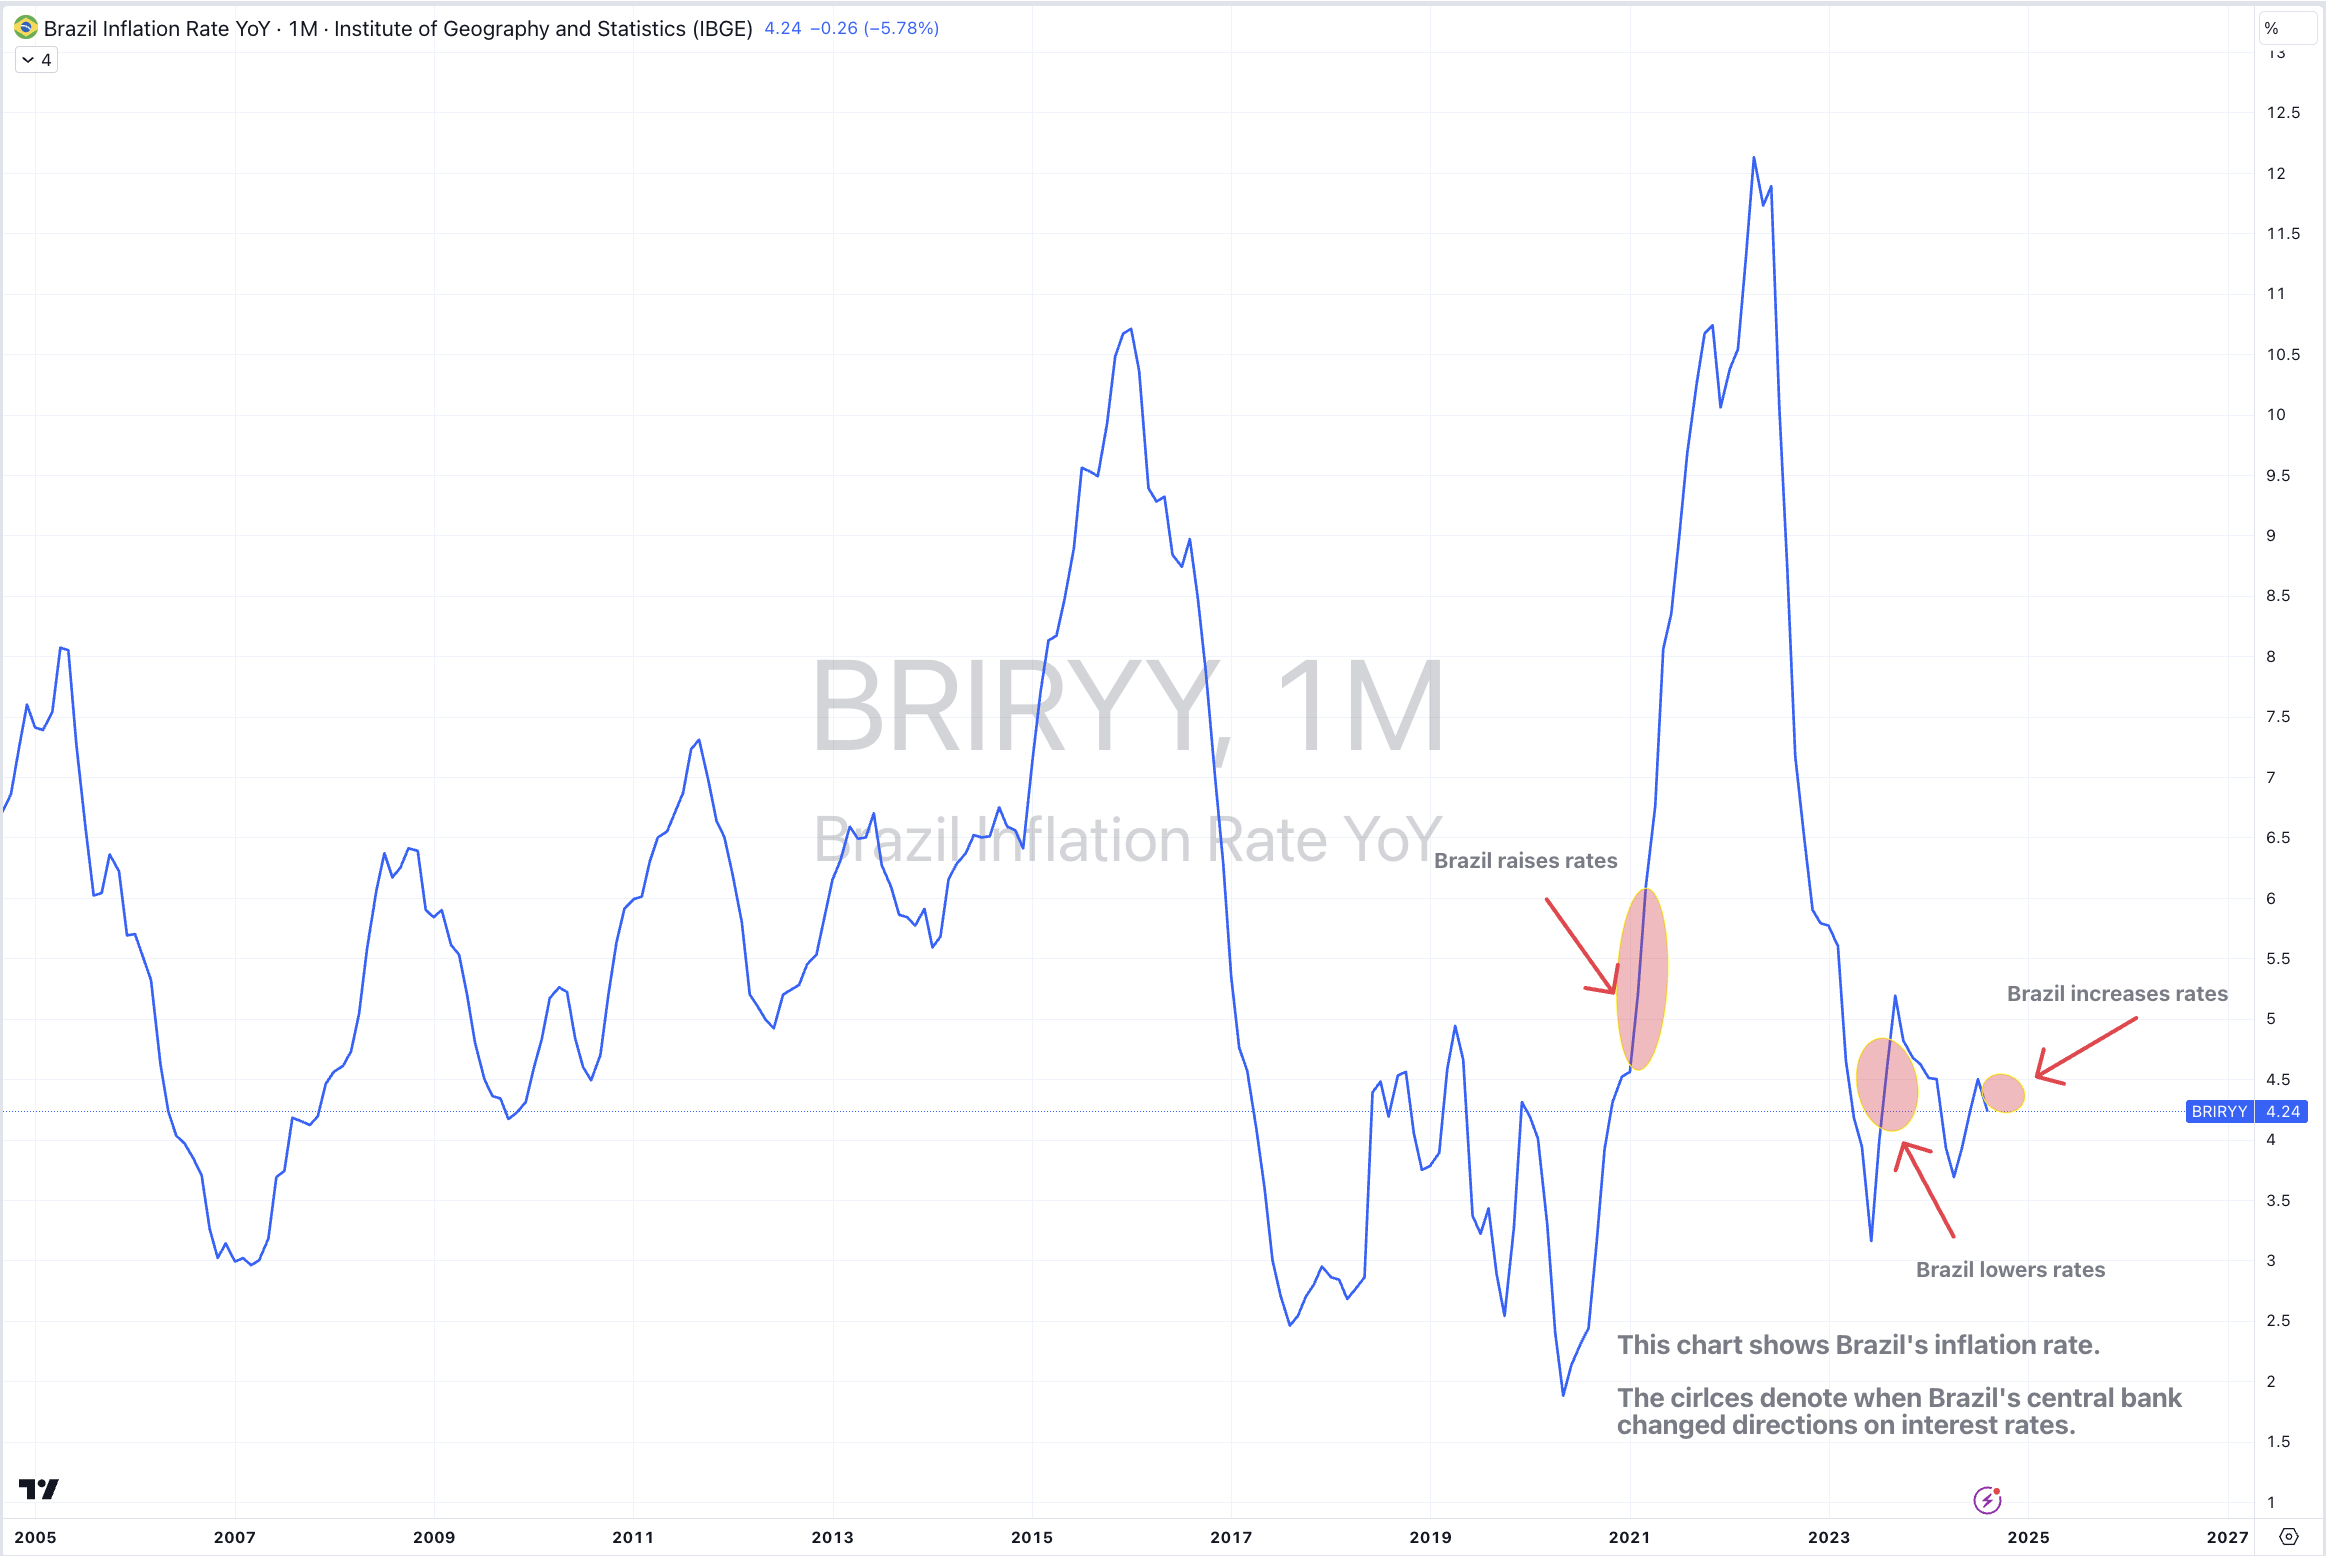
And incidentally, Brazil’s central bank hiked their policy interest rate.
Equities rose again.
We are seeing more indices entering overbought territory.
At this stage, most of them are in Asia driven by their stronger currencies.
Singapore’s Strait Times is in a 6 week winning streak.
Some Australian indices also feature in this week’s list.
The Shanghai Composite and CSI 300 broke their 4 week losing streaks.
And any of those which were oversold last week have bounced, such as the KOSPI.
Commodities mostly rose.
Gold and Palladium remain in overbought territory.
Sugar soared 19% for the week.
Lumber and Heating Oil moved out of overbought territory.
U.S. Henry Hub Natural Gas has risen 14% over the past 3 weeks.
Wheat broke its 3 week winning streak.
U.S.Midwest Hot Rolled Coil Steel has spent 17 weeks being oversold.
And Lithium Hydroxide has now spent 62 consecutive weeks in weekly oversold territory.
Currencies feature heavily in this week’s entrants of extremes.
The Aussie rose while the Canadian Loonie fell, again. Confusing perhaps?
The decline in the CAD juxtaposed the risk-on feeling for the week.
While the Yen’s decline of 2%-3% across a range of pairs and weakness in the Swissie confirmed the ‘risk-on’ mood.
The USD was generally weaker and is prominently oversold against various Asian currencies.
And the British Pound is nearing an overbought level again the USD.
The larger advancers over the past week comprised of;
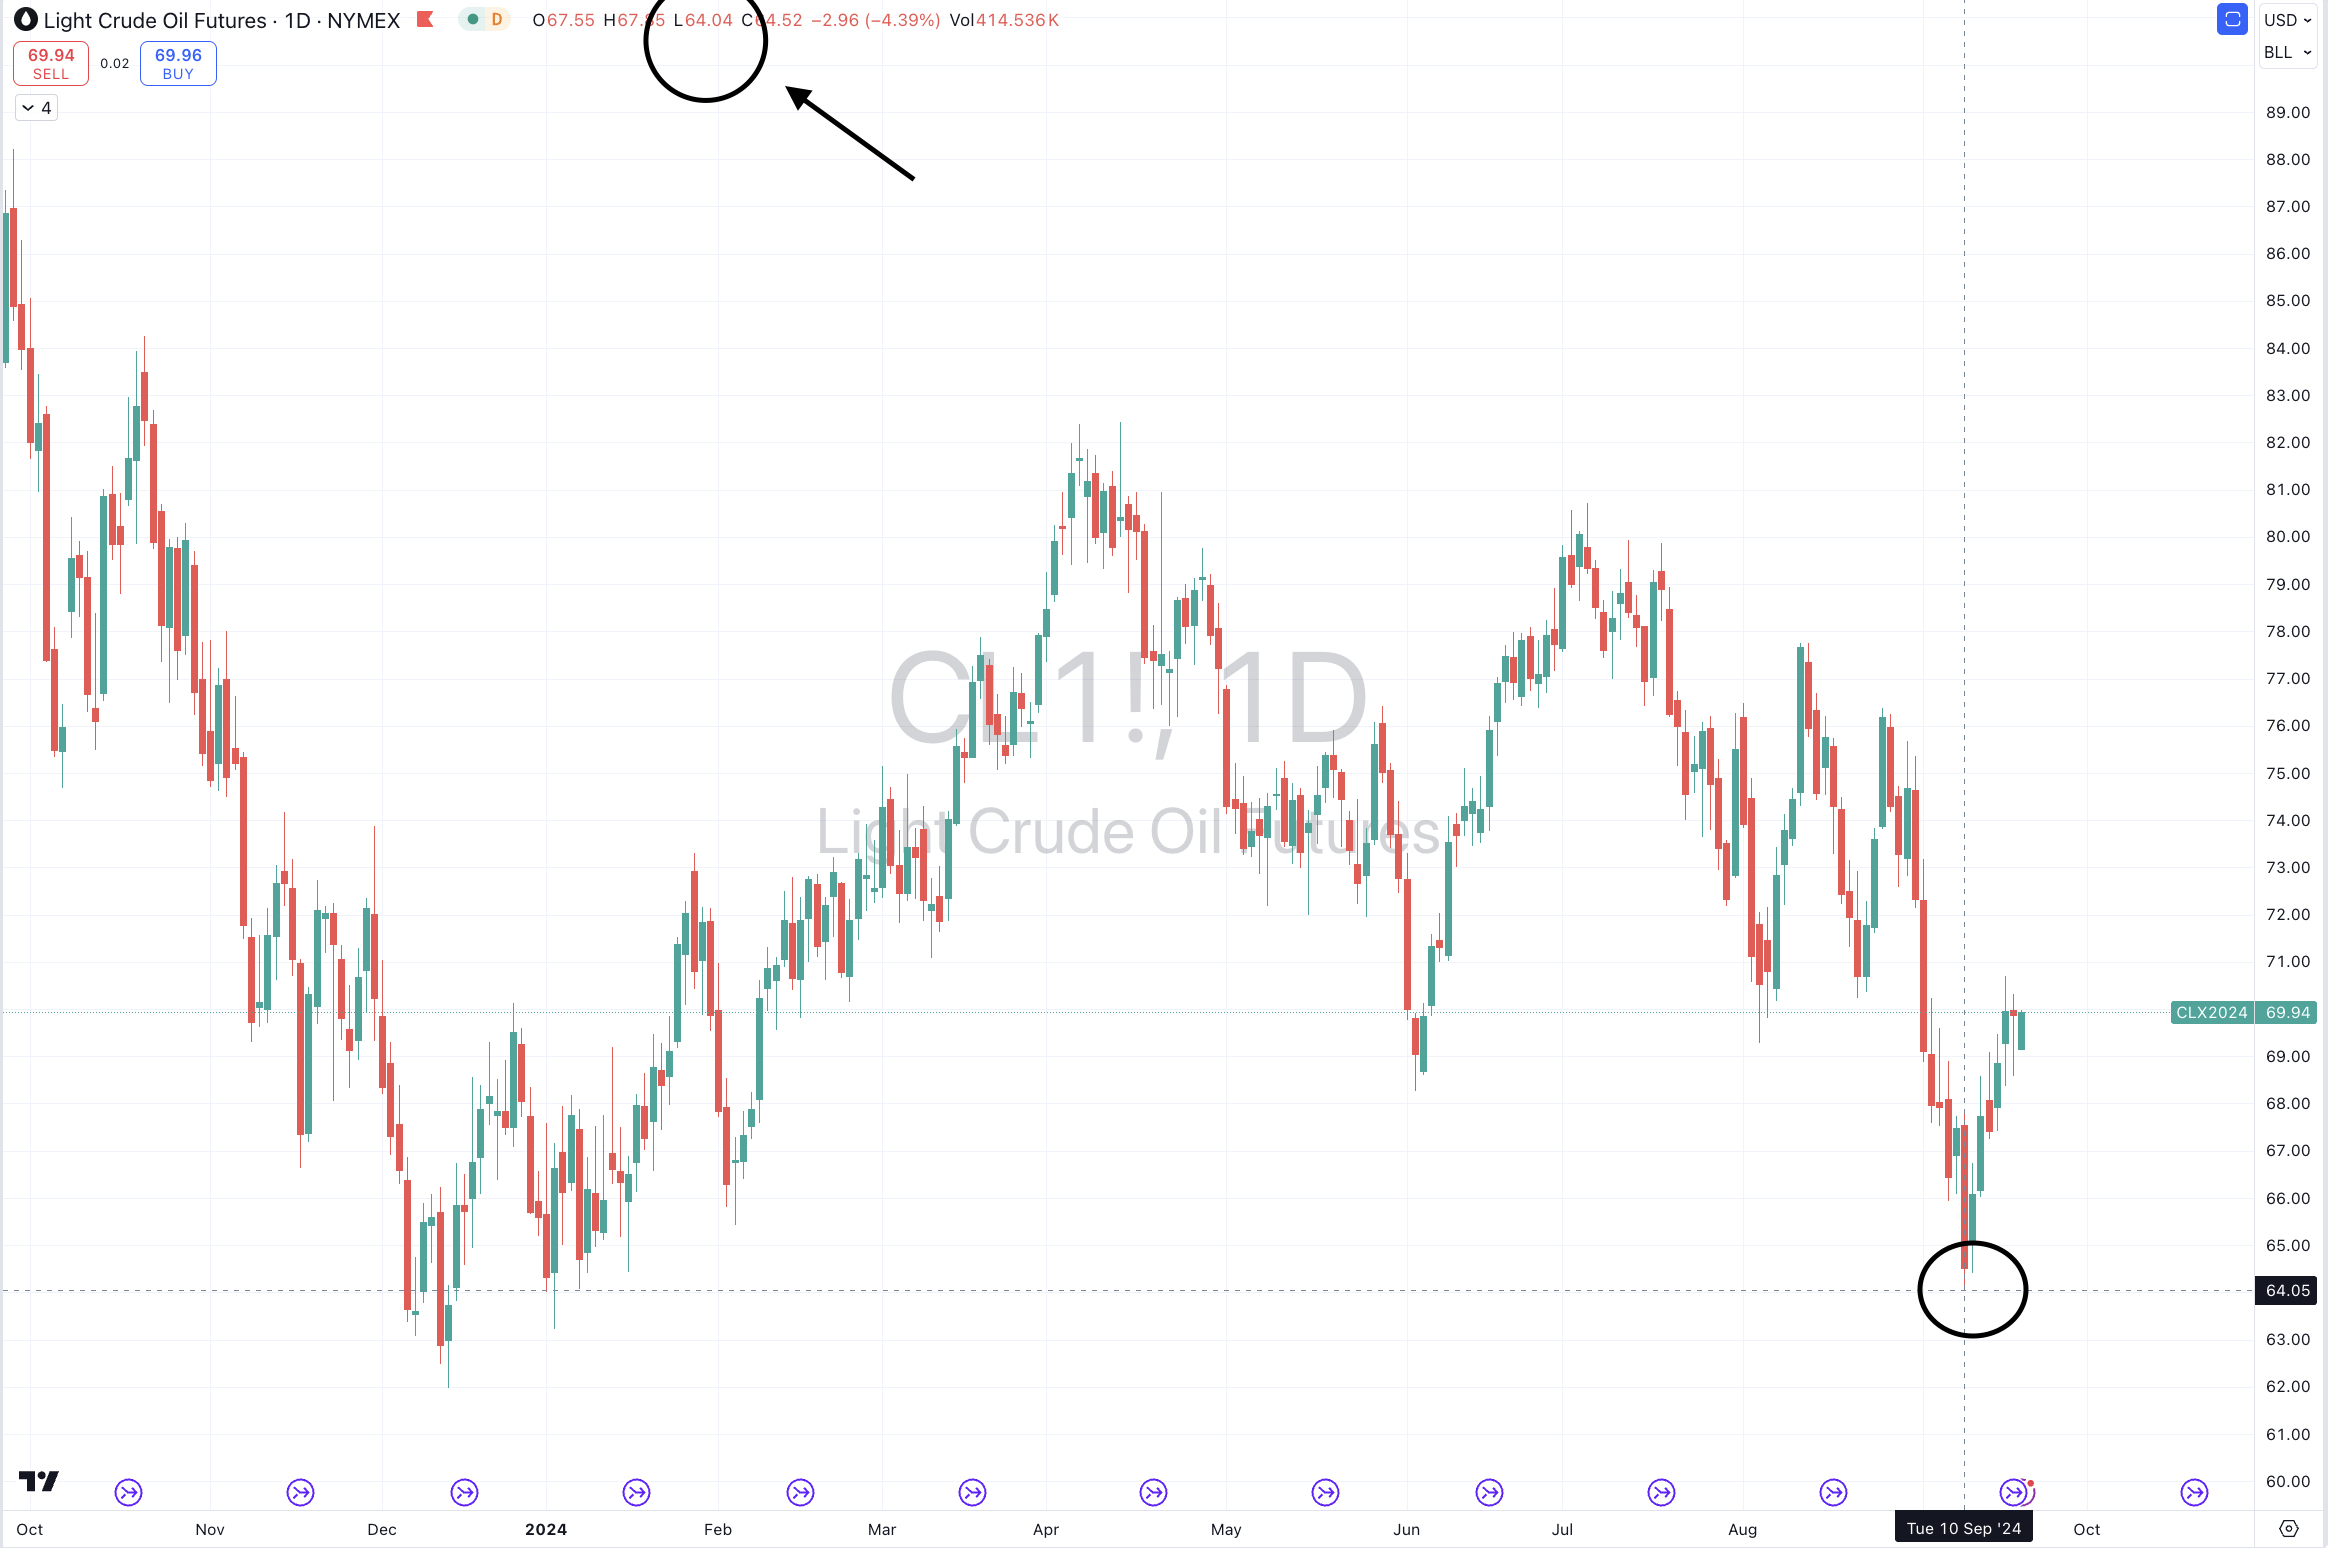
Bloomberg Commodity Index 2.1%, Baltic Dry Index 4.6%, WTI Crude Oil 5.3%, Cotton 5.3%, Lean Hogs 4.8%, Copper 2.5%, Heating Oil 3.5%, Lumber 2.3%, Cattle 2.5%, LNG JKM in Yen 4.4%, Newcastle Coal 2.9%, Natural Gas 5.6%, Nickel 4.1%, Gasoline 5.3%, Sugar 19.2%, S&P GSCI 2.8%, CRB Index 3.1%, Brent Crude 3.6%, Gasoil 2.5%, Gold in CHF 1.8%, Gold in USD 1.7%, Rice 1.9%, KBW Bank Index 4.7%, DJ Industrials 1.6%, HSCEI 5.1%, Hang Seng 5.1%, IBEX 1.9%, IDX 1.6%, S&P Small Cap 600 2.3%, MOEX 3.9%, Russell 2000 2.2%, TAEIX 1.8%, Nasdaq Composite 1.5%, KSE 3.5%, S&P MidCap 400 2%, Nikkei 225 3.1%, Stockholm 2.1%, PSI 3.3%, South Africa 2%, Sensex 2%, SET 1.9%, S&P 500 1.4%, STI 1.7%, ASX Financials 2.4%, ASX Small Caps 1.8% and Turkiye’s BIST rose 2.2%.
The group of largest decliners from the week included;
JKM LNG (2.7%), Arabica Coffee (3.4%), Platinum (2.5%), Robusta Coffee (4%), Dutch TTG Gas (3.4%), Corn (2.8%), Oats (2.7%), Wheat (4.4%), BOVESPA (2.8%), Copenhagen (2.6%) and the Tel Aviv 35 fell 2.8%
September 22, 2024
by Rob Zdravevski
rob@karriasset.com.au