Macro Extremes (week ending January 17, 2025)

A weekly Macro, Cross Asset review of prices trading at extremes which may generate future investment ideas and opportunities.

The following assets (on a weekly timeframe) either registered an Overbought or Oversold reading and/or have traded more than 2.5 standard deviations above or below its rolling mean.

* denotes multiple week inclusion

Extremes above the Mean (at least 2.5 standard deviations)

Chilean and Japanese 2 year government bond yields

German and Japanese 5 year government bond yields

Austrian, Canadian, German, Danish, Spanish, French, Greek, Italian, Japanese, Dutch and Portuguese 10 year government bond yields

Australian 10 year minus Australian 2 year bond yield spread

U.S. 10 year minus U.S. 2 year bond yield spread

Bloomberg Commodity Index

Brent Crude Oil *

WTI Crude Oil *

Heating Oil *

Cattle

Natural Gas *

Gasoil *

Gasoline 

S&P GSCI Index

CRB Index

Corn *

CAD/GBP

Italy’s MIB Index

Chile’s IGPA Index

And the U.K.’s FTSE 100

Overbought (RSI > 70)

Brazilian 10 year government bond yield *

DXY Index *

Arabica Coffee *

Gold as priced in AUD, CAD, GBP and EUR

Austria’s ATX Index

Hungary’s BUX Index

Germany’s DAX Index

Pakistan’s KSE Index *

Czech Republic’s PX Index *

Israel’s TA35 *

The Overbought Quinella (Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)

Urea U.S. Gulf 

Extremes below the Mean (at least 2.5 standard deviations)

Belgian and Finnish 10 year government bond yields * 

Rotterdam Coal

Raw Sugar

Egypt 30 Index

KLSE

FTSE 250

And Thailand’s SET Index

Oversold (RSI < 30)

Chinese 10 year government bond yields * 

U.S. 3 month government bill yield *

Australian Coking Coal

Richards Bay Coal

Newcastle Coal *

North European Hot Rolled Coil Steel *

U.S. Midwest Hot Rolled Coil Steel *

Lithium Carbonate *

Lithium Hydroxide *

CAD/USD

EUR/USD

GBP/USD

RMB/USD *

DKK/USD *

INR/USD *

The Oversold Quinella (Both Oversold and Traded at < 2.5 standard deviations below the weekly mean)

None 

Notes & Ideas:

Government bond yields fell.

The Euro 10 year yield has risen for 6 weeks straight as has the US10/2 yield spread.

Spanish, French, Italian, Dutch and Portuguese 10 year bond yields have risen for 5 weeks. 

The U.S. 5 year bond minus the U.S. 3 month bill yield spread fell from overbought territory.

And the noise surrounding the heights in the British 30 year bond yield, resulted in it declining for the week.

Equities had a terrific week.

All the notable gainers appear in the ‘advancers’ list below.

Only a few Asian indices saw weakness. 

Copenhagen’s OMX25 was the rare decliner in western markets due to Novo Nordisk accounting for 12% of the index weighting.

The past week saw an overbought extreme for Britain’s FTSE 100 juxtaposed against the FTSE 250 registering an oversold extreme.

The Czech Republic’s PX Index has risen for 7 consecutive weeks and for 16 of the past 18 weeks.

Israel’s Tel Aviv 35 Index had climbed for 8 straight weeks and for 13 of the past 14.

The Regional Banks (KRE) Index broke it for 6 consecutive weeks of decline.

The DAX is at an all-time high.

The BUX, SMI, AEX, FTSE 100, Nasdaq Transports, IBEX and Norways OBX have risen for 4 weeks in a row.

The Nikkei 225 has fallen for the past 3 weeks.

While Chinese and Hong Kong equities recovered last weeks declines.

Commodity prices were mostly higher.

The 3 major commodity indices are overbought.

Aluminium is at its highest weekly close since April 2024.

Gasoline has climbed for 4 consecutive weeks.

Corn has risen for 6 of the past 7 weeks.

While Orange Juice is in a 4 week losing streak.

The few losers for the week included Platinum, Sugar, Lumber, Australian Coking Coal and the Baltic Dry Index.

Coal prices remain in oversold territory.

Gold as priced in CAD has risen for 7 consecutive weeks, while AUD Gold broke its 6 week winning streak.

Sugar has fallen for 13 of the past 15 weeks.

U.S.Midwest Hot Rolled Coil Steel has spent 34 weeks being oversold,

while Lithium Hydroxide has now lingered in weekly oversold territory for 85 consecutive weeks.

Currencies continue to provide much action.

Compared to last week’s list, many currencies have departed the oversold region.

Although, notably, there are still a few which are oversold compared to the USD.

The DXY (USD) Index remains in overbought territory,

The AUD was stronger except vs the JPY and ZAR 

and the Aussie broke its 6 week losing streak again the USD.

The Euro was mixed 

And the Yen was firmer.

The weakness in the Loonie continued as it touched a 22 year low versus the USD.

Oddly, the Canadian Dollar registered an overbought extreme against the British Pound.

While the Swiss broke its 5 weeks losing streak against the USD, its lowest weekly close since March 2023.

The larger advancers over the past week comprised of;

Richards Bay Coal 2%, Aluminium 5.4%, Rotterdam Coal 3.3%, Cocoa 5.7%, WTI Crude Oil 2.9%, Heating Oil 3.5%, JKM LNG in ¥ 1.8%, Newcastle Coal 4.1%, Nickel 2.3%, Gasoline 1.9%, Dutch TTF Gas 4.2%, CRB Index 1.7%, Gasoil 3.1%, Corn 2.9%, Oats 10.4%, Rice 2.4%, Shanghai Composite 2.3%, CSI 300 2.1%, All Developed World ex uSA 1.8%, AEX 2.7%, ATX 3.5%, KBW Banks 8.2%, BUX 3.8%, CAC 3.8%, China A50 2.3%, DAX 3.4%, DJ Industrials 3.7%, Dow Jones Transports 3.2%, MIB 3.4%, HSCEI 3.1%, Hang Seng 2.7%, IBEX 1.7%, BOVESPA 2.9%, IDX 1.8%, S&P SmallCap 600 4.3%, Russell 2000 4%, Nasdaq Composite 2.5%, KRE Regional Banks 8.2%, KSE 1.8%, FTSE 250 4.4%, S&P MidCap 400 4.5%, Nasdaq 100 2.9%, Helsinki 2.1%, Stockholm 3.7%, PX 2%, SA40 1.8%, SOX 5.4%, Chile 2.1%, S&P 500 2.9%, TA35 3.1%, FTSE 100 3.1%, WIG 1.8% and the ASX Materials Index rose 2.6%.  

The group of largest decliners from the week included;

Australian Coking Coal (2.2%), Baltic Dry Index (5.8%), Lean Hogs (1.7%), JKM LNG (2.2%), Lumber (2.1%), Platinum (3.1%), Cane Sugar (5.2%), Raw Sugar (2.1%), Gold in ZAR (1.5%), KLSE (2.2%), Nikkei 225 (1.9%), Copenhagen (2.1%), SET (2%) and Philippines PSE fell 2.2%.

January 19, 2025

By Rob Zdravevski

rob@karriasset.com.au

The Swiss Franc is unloved

The #Swiss Franc versus the USD has traded down to its lowest point since March 2023.

That’s just a price point fact, nothing more.

The Swissie is in a downtrend and it still has strength. It’s out of favour.

‘We’ love to sell the Swissie when risk is ‘on’,

but I think the medium low is near if it doesn’t make a new ‘lower low’.

If it does, we should see a quick visit to the 1.0680 region and that would be an attractive buying point.

but also, I’m observing some divergence in the #Swissie compared to other assets.

January 19, 2025

rob@karriasset.com.au

Screenshot

22 year low in the CAD/USD

The #Canadian Dollar is at its lowest weekly and monthly closing price since April 2003.

On a weekly basis, it is trading at one of my extremes.

Not yet on a monthly basis,

but there lows in the #loonie correlates to the overall #commodity complex.

January 18, 2025

rob@karriasset.com.au

Screenshot

Goodbye ESG, for sure !

And as I wrote in August of 2022,

“Whether or not, #DeSantis wins the Republican presidential nomination, look for Ashley #Moody (#Florida’s Attorney-General) to get a plumb job in the ’next’ republican federal government.”

Today’s news is that Ron DeSantis selects Ms Moody to replace Mario Rubio’s senate seat.

I can’t help to start pondering the investing ramifications and the ‘favours to be curried’.

Ms Moody could certainly help put the final nail into the ESG coffin.

Matt #Levine implied that “maybe ESG is illegal now” in his recent #Bloomberg opinion article.

https://www.bloomberg.com/opinion/articles/2025-01-14/maybe-esg-is-illegal-now?sref=qLOW1ygh

You can read that original note in amongst my Linkedin posts or on my blog.

January 16, 2025

rob@karriasset.com.au

Macro Extremes (week ending January 10, 2025)

A weekly Macro, Cross Asset review of prices trading at extremes which may generate future investment ideas and opportunities.

The following assets (on a weekly timeframe) either registered an Overbought or Oversold reading and/or have traded more than 2.5 standard deviations above or below its rolling mean.

* denotes multiple week inclusion

Extremes above the Mean (at least 2.5 standard deviations)

Austrian, Chilean, French & Dutch 10 year government bond yields

Eurozone 5 year government bond yield

Bloomberg Commodity Index

Brent Crude Oil

WTI Crude Oil

Heating Oil

Cattle

Natural Gas *

Gasoil

Corn

Overbought (RSI > 70)

Japanese 2,5 and 10 year government bond yield *

Brazilian, Europe and British 10 year government bond yields *

U.S. 5 year bond yield minus the U.S. 3 month bill yield *

DXY Index *

Arabica Coffee

Gold as priced in AUD, CAD and EUR

Hungary’s BUX Index

Pakistan’s KSE Index *

Czech Republic’s PX Index *

Israel’s TA35 *

The Overbought Quinella (Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)

Australian 10 year bond yield minus Australian 2 year bond yield *

Australian 10 year bond yield minus Australian 5 year bond yield *

U.S. 10 year bond yield minus U.S. 2 year bond yield spread *

Urea U.S. Gulf 

Gold in ZAR

Extremes below the Mean (at least 2.5 standard deviations)

Belgian 10 year government bond yields * 

ZAR/USD *

FTSE 250 Index

Oversold (RSI < 30)

Chinese 10 year government bond yields * 

U.S. 3 month government bill yield *

North European Hot Rolled Coil Steel *

U.S. Midwest Hot Rolled Coil Steel *

Lithium Carbonate *

Lithium Hydroxide *

AUD/THB

AUD/USD

CAD/USD *

EUR/USD

GBP/USD

NZD/USD

RMB/USD *

DKK/USD *

INR/USD *

KRW/USD *

SGD/USD *

The Oversold Quinella (Both Oversold and Traded at < 2.5 standard deviations below the weekly mean)

Newcastle Coal *

Notes & Ideas:

Government bond yields rose.

The Euro 10 year yield has risen for 6 weeks straight as has the US10/2 yield spread.

Spanish, French, Italian, Dutch and Portuguese 10 year bond yields have risen for 5 weeks. 

Many of the spreads appearing in last weeks list, no longer appear.

And Czech 10’s broke their 5 week rising streak.

Equities mostly declined.

The Czech Republic’s PX Index has risen for 13 of the past 14 weeks.

Israel’s Tel Aviv 35 Index had climbed for 7 straight weeks and for 12 of the past 13.

Some U.S. indices had bearish outside reversal weeks.

Brazil’s BOVESPA breaks its 4 week losing streak and bounces out of oversold.

The Regional Banks (KRE) Index has fallen for 6 consecutive weeks.

While Chinese and Hong Kong equities were notable decliners, again.

The HSCEI Index has fallen 16% since it registered an overbought quinella at the beginning of October 2024.

Commodity prices were mixed.

The broader commodity indices rose due to the weighting of their constituents.

The Bloomberg Commodity Index is overbought while the CRB is near.

Oils, Gases, Precious Metals, Grains and Base Metals were the notable gainers.

Coal, LNG, Cocoa and Orange Juice were amongst the weeks losers.

Arabica coffee returns to being overbought, while Rice bounced from oversold territory.

Coal prices are in oversold territory.

Gold as priced in AUD and CAD has risen for 6 consecutive weeks.

Following last week’s quip, Nickel bounced.

Sugar has fallen for 12 of the past 14 weeks.

Dutch TTF Gas fell 9%, giving up half of the 18% gain seeing the previous 3 weeks. 

U.S.Midwest Hot Rolled Coil Steel has spent 33 weeks being oversold,

while Lithium Hydroxide has now lingered in weekly oversold territory for 84 consecutive weeks.

Currencies were active, again and again.

The DXY (USD) Index remains in overbought territory,

The AUD was weak and it returns to being oversold versus the USD and against the THB.

It has fallen 6 weeks straight against the former.

The Loonie rose and did the Yen.

The Pound Sterling was weaker.

The Swiss Franc has fallen for 5 weeks against the USD.

The Loonie remains oversold versus the USD as does China’s Renminbi.

And the NZD/USD has fallen for 13 of the past 15 weeks.

The larger advancers over the past week comprised of;

Aluminium 3.7%, Bloomberg Commodity Index 4.1%, Brent Crude 3.6%, WTI Crude Oil 3.5%, Lean Hogs 2.2%, Copper 5.7%, Heating Oil 6.5%, Lumber 2.1%, Cattle 2.4%, Tin 4.5%, Natural Gas 18.9%, Nickel 3.7%, Palladium 5%, Platinum 5%, S&P GSCI 3.1%, CRB Index 3.4%, Urea U.S. Gulf 4%, Gasoil 4.2%, Silver in AUD 3.9%, Silver in USD 2.7%, Gold in AUD 3.1%, Gold in CAD 1.7%, Gold in CHF 2.8%, Gold in EUR 2.6%, Gold in GBP 3.7%, Gold in USD 2%, Gold in ZAR 4.1%, Corn 4.4%, Oats 1.9%, Rice 3.8%, Soybean 3.4%, BUX 2.5%, CAC 2%, DAX 1.6%, Chile 1.6% and Italy’s MIB rose 2.8%.

The group of largest decliners from the week included;

Australian Coking Coal (4.1%), Richards Bay Coal (7.1%), Rotterdam Coal (6.6%), Baltic Dry Index (2.2%), Cocoa (5.9%), JKM LNG in Yen (5.1%), Lithium Hydroxide (7.2%), Newcastle Coal (7.3%), Orange Juice (3.1%), Sugar (2.2%), Sugar (2.7%), Dutch TTF Gas (9.3%), Uranium (1.7%), KBW Banks (2.3%), China A50 (2.8%), DJ Industrials (1.8%), Egypt 30 (2.1%), HSCEI (3.7%), Hang Seng (3.5%), Jakarta (2%), S&P Small Caps 600 (2.7%), Russell 2000 (3.4%), Nasdaq Composite (2.3%), KLSE (1.7%), KRE Regional Banks (3.7%), KSE (3.7%), FTSE 250 (4.2%), S&P MidCap 400 (1.7%), Nasdaq Biotech (1.7%), Nasdaq 100 (2.2%), Nikkei 225 (1.8%), NIFTY (2.4%), SENSEX (2.3%), SOX (2.4%), Vietnam (1.9%) and the S&P 500 fell 1.9%.

January 12, 2025

By Rob Zdravevski

rob@karriasset.com.au

Gilts have risen but not at extremes

British 30 year bond yields are in todays financial market news.

Much being said about their new highs being made.

It’s OK, they can float around here (+/- 1%).

They might be a little stretched but not at an extreme.

Same goes for #British 10’s.

January 7, 2025

rob@karriasset.com.au

#gilts

Screenshot

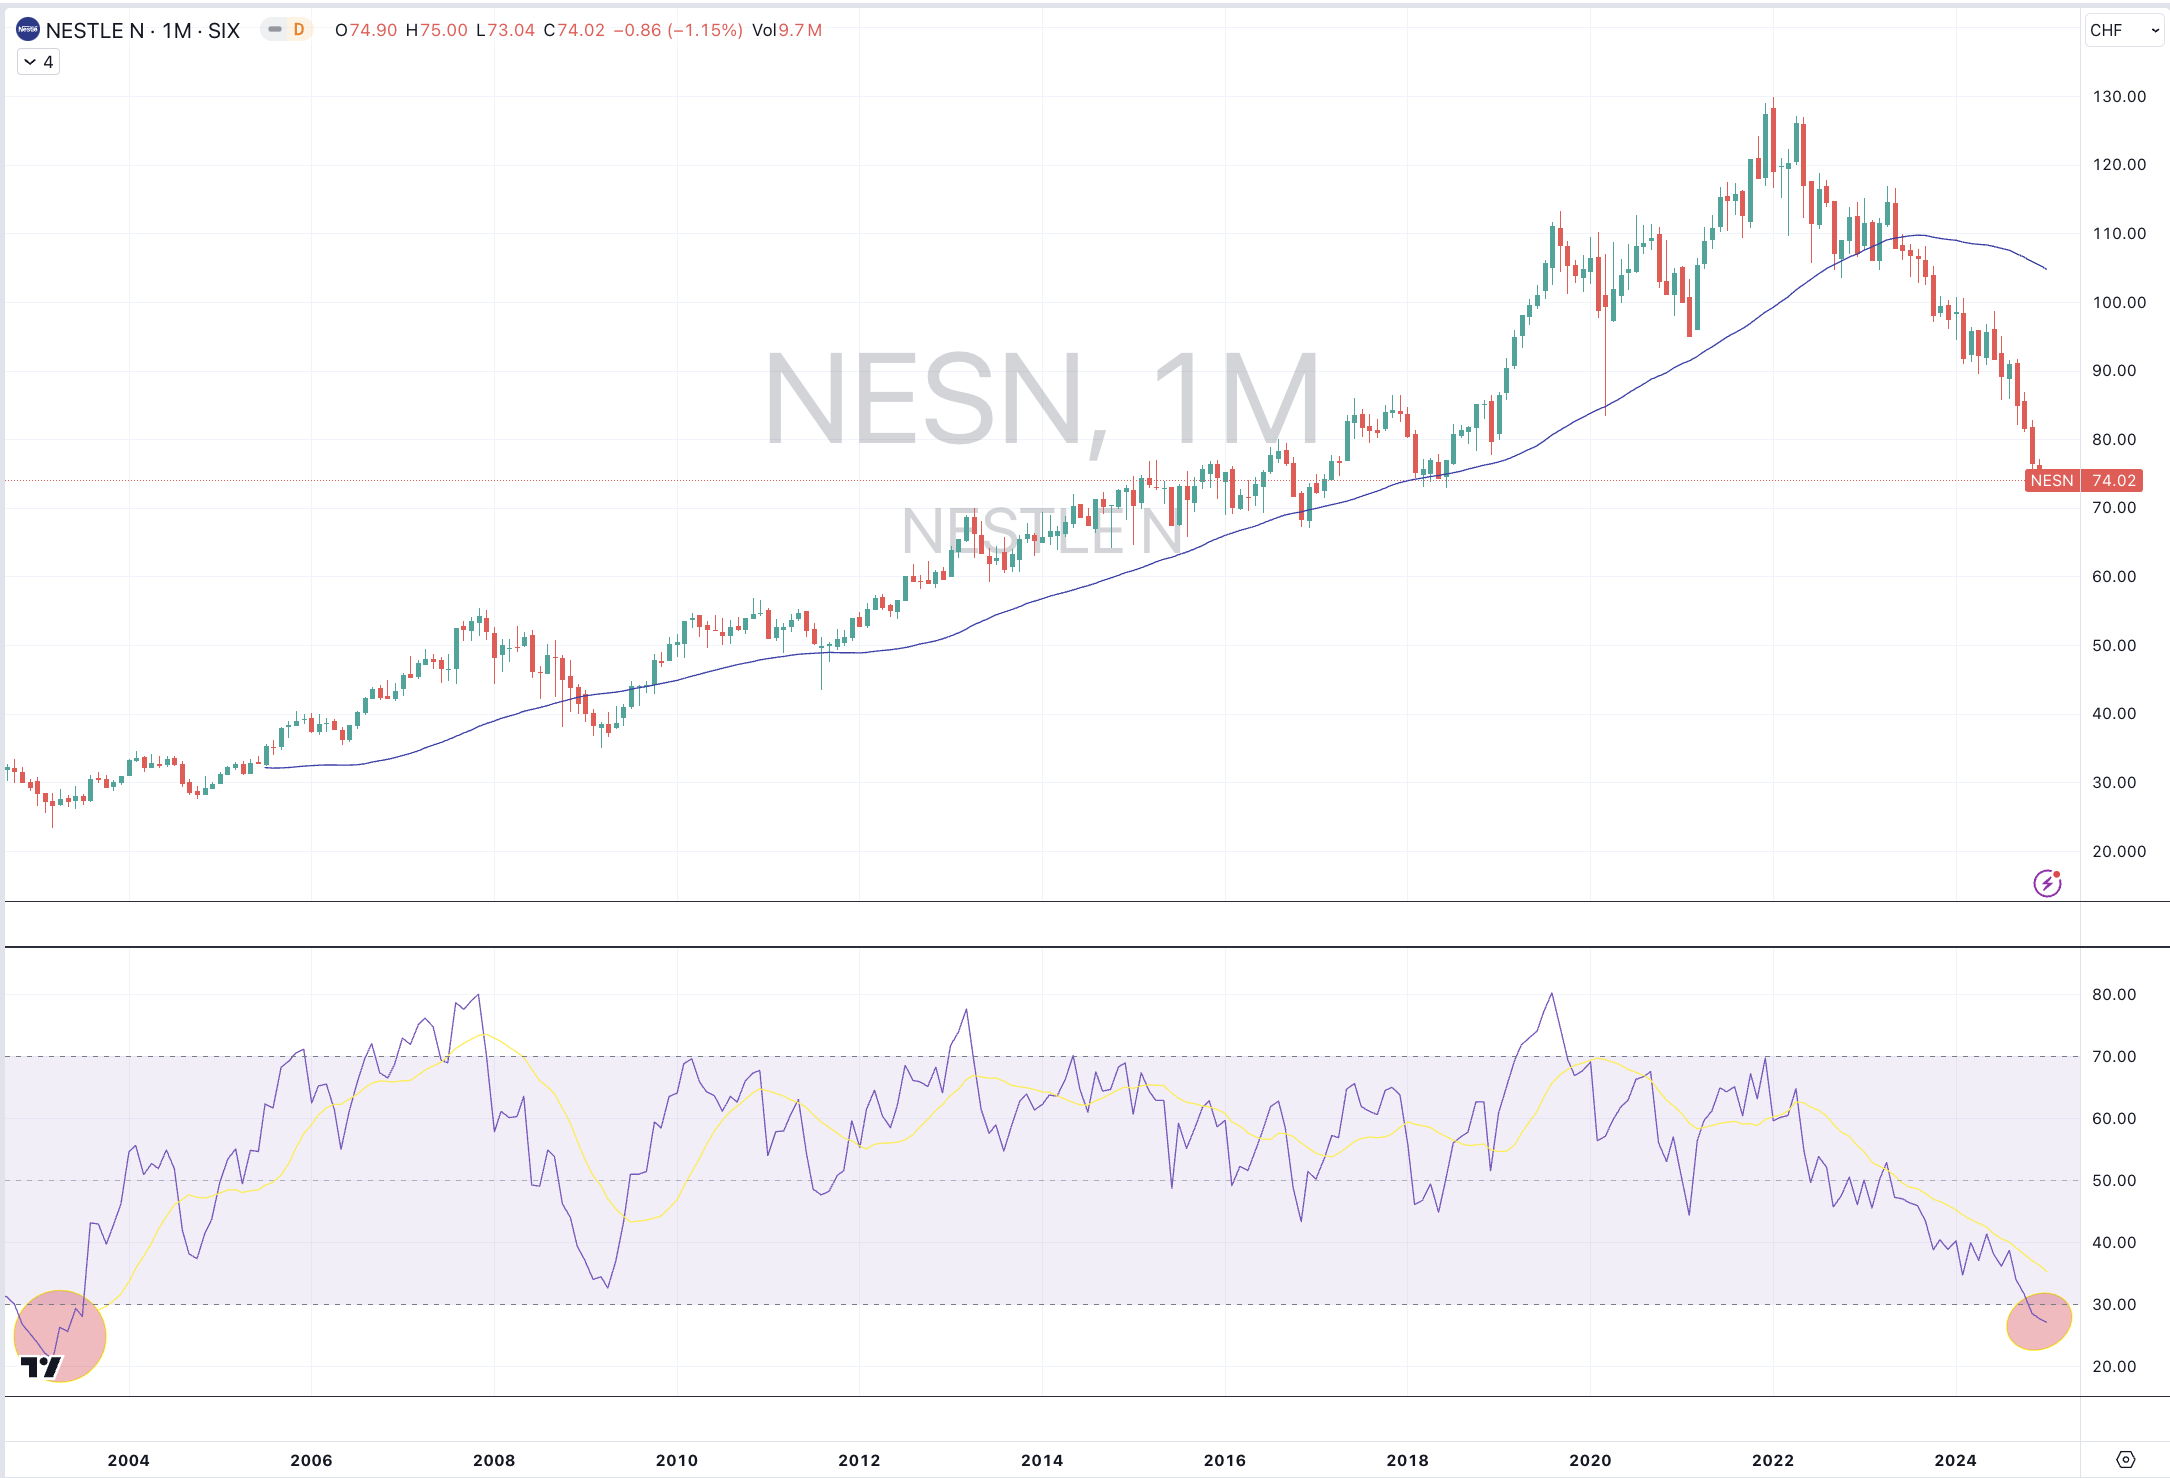
A rare extreme in Nestle’s stock price

22 years ago was the last time when Nestle shares registered a monthly oversold reading.

January 7, 2025

rob@karriasset.com.au

Screenshot

Macro Extremes (week ending January 2025)

A weekly Macro, Cross Asset review of prices trading at extremes which may generate future investment ideas and opportunities.

The following assets (on a weekly timeframe) either registered an Overbought or Oversold reading and/or have traded more than 2.5 standard deviations above or below its rolling mean.

* denotes multiple week inclusion

Extremes above the Mean (at least 2.5 standard deviations)

Australian 10 year bond yield minus Australian 5 year bond yield *

U.S. 10 year bond yield minus Australian 10 year bond yield spread *

U.S. 10 year bond yield divided by the Australian 10 year bond yield spread *

Austrian 10 year government bond yield

Japan Korean Marker (JPM) LNG *

Natural Gas *

CAD/AUD

GBP/AUD *

Overbought (RSI > 70)

Japanese 2 year government bond yield *

Brazil 10 year government bond yield *

U.S. 5 year bond yield minus the U.S. 3 month bill yield *

DXY Index

Pakistan’s KSE Index *

Czech Republic’s PX Index *

Israel’s TA35 *

The Overbought Quinella (Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)

None

Extremes below the Mean (at least 2.5 standard deviations)

Australian 10 year bond yield minus U.S. 10 year bond yield spread *

Rice

AUD/IDR

AUD/GBP *

AUD/CAD

EUR/USD

NZD/USD

RMB

ZAR/USD *

Egypt 30 Index

Oversold (RSI < 30)

U.S. 3 month government bill yield *

North European Hot Rolled Coil Steel *

U.S. Midwest Hot Rolled Coil Steel *

Lithium Carbonate *

Lithium Hydroxide *

Newcastle Coal *

BRL/USD *

CAD/USD *

DKK/USD

KRW/USD *

SGD/USD

Brazil’s BOVESPA Index

The Oversold Quinella (Both Oversold and Traded at < 2.5 standard deviations below the weekly mean)

Chinese 10 year government bond yields *

INR/USD *

Notes & Ideas:

Government bond yields were mixed again.

The Euro 10 year yield has risen for 5 weeks straight.

Belgian, Finnish, Spanish, French Italian, Portuguese and Belgian yields have fallen for 4 consecutive weeks

All British yields and Brazilian 10’s broke their respective 4 and 6 week rising streaks.

And Chinese 10’s resumed their decline falling to a new low of 1.6%.

Equities mostly rose.

Strength tended to favour the small/mid caps over the large caps.

The Czech Republic’s PX Index has risen for 12 of the past 13 weeks.

Israel’s Tel Aviv 35 Index had climbed for 6 straight weeks.

Brazil’s BOVESPA has fallen for 4 straight weeks and enters the oversold region.

The Regional Banks (KRE) Index is in 6 week losing streaks.

While Chinese and Hong Kong equities were notable decliners.

Commodity prices were mixed.

Oil, Gases, Coking Coal, Shipping Rates, Cocoa, Uranium were the notable gainers.

Aluminium, Steel, Wheat, Lumber, Rubber and Nickel prices were amongst the weeks losers.

Arabica coffee isn’t overbought this week.

Australian Coking Coal not oversold, nor is Uranium.

Gold as priced in AUD and CAD has risen for 5 consecutive weeks.

Corn broke its 4 week rising streak.

Nickel is now trading 32% below its 200 week moving average and at its lowest close since early June, 2020.

Sugar has fallen for 11 of the past 13 weeks.

Dutch TTF Gas has climbed 19% over the past 3 weeks.

Palladium and Uranium broke their respective 5 and 6 weeks of declines. 

U.S.Midwest Hot Rolled Coil Steel has spent 32 weeks being oversold,

while Lithium Hydroxide has now lingered in weekly oversold territory for 83 consecutive weeks.

Currencies were active, again.

The big news was the DXY (USD) Index entering overbought territory,

And the resulting extremes appearing in this weeks list.

The Aussie, Loonie and Yen were firmer.

Swiss was weak as was the Euro and Pound Sterling.

The Chilean Peso is in a 5 week losing streak versus the USD.

And the AUD bounced from being oversold against the Thai Baht.

EUR/JPY and JPY/USD broke their 4 straight weeks of gains.

The Loonie remains oversold versus the USD as does China’s Renminbi.

And the NZD/USD has fallen for 12 of the past 14 weeks as it registers its lowest close since May 2009.

The larger advancers over the past week comprised of;

Australian Coking Coal 4.6%, Baltic Dry Index 7.5%, Brent Crude 4.1%, Cocoa 11%, WTI Crude 4.7%, Heating Oil 4.4%, Cattle 1.8%, JKM LNG in Yen 2.5%, Lithium Hydroxide 2.5%, Gasoline 4.2%, Sugar 1.5%, S&P GSCI 1.9%, CRB Index 1.8%, Dutch TTF Gas 3.4%, Gasoil 3.3%, Uranium 6.5%, Gold in EUR 1.9%, Gold in GBP 2%, Pakistan 5.6%, Oslo 2.6%, Poland’s WIG 2% and Jakarta Composite rose 1.8%.

The group of largest decliners from the week included;

Aluminium (3.3%), Cotton (1.8%), North European Hot Rolled Coil Steel (3.1%), Lean Hogs (4%), Copper/Gold Ratio (2%), U.S. Midwest Hot Rolled Coil Steel (3%), Lumber (3.7%), Lithium Carbonate (6%), Newcastle Coal (1.8%), Nickel (1.5%), Rubber (2.7%), Wheat (3.2%), Shanghai Composite (5.6%), CSI 300 (5.2%), China A50 (3.9%), HSCEI (2%), Hang Seng (1.6%) and Taiwan’s TAEIX fell 1.6%.

January 5, 2025

By Rob Zdravevski

rob@karriasset.com.au

Macro Extremes (week ending December 27, 2024)

A weekly Macro, Cross Asset review of prices trading at extremes which may generate future investment ideas and opportunities.

The following assets (on a weekly timeframe) either registered an Overbought or Oversold reading and/or have traded more than 2.5 standard deviations above or below its rolling mean.

* denotes multiple week inclusion

Extremes above the Mean (at least 2.5 standard deviations)

Australian 10 year bond yield minus Australian 2 year bond yield 

Australian 10 year bond yield minus Australian 5 year bond yield 

Chilean 2 and 10 year government bond yields

Swedish 10 year government bond yield

Japan Korean Marker (JPM) LNG

Natural Gas

Overbought (RSI > 70)

Japanese 2 year government bond yield

U.S. 5 year bond yield minus the U.S. 3 month bill yield *

Arabica coffee *

Pakistan’s KSE Index *

Czech Republic’s PX Index *

Israel’s TA35 *

The Overbought Quinella (Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)

Brazil 10 year government bond yield

U.S. 10 year bond yield minus Australian 10 year bond yield spread *

U.S. 10 year bond yield divided by the Australian 10 year bond yield spread *

Extremes below the Mean (at least 2.5 standard deviations)

Rice

AUD/GBP

AUD/SGD

ZAR/USD

Oversold (RSI < 30)

U.S. 3 month government bill yield *

Australian Coking Coal *

North European Hot Rolled Coil Steel *

U.S. Midwest Hot Rolled Coil Steel *

Lithium Carbonate *

Lithium Hydroxide *

Newcastle Coal *

RMB/USD *

CAD/USD

The Oversold Quinella (Both Oversold and Traded at < 2.5 standard deviations below the weekly mean)

Australian 10 year bond yield minus the U.S. 10 year bond yield spread

Chinese 10 year government bond yields *

Uranium

AUD/THB *

BRL/USD *

INR/USD *

KRW/USD *

Notes & Ideas:

Government bond yields were mixed overall, with a bias for higher rates. 

Euro 5’s and 10’s yields have risen for 4 weeks straight.

Yields across the British curve have also climbed for 4 weeks, as have Swedish 10’s.

The South Korean 10 year yield has bounced since its oversold reading 3 weeks ago.

Brazilian 10’s have risen for 6 weeks.

Chinese yields broke their 6 consecutive weeks of declines.

The U.S. 10 minus Euro 10 spread is nearly overbought.

While this week sees the return of the Aussie yield curve return to overbought territory.

Equities were stronger, reversing the previous 2 weeks of weakness.

The overreactive decline following last weeks Fed announcement seems comical now. 

The Czech Republic’s PX Index has risen for 11 of the past 12 weeks.

Israel’s Tel Aviv 35 Index had climbed for 5 straight weeks.

The Russell 2000 rose and Oslo’s OBX Index broke their 4 week losing streak.

The Regional Banks (KRE) Index is in 5 week losing streaks.

And Indonesia’s IDX is nearly oversold.

Commodity prices were mixed.

Gases, Corn and Wheat were the notable gainers.

Cocoa, Oat and Coal prices were amongst the weeks losers.

Aluminium and JKM LNG (in Yen) broke their 4 week losing streaks.

Gold as priced in AUD and CAD has risen for 4 consecutive weeks, as has Corn.

Nickel is now trading 32% below its 200 week moving average and at its lowest close since early June, 2020.

Sugar has fallen for 11 of the past 12 weeks.

Dutch TTF Gas has climbed 15% over the past 2 weeks.

The Baltic Dry Index broke its 5 week losing streak,

Palladium has declined for 5 weeks, 

while Uranium extends its loses to 6 consecutive weeks.

Lean Hogs and Cocoa broke their respective 5 and 6 straight weeks of gains.

U.S.Midwest Hot Rolled Coil Steel has spent 31 weeks being oversold,

while Lithium Hydroxide has now lingered in weekly oversold territory for 82 consecutive weeks.

Currencies were active, again.

The Aussie was weaker again.

The Thai Baht is at its highest against the AUD since June 2020.

The AUD has fallen for 10 of the past 13 weeks against the USD and the CAD.

The Euro was firmer.

EUR/JPY has risen for 4 straight weeks.

And so, the Yen was weaker and it has fallen for 4 weeks against the USD.

The Loonie remains oversold versus the USD as does China’s Renminbi.

And the NZD/USD has fallen for 11 of the past 13 weeks.

The larger advancers over the past week comprised of;

Aluminium 1.7%, Rotterdam Coal 3.2%, WTI Crude Oil 1.6%, JKM LNG 4.6%, JKM LNG in Yen 11.6%, Dutch TTF Gas 8.1%, Corn 1.7%, Wheat 2.5%, All World Developed ex USA 1.6%, China A50 2%, HSCEI 2.3%, Hang Seng 1.9%, TAIEX 3.4%, KLSE 2.3%, Nikkei 225 4.1%, Oslo 1.8%, Copenhagen 3.3%, Helsinki 1.7%, PSE 1.9%, SET 2.7%, SMI 1.8%, SOX 3.2%, ASX Financials 3.4%, ASX 200 2.4%, ASX Industrials 2.1%, ASX Small Caps and Turkiye’s BIST rose 3.1%.

The group of largest decliners from the week included;

Australia Coking Coal (2%), Cocoa (15.3%), Lean Hogs (2.1%), Newcastle Coal (1.9%), Orange Juice (2.7%), Uranium (3%), Oats (9.5%), Rice (1.5%), Egypt (1.9%) and Brazil’s BOVESPA fell 1.5%.

December 29, 2024

By Rob Zdravevski

rob@karriasset.com.au
What if Amazon’s share price halves?

I think #Amazon‘s stock price can trade down to $122 within the year 2025.

Whether it occurs in 2025 is inconsequential.

It’s a larger concern to those buying the stock at any of these lofty levels.

It’s certainly an uncrowded thought and trade.

Should #AMZN‘s sport a market capitalisation which is $1 trillion less than today, I’m thinking of where the money goes to from the selling proceeds during its decline?

December 28, 2024

rob@karriasset.com.au