The pessimism in Europe is not unwarranted, however the stock market is discounting much.
Around February 26 – March 8, 2022, the DAX equity index triggered a ‘trifecta oversold’ buy signal which bodes well for the longer term investor.
Around the price of 13,200 (similar to today’s level), the DAX registered an Oversold RSI level below 30, traded 2.5 standard deviations below its weekly mean and was below its 200 week moving average.
The following assets (on a weekly timeframe) registered an Overbought or Oversold reading and/or have traded more than 2.5 standard deviations above or below its rolling mean.
Extremes “above” the Mean (at least 2.5 standard deviations)
AUD/GBP (2nd consecutive week)
Nikkei 225
Overbought (RSI > 70)
Dutch TTF Gas
Japan Korean LNG Marker price
The Overbought Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)
Istanbul Stock Exchange (BIST)
Extremes “below” the Mean (at least 2.5 standard deviations)
Japanese 10 year government bond yields
U.S. 10 year minus 5 year government yield spread
Oversold (RSI < 30)
U.S. 5 year minus U.S.3 month government bond yield ‘spread’
Hot Rolled Coiled Steel
Tin
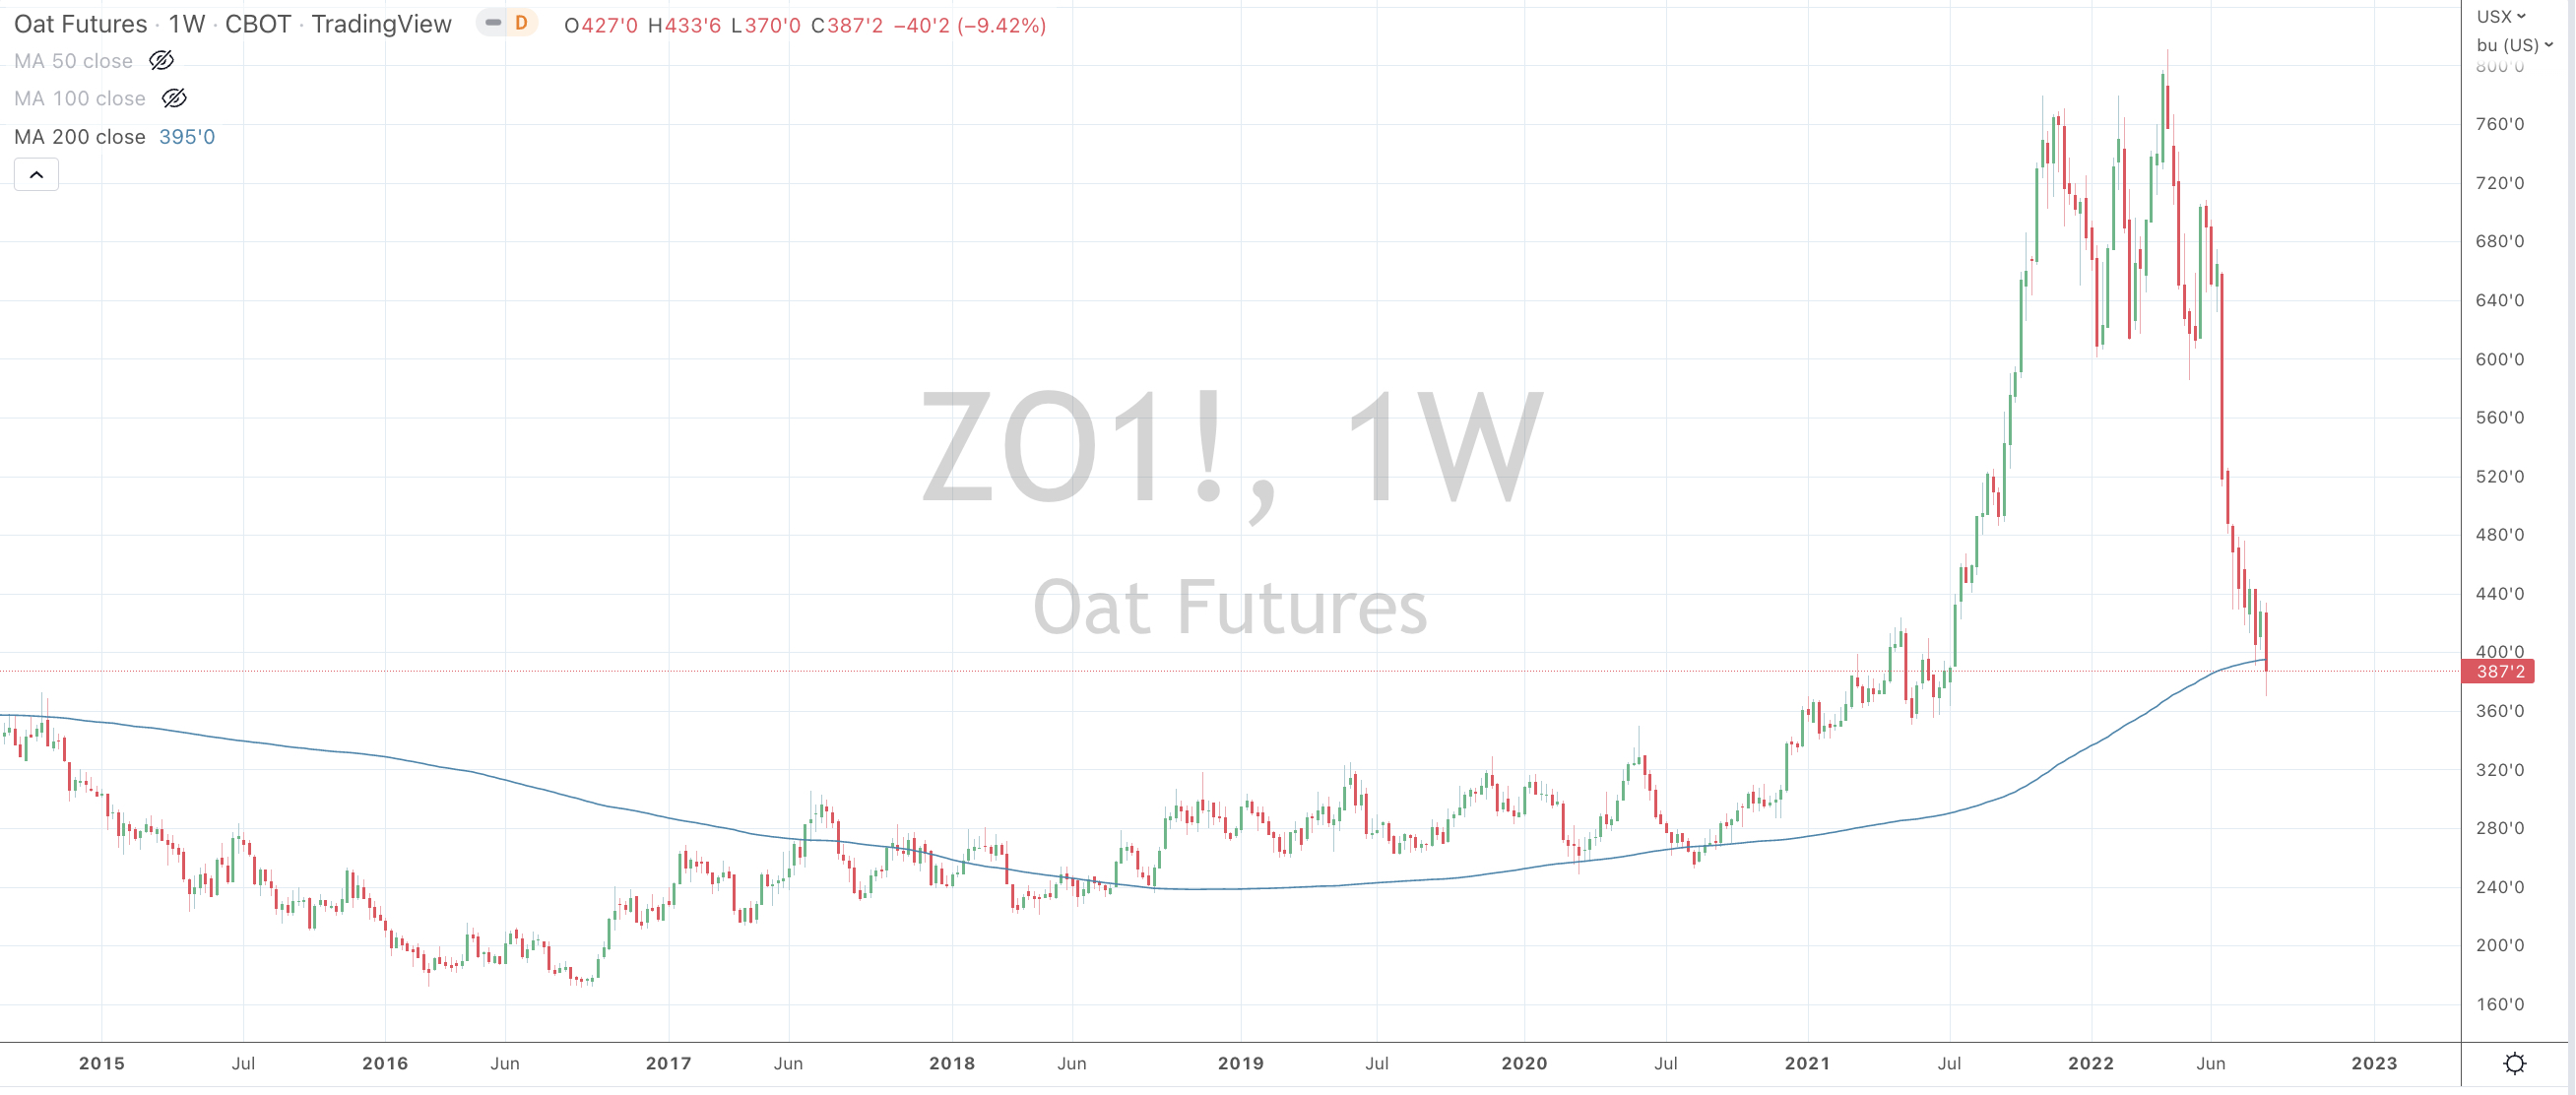
Oats
EUR/USD
DKK/USD
KRW/USD
INR/USD
The Oversold Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)
Chinese 10 year government bond yields
Notes & Ideas:
The big news over the past week included; gas and coal prices extending their rise while many other commodities continued to weaken and the surge in the U.S. Dollar, as we saw various currency crosses return to the extreme list.
The larger currency drops occurred in the Kiwi, the Aussie, the Pound Stirling and the Chilean Peso.
We saw a petering of the equity rally amongst small capitalised U.S. stocks. This was timed with my recent notes that this rally ‘may be done’ and one that it to be rented and not owned.
The U.S. yield curve moved out of Oversold territory, moving from last weeks close of 0.42% (the intra-week low was -0.51%) to its current -0.26% level.
Another notable higher move in yields was the Japanese 10’s rising from 0.16% to 0.19%. I’d count a 21% move as notable.
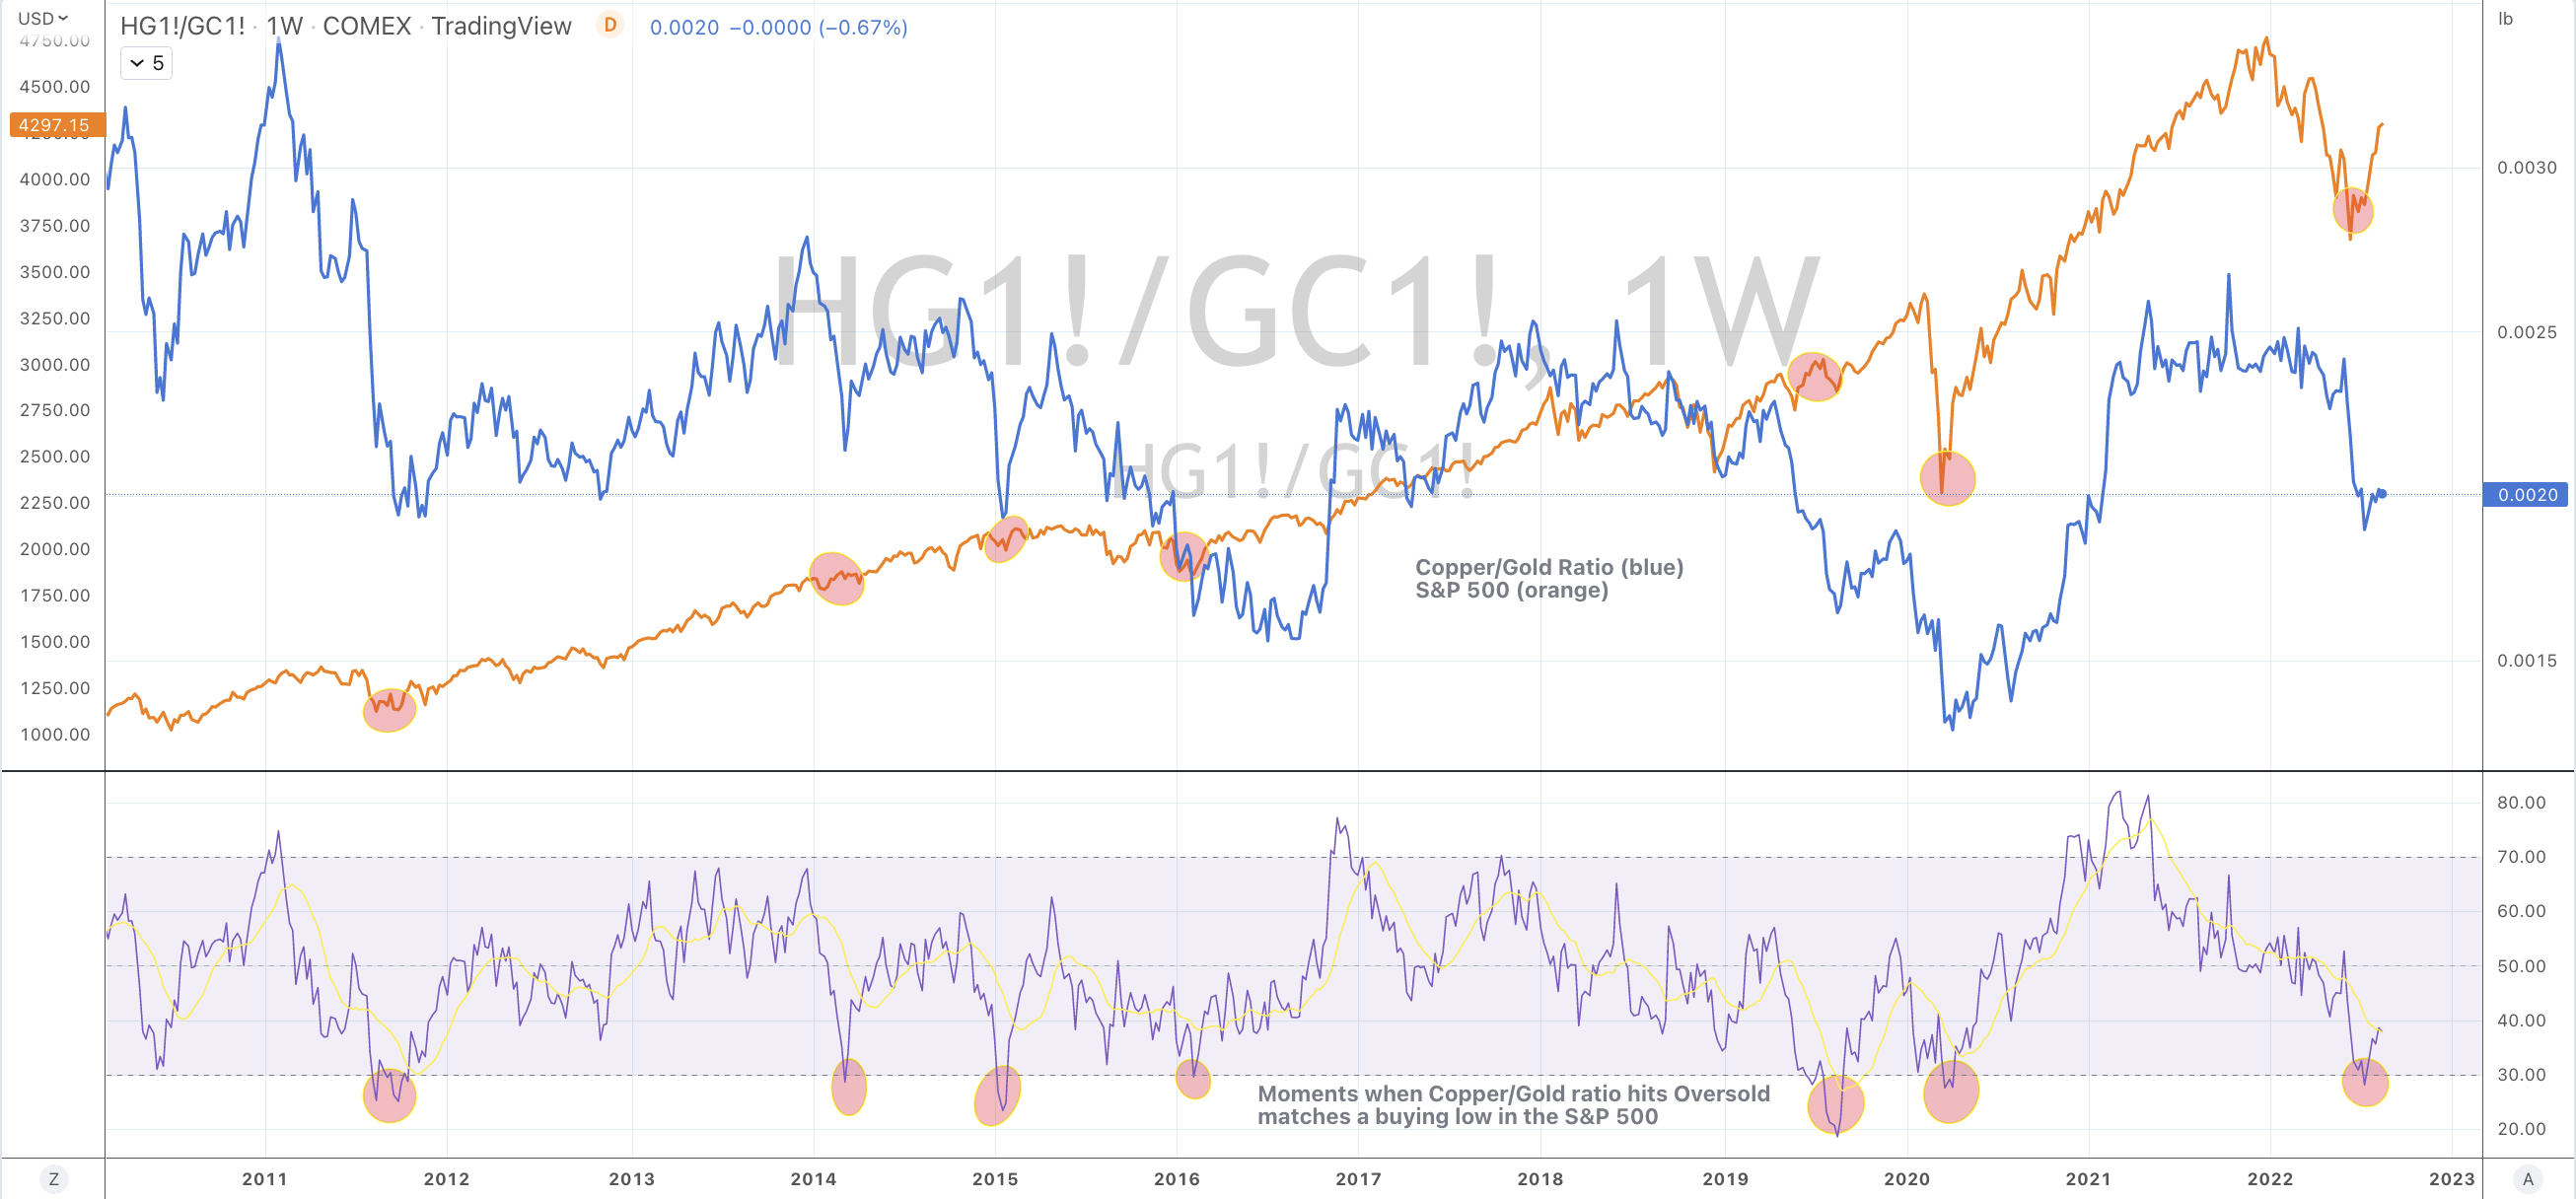
The Copper /Gold ratio is worth watching a barometer of the health of the economy.
On a weekly basis, we may see the early start of a weaker trend in Gasoline although that’s not confirmed.
Oats fell enough to be Oversold and mean revert to its 200 week moving average.
Lumber have given up two-thirds of last week’s 23% advance.
Sugar had a outside bearish reversal week.
The TAIEX has registered a rare 7 consecutive weekly advance.
The larger advancers over the past week comprised of;
Australian Coking Coal 9.5%, Rotterdam Coal 5.9%, China Coal 2.5%, U.S. Dollar Index 2.3%, Gasoil 4%, Copper/Gold Ratio 2.9%, Heating Oil 5.2%, JKM KNG9.9%, Natural Gas 6.5%, Cotton 4.6%, Dutch TTF Gas 18.7%, Istanbul BIST 5.1% and Australia’s ASX 200 rose 1.2%.
The group of decliners included;
Aluminium (2.1%), Baltic Dry Index (13.4%), WTI Crude (1.8%), Gold (2.9%), Lean Hogs (6.9%), Hot Rolled Coil Steel (3.1%), Coffee (4.1%), Lumber (14.6%), Orange Juice (6.2%), Palladium (4%), Platinum (7.4%), Silver (8.5%), Brent Crude (2.1%), Silver in AUD (5.2%), Gold (3.1%), Corn (2.2%), Oats (9.4%), Soybean (3.5%), Wheat (4.3%), AUD/USD (3.4%), EUR/USD (2.2%), GBP/USD (2.5%), NZD/USD (4.3%), CLP/USD (7.9%), KBW Bank Index (2.4%), DAX (1.8%), DJ Transports (2.5%), MIB (1.9%), HSCEI (2%), HSI (2%), Nasdaq 100 (2.4%), Russell 2000 (2.9%), SOX (3.7%), Nasdaq Biotech Index (3.8%) and the Nasdaq Composite fell (2.6%)
Oversold moments in the Copper/Gold ratio synchronises with buying ‘troughs’ in the S&P 500 Index.
If you remember the extreme pessimism felt through May and June 2022, the Copper/Gold ratio is one tool to add to your analysis arsenal which can help quantify that subjective ‘sinking’ feeling, when it arises again.
The following assets (on a weekly timeframe) registered an Overbought or Oversold reading and/or have traded more than 2.5 standard deviations above or below its rolling mean.
Extremes “above” the Mean (at least 2.5 standard deviations)
AUD/GBP
Overbought (RSI > 70)
Dutch TTF Gas
Japan Korean LNG Marker price
The Overbought Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)
Istanbul Stock Exchange
Extremes “below” the Mean (at least 2.5 standard deviations)
Japanese 10 year government bond yields
U.S. 10 year minus 5 year government yield spread
Oversold (RSI < 30)
U.S. 10 year minus U.S. 2 year government bond yield ‘spread’
U.S. 5 year minus U.S.3 month government bond yield ‘spread’
Hot Rolled Coiled Steel
Tin
The Oversold Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)
None
Notes & Ideas:
This big news over the past week was an extension in the equities advance which was mainly appearing in North American markets and the strength in many commodities.
The feature in the latter was amongst the energy complex.
In last week’s edition of Macro Extremes, I wrote,
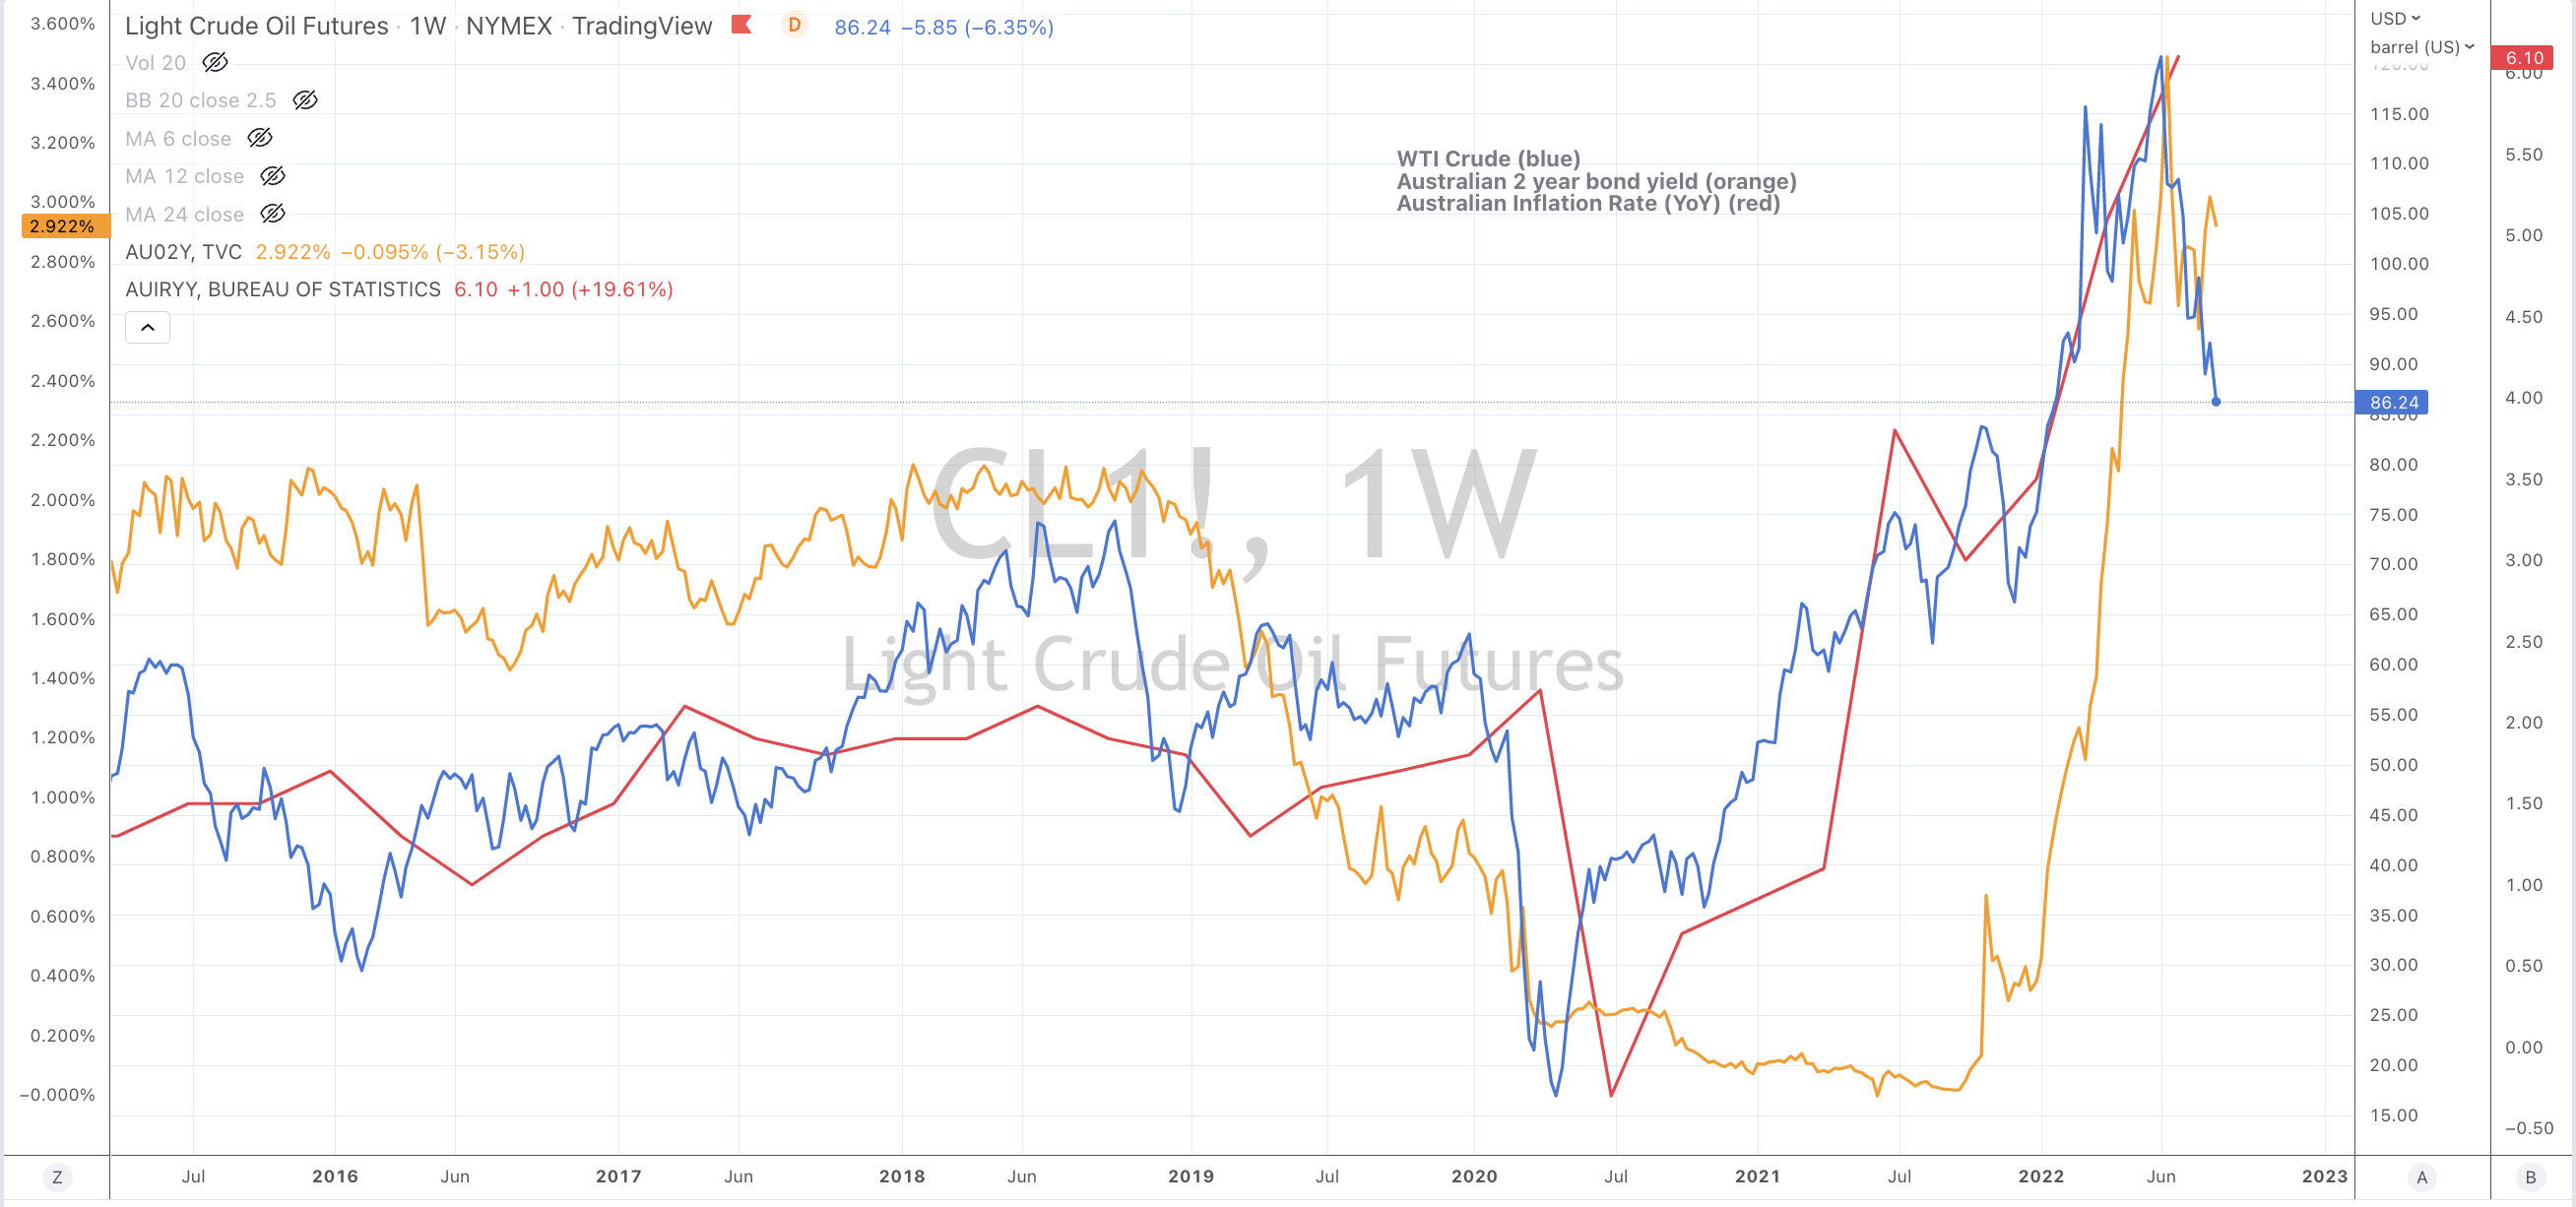
“Now that Gasoil and Crude prices have fallen 30% from their recent highs, Crude Oil specifically is near an interim low and due for a ‘bounce’.
I’ll look for WTI Crude and Brent to trade down to $85.50 and $92.00 respectively.”
That bounce did occur over this past week and WTI Crude and Brent traded near but not quite down to those targets. For example, Brent touched $93.07.
Resilient to recent energy price retracement has selected gas prices.
Over the past 12 weeks, the Japan Korean LNG Marker has risen 137% while the Dutch (European) TTF Gas price has climbed 150% in only 9 weeks.
Lately, I have been writing about how the lows of this recent trading rally were seen in mid June 2022 and Buy signals were appearing in Small and Mid Cap indices.
Since then, the MidCap 400 has rallied 19% and the Russell 2000 has soared 23%, of which 5% occurred in this past week. This adds to the argument of being careful chasing momentum at the tail end of what I see as an interim wave.
Incidentally, that Russell 2000 is still 18% below its November 8, 2021 peak.
This also comes from the playbook that small caps peaked early and likely ‘troughed’ first. There was much damage done in the small caps.
Lastly, the U.S. yield curve remains inverted for the 6th week in a row and Oversold for 4 consecutive weeks.
The larger advancers over the past week comprised of;
Australian Coking Coal 5.8%, Rotterdam Coal 11.8%, Bloomberg Commodity Index 4.5%, Baltic Dry Index 2.1%, Cocoa 3.9%, China Coal 9%, WTI Crude 3.5%, Gasoil 5.6%, Copper 3.3%, Heating Oil 9.4%, JKM 16.2%, Coffee 6.2%, Lumber 22.9%, Natural Gas 8.7%, Palladium 4.3%, Platinum 3.8%, Gasoline 6.7%, Sugar 3.7%, Silver 4.6%, Cotton 12.6%, Dutch TTF Gas 5%, Brent Crude 3.7%, Corn 4.8%, Oats 5.4%, Soybean 3.2%, Wheat 3.9%, KBW Banking Index 5.8%, Dow Jones Industrials 3%, DJ Transports 3.7%, IBEX 2.9%, BOVESPA 5.9%, S&P Midcap 400 4.5%, Nasdaq 2.7%, Helsinki 2%, Russell 2000 4.9%, Sensex 1.8%, S&P 500 3.3%, TAIEX 1.7%, Toronto’s TSX 2.9%, S&P SmallCap 600 3.9%, Nasdaq Composite 3.1% while Australia’a ASX 200 only rose 0.24%.
The short-term rally in the ASX 200 is done (or almost).
It looks exhausted at its current price of 7.057 points. I may give a 10-20% probability of an additional 2.2% spurt up to 7,215, but the 10% rally from its June 20, 2022 low has satisfied my milestones and targets and I think the ‘fat part’ of the trade has been had.
I’ll wait for a retracement to between 6.740 and 6,820 and check on the velocity of the pullback before considering re-entering this Index.
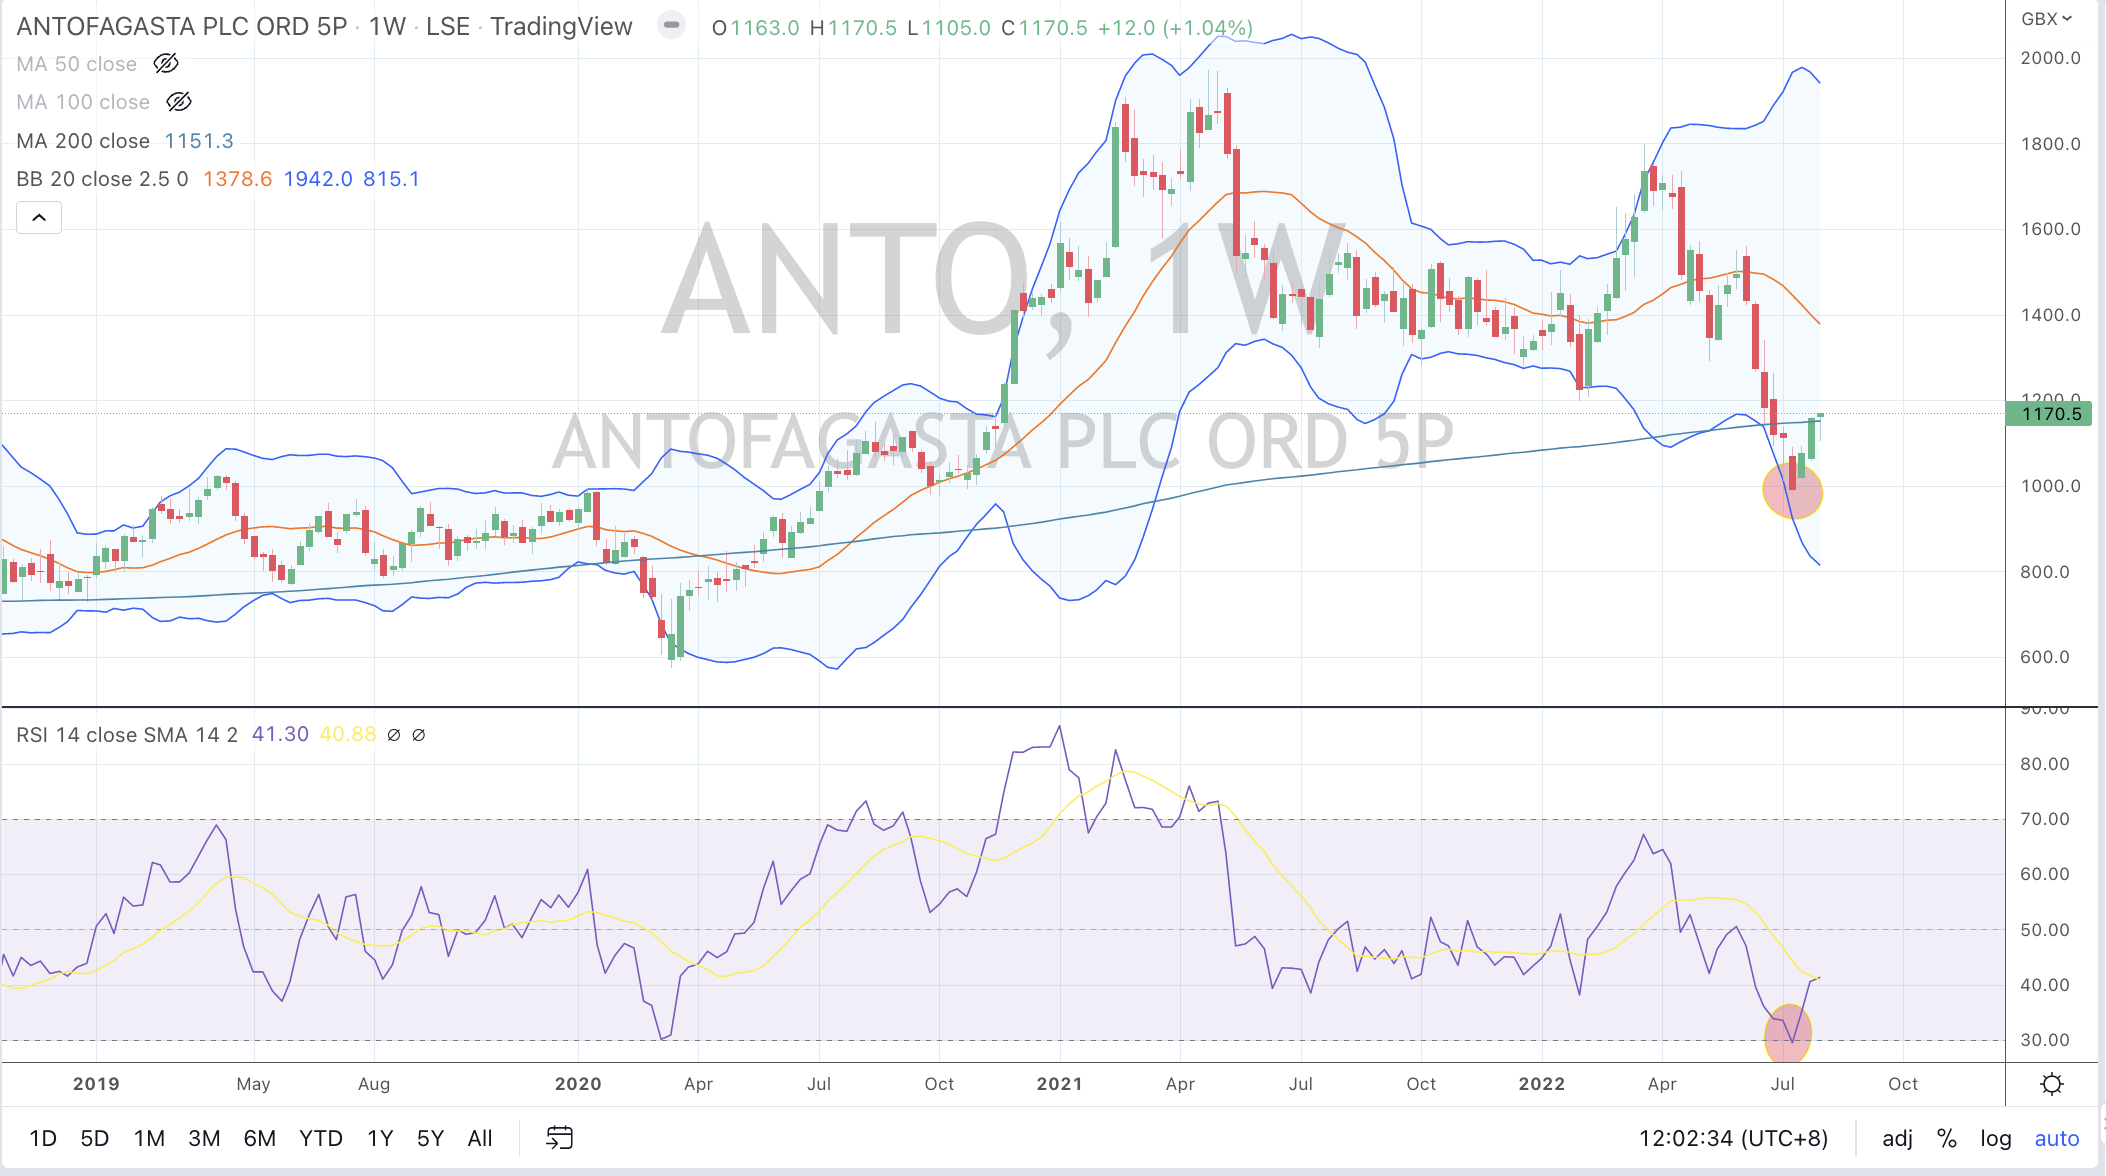
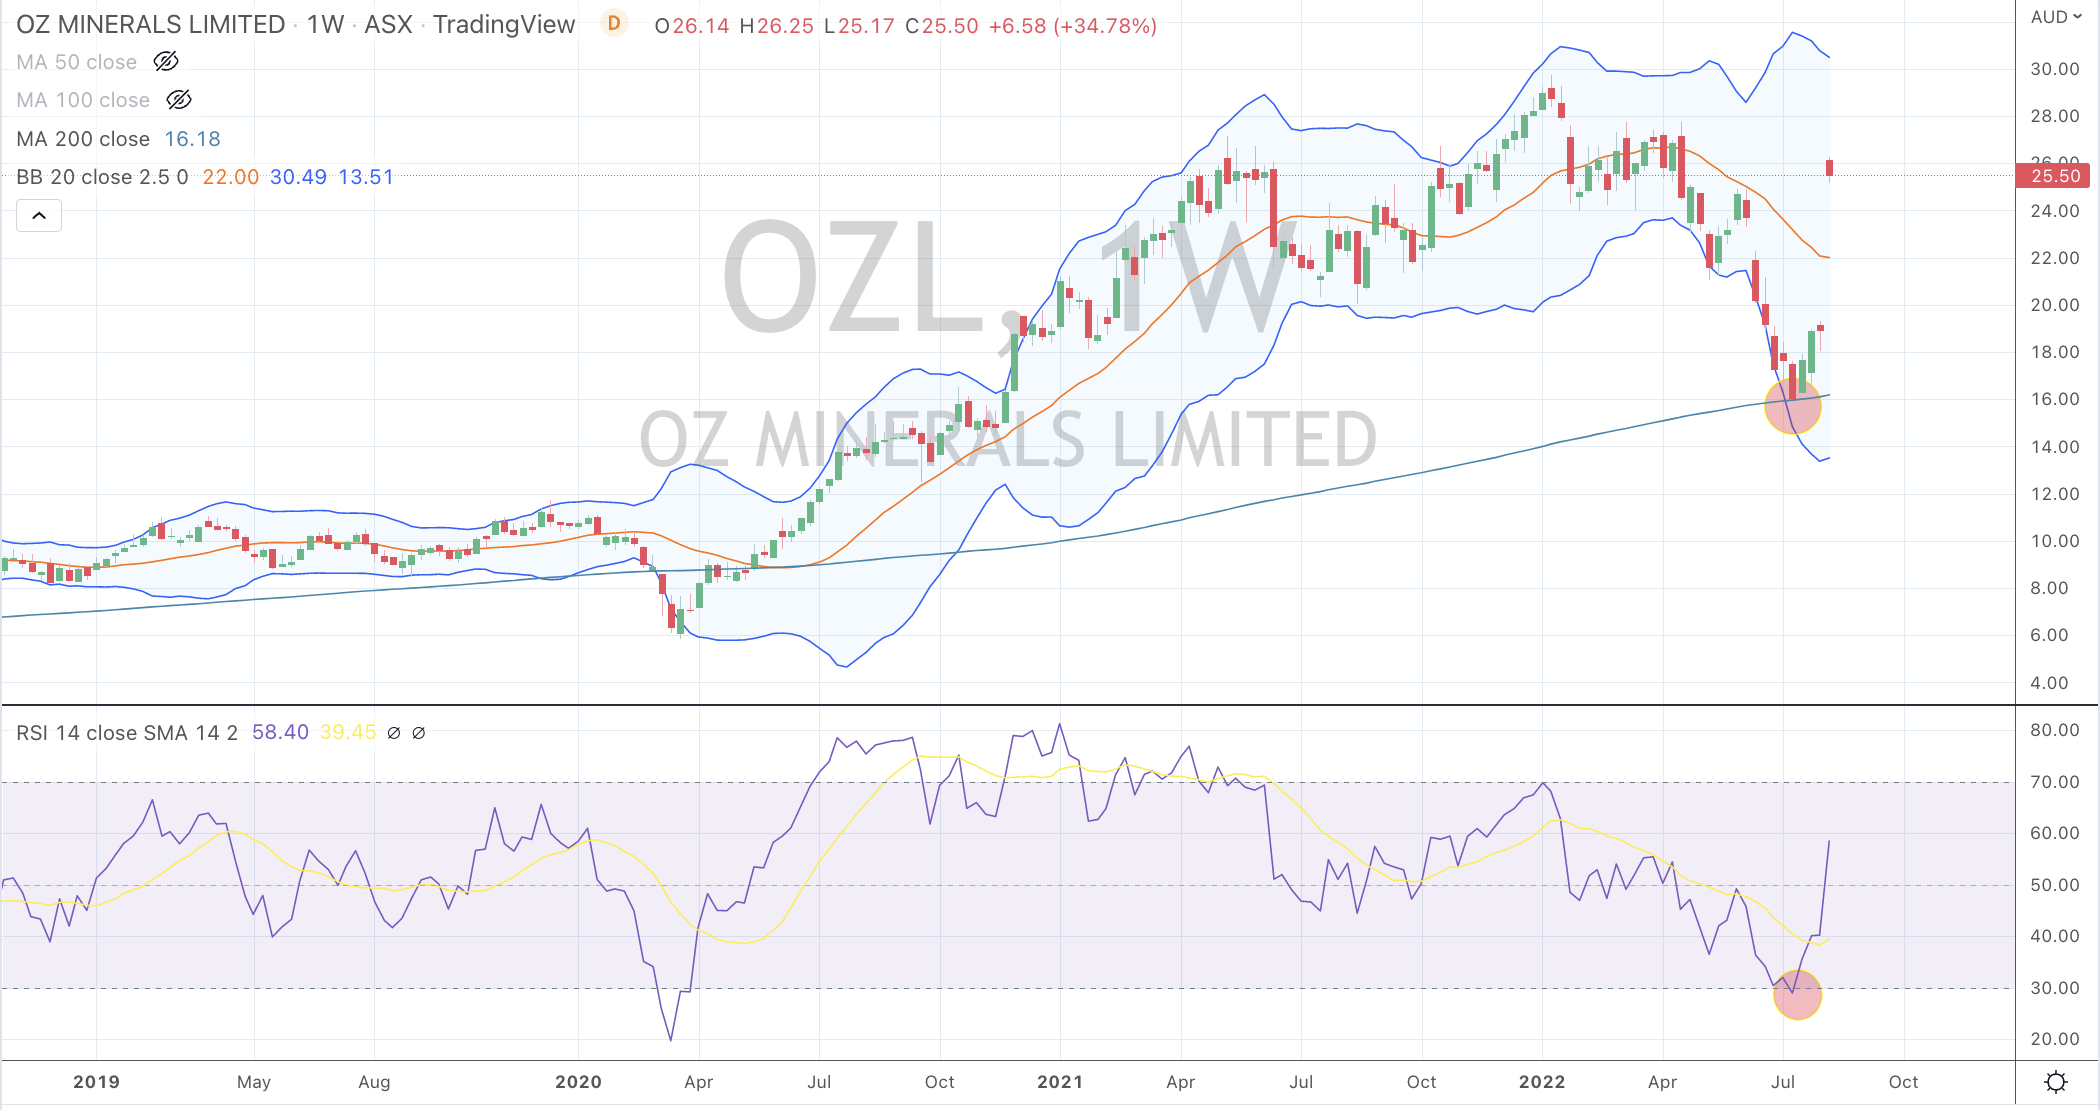
Sandfire’s stock price has risen 38% from its mid July 2022 low.
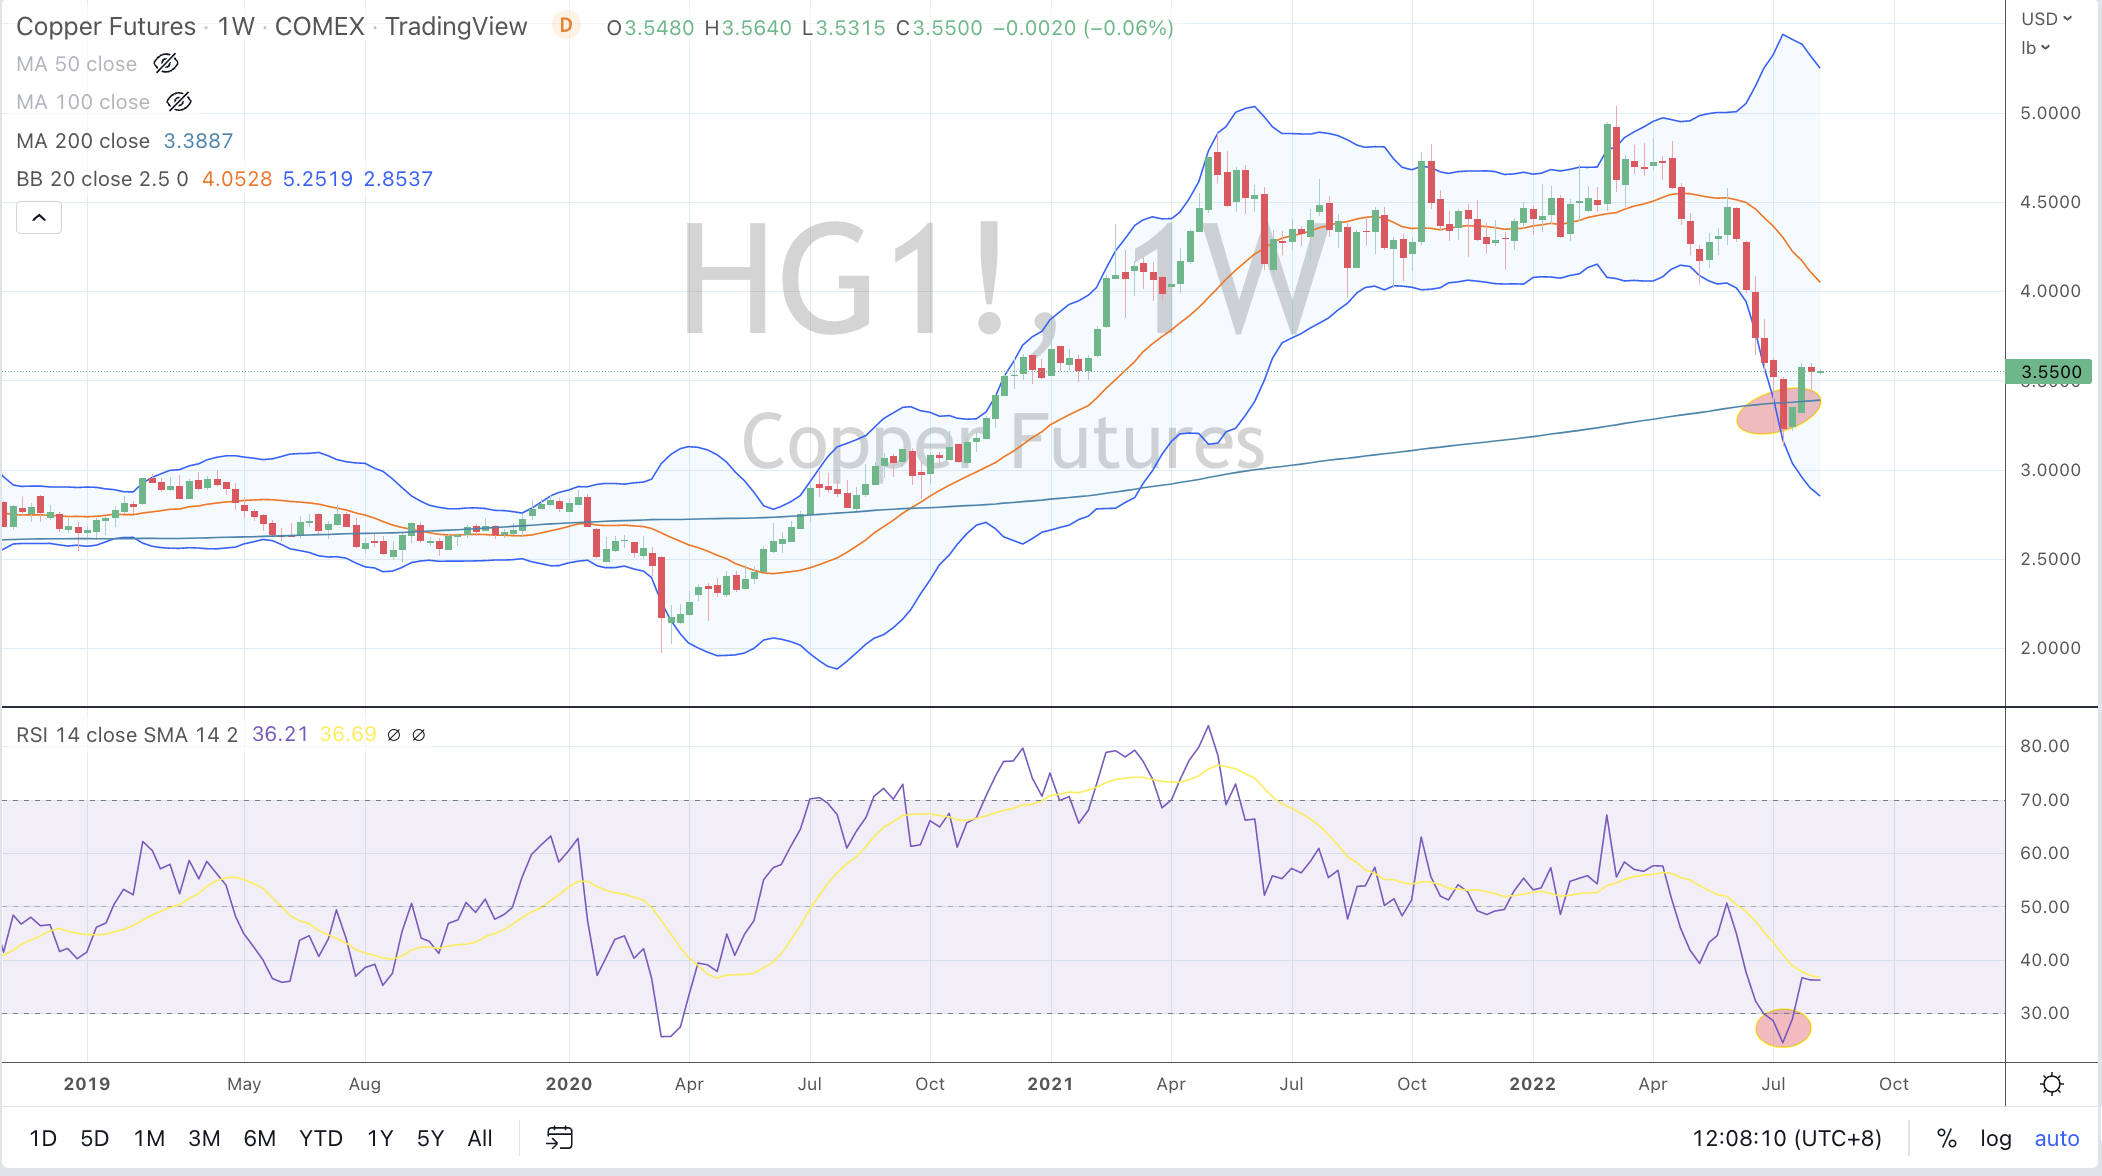
The price of Copper has climbed 40% since then.
In fact, the price of Chilean copper miner, Antofagasta (listed in London), Sandfire Resources, OZ Minerals and the price of Copper all exhibited my trifecta of a mean reversion to its 200 week moving average, trading to 2.5 standard deviations and registering a weekly Oversold RSI reading.
The following assets (on a weekly timeframe) registered an Overbought or Oversold reading and/or have traded more than 2.5 standard deviations above or below its rolling mean.
Extremes “above” the Mean (at least 2.5 standard deviations)
None
Overbought (RSI > 70)
Dutch TTF Gas
The Overbought Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)
None
Extremes “below” the Mean (at least 2.5 standard deviations)
Japanese 10 year government bond yields
Oversold (RSI < 30)
U.S. 10 year minus U.S. 5 year government bond yield
Hot Rolled Coiled Steel
Tin
Oats
The Oversold Quinella – Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)
The U.S. 10 year minus 2 year government bond yield spread.
Notes & Ideas:
This big news over the past week was continued weakness in energy prices and shipping rates. We also experienced the mildest and quietest week in global equities for more than 2 months. It certainly felt that way too.
It was a week to not chase the momentum higher, not initiate any meaningful positions and to trim and sell those assets that have given you a fortuitous return or allowed you to a second chance to recoup some capital.
There was plenty of warning about the pending decline in energy prices.
I was cognisant of Oil’s ‘high’ price as expressed in these posts.
Now that Gasoil and Crude prices have fallen 30% from their recent highs, Crude Oil specifically near an interim low and due for a ‘bounce’.
I’ll look for WTI Crude and Brent to trade down to $85.50 and $92.00 respectively.
Incidentally, Gasoil (diesel) has fallen from $1400 to $990 (a metric ton) over the past 7 weeks. Over the same time WTI Crude has declined from $123 to $89. It’s interest to ‘hear’ the silence in the financial media, as opposed to the noise heard when prices were barreling skywards only a few months earlier.
There is merit to identifying the ‘mean’ are and cancelling out the noise.
The U.S. yield curve remains inverted for the 5th week in a row and Oversold for 3 consecutive weeks.
Keep in mind that when the yield inverted 6 weeks ago, I had earlier written a note citing that such an occurrence is beneficial for the longer term accumulation of the S&P 500.
Over a similar timeframe, the KOSPI and ASX200 have risen 9.4%, the Russell 2000 has advanced 17% while the Nasdaq Biotechnology Index has soared 25.4%.
Today, I think the S&P 500 is closer to a ‘trading sell’ and while the longer term accumulation position remains my stance, tactically I think we’ll see lower prices again, a double dip testing recent lows and a safer opportunity to buy or add to positions.
The next 12 months should prove a notable moment to build an equities portfolio of world class businesses at much more reasonable and palatable valuations.
The larger advancers over the past week comprised of;
Australian Coking Coal 8.1%, Iron Ore 2.4%, JKM LNG 5.8%, Orange Juice 6.3%, Platinum 3.9%, Sugar 2.3%, Dutch TTF Gas 2.8%, Uranium 1.9%, Rice 2.7%, BOVESPA 3.2%, KOSPI 1.6%, Nasdaq 100 2%, Russell 2000 1.9%, SOX 2.9%, STI 2.2%, Istanbul 6.3%, Nasdaq Composite 3.3% and the Nasdaq Biotechnology Index soared 6.8%.
The group of decliners included;
Aluminium (2.7%), Rotterdam Coal (2.3%), Bloomberg Commodity Index (3.3%), Baltic Dry Index (17.7%), China Coal (5.7%), WTI Crude Oil (9.7%), Gasoil (10.5%), Heating Oil (11.3%), Hot Rolled Coil Steel (4.3%), Coffee (3.6%), Lumber (9.1%), LNG (6.6%), Natural Gas (2%), Gasoline (8.3%), Silver USD (2.2%), CRB Index (3.8%), Brent Crude (9%), Urea M/E (3.7%), Oats (8.4%), Soybeans (4.1%), Wheat (4%), MOEX (7.2%) and Copenhagen’s OMX 25 Index fell 2.2%.