Macro Extremes (week ending May 24, 2024)

A weekly Macro, Cross Asset review of prices trading at extremes which may generate future investment ideas and opportunities.

The following assets (on a weekly timeframe) either registered an Overbought or Oversold reading and/or have traded more than 2.5 standard deviations above or below its rolling mean.

* denotes multiple week inclusion

Extremes above the Mean (at least 2.5 standard deviations)

Copper/Gold Ratio *

Bloomberg Commodity Index

Copper

JKM LNG in USD and JPY

Nickel *

Platinum *

Dutch TTF Gas

Wheat *

AUD/SGD

Helsinki *

South Africa 40

And the ASX Materials Index

Overbought (RSI > 70)

Japanese 2, 5 and 10 year government bond yield * 

Tin

AEX *

Austria’s ATX *

Malaysia’s KLSE *

Pakistan’s KSE Index *

Oslo *

Stockholm

TAEIX *

and Turkiye’s BIST 100 *

The Overbought Quinella (Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)

Nickel on MCX

Orange Juice

Extremes below the Mean (at least 2.5 standard deviations)

Australian 10 year minus Australian 2 year government bond yield spread

CAD/EUR

CAD/GBP

USD/ZAR

Oversold (RSI < 30)

North European Hot Rolled Coil Steel *

Lumber *

Lithium Hydroxide *

Sugar

The Oversold Quinella (Both Oversold and Traded at < 2.5 standard deviations below the weekly mean)

None

Notes & Ideas:

Government bond yields rose, mostly.

It was another week of relative quiet action.

The Russian 10 year government bond yield isn’t overbought anymore.

And the U.S. 10 year inflation breakeven rate, mean reverted.

Equities were mainly weaker.

The Hang Seng Index and S&P Small Cap 600 aren’t overbought anymore.

Many other equity indices also dropped out of their overbought extremes.

The KBW Bank Index, Vietnam, CSI 300 and Shanghai Index all broke their weekly winning streaks.

The Nasdaq Composite, KLSE, FTSE 250, Nasdaq 100, S&P 500 and TAEIX have all put together a 5 week winning streak.

Pakistan’s KSE has risen for 9 of the past 10 weeks.

The Philadelphia Semiconductor Index (SOX) has risen 10% over the past 3 weeks.

Oslo is at an all-time high.

And the HSCEI and Indonesia’s IDX had a weekly outside bearish week. 

Commodities were mostly stronger.

Cotton, Coffee, JKM LNG, Cocoa and Wheat all had a good week.

Nickel as traded on India’s MCX makes a return to registering an overbought extreme.

Oil & Distillates, Copper,  Palladium, Platinum, Silver and Gold all saw weakness.

Tin returns to overbought territory.

Silver and Gold (in all currencies except the CHF) are no longer overbought. 

In fact, Gold performed a bearish outside reversal week.

Lean Hogs are in a 5 week losing streak.

Orange Juice has risen 27% over the past 3 weeks.

Soybeans are in a 5 week winning streak.

Cotton rose and broke its 11 week losing streak.

And Lithium Hydroxide has now spent 45 consecutive weeks in weekly oversold territory.

Currencies saw some action during the week.

The British Pound was stronger and nearing extreme against the JPY and EUR.

The Yen was mostly weaker., 

The Aussie was weaker against all except the Thai Baht and South African Rand.

The Euro as mixed while the Loonie was weaker.

The larger advancers over the past week comprised of;

Aluminium 2.4%, Cocoa 12.9%, Cotton 6.1%, JKM LNG 7%, Coffee 5.6%, JKM LNG in Yen 13.9%, Tin 2.7%, Nickel in MCX 4%, Orange Juice 6.3%, Robusta Coffee 10.6%, Corn 2.7%, Oats 3%, Wheat 7.1%, Egypt 4.1%, NIFTY 2%, SENSEX 2%, Chile 1.8% and the SOX rose 4.8%.

The group of largest decliners from the week included;

Baltic Dry Index (2.6%), WTI Crude Oil (2.3%), Lean Hogs (2.3%), Copper (5.9%), Heating Oil (2.8%), Nickel (4.1%), Palladium (4%), Platinum (4.7%), Gasoline (3.5%), Sugar (2.4%), Brent Crude Oil (2.1%), Gasoil (3.1%), Silver in AUD (2.7%), Silver in USD (3.6%), Gold in AUD (2.4%), Gold in CAD (3%), Gold in EUR (3.1%), Gold in GBP (3.6%), Gold in USD (3.3%), Rice (2.2%), Shanghai (2.1%), CSI 300 (2.1%), KBW Banks (2.3%), China A50 (2.6%), DJ Industrials (2.3%), DJ Transports (2.7%), MIB (2.6%), HSCEI (4.8%), Hang Seng (4.8%), BOVESPA (3%), IDX (3%), MOEX (3%), KRE Regional Banks (4.4%) and Mexico fel 3.8%.

And for some reference for Australian readers, the ASX 200 and ASX Small Caps fell 1.1%, the ASX Materials fell 1.5% while the ASX Industrials rose 0.9% for the week.

May 26, 2024

by Rob Zdravevski

rob@karriasset.com.au
The economics of the combustion engine prevail

My note dated, November 17, 2020 was titled; “A bet that the Internal Combustion Engine still has 30 years of life“

An extract from my late 2020 note included,

“It’s unlikely that automobile manufacturers will walk away from the capital expenditure spent on engine development and assembly, while synthetic fuels are making ICE’s even more cleaner.

Commensurate to introducing electric vehicles into their stable, auto companies have also made statements that they still expect the ICE to be part of their business for the next 30 years.

The note also observed Palladium’s premium above the price of Platinum (implying that the gap is narrowed as Palladium declines and Platinum rises) along with my expectation of mean reversion/convergence in the Gold price.

Gold did mean revert, Platinum rose and Palladium’s premium collapsed.

Since that note was published, both Platinum and Gold have risen 11%.

And Palladium is now cheaper than Platinum.

Now, Mercedes Benz has said it will continue to make combustion-engine and hybrid vehicles “well into the 2030s,” if demand is there.

The article continued to say, “And with China not phasing out sales of new combustion-engines until 2060,”

May 25, 2024

by Rob Zdravevski

rob@karriasset.com.au
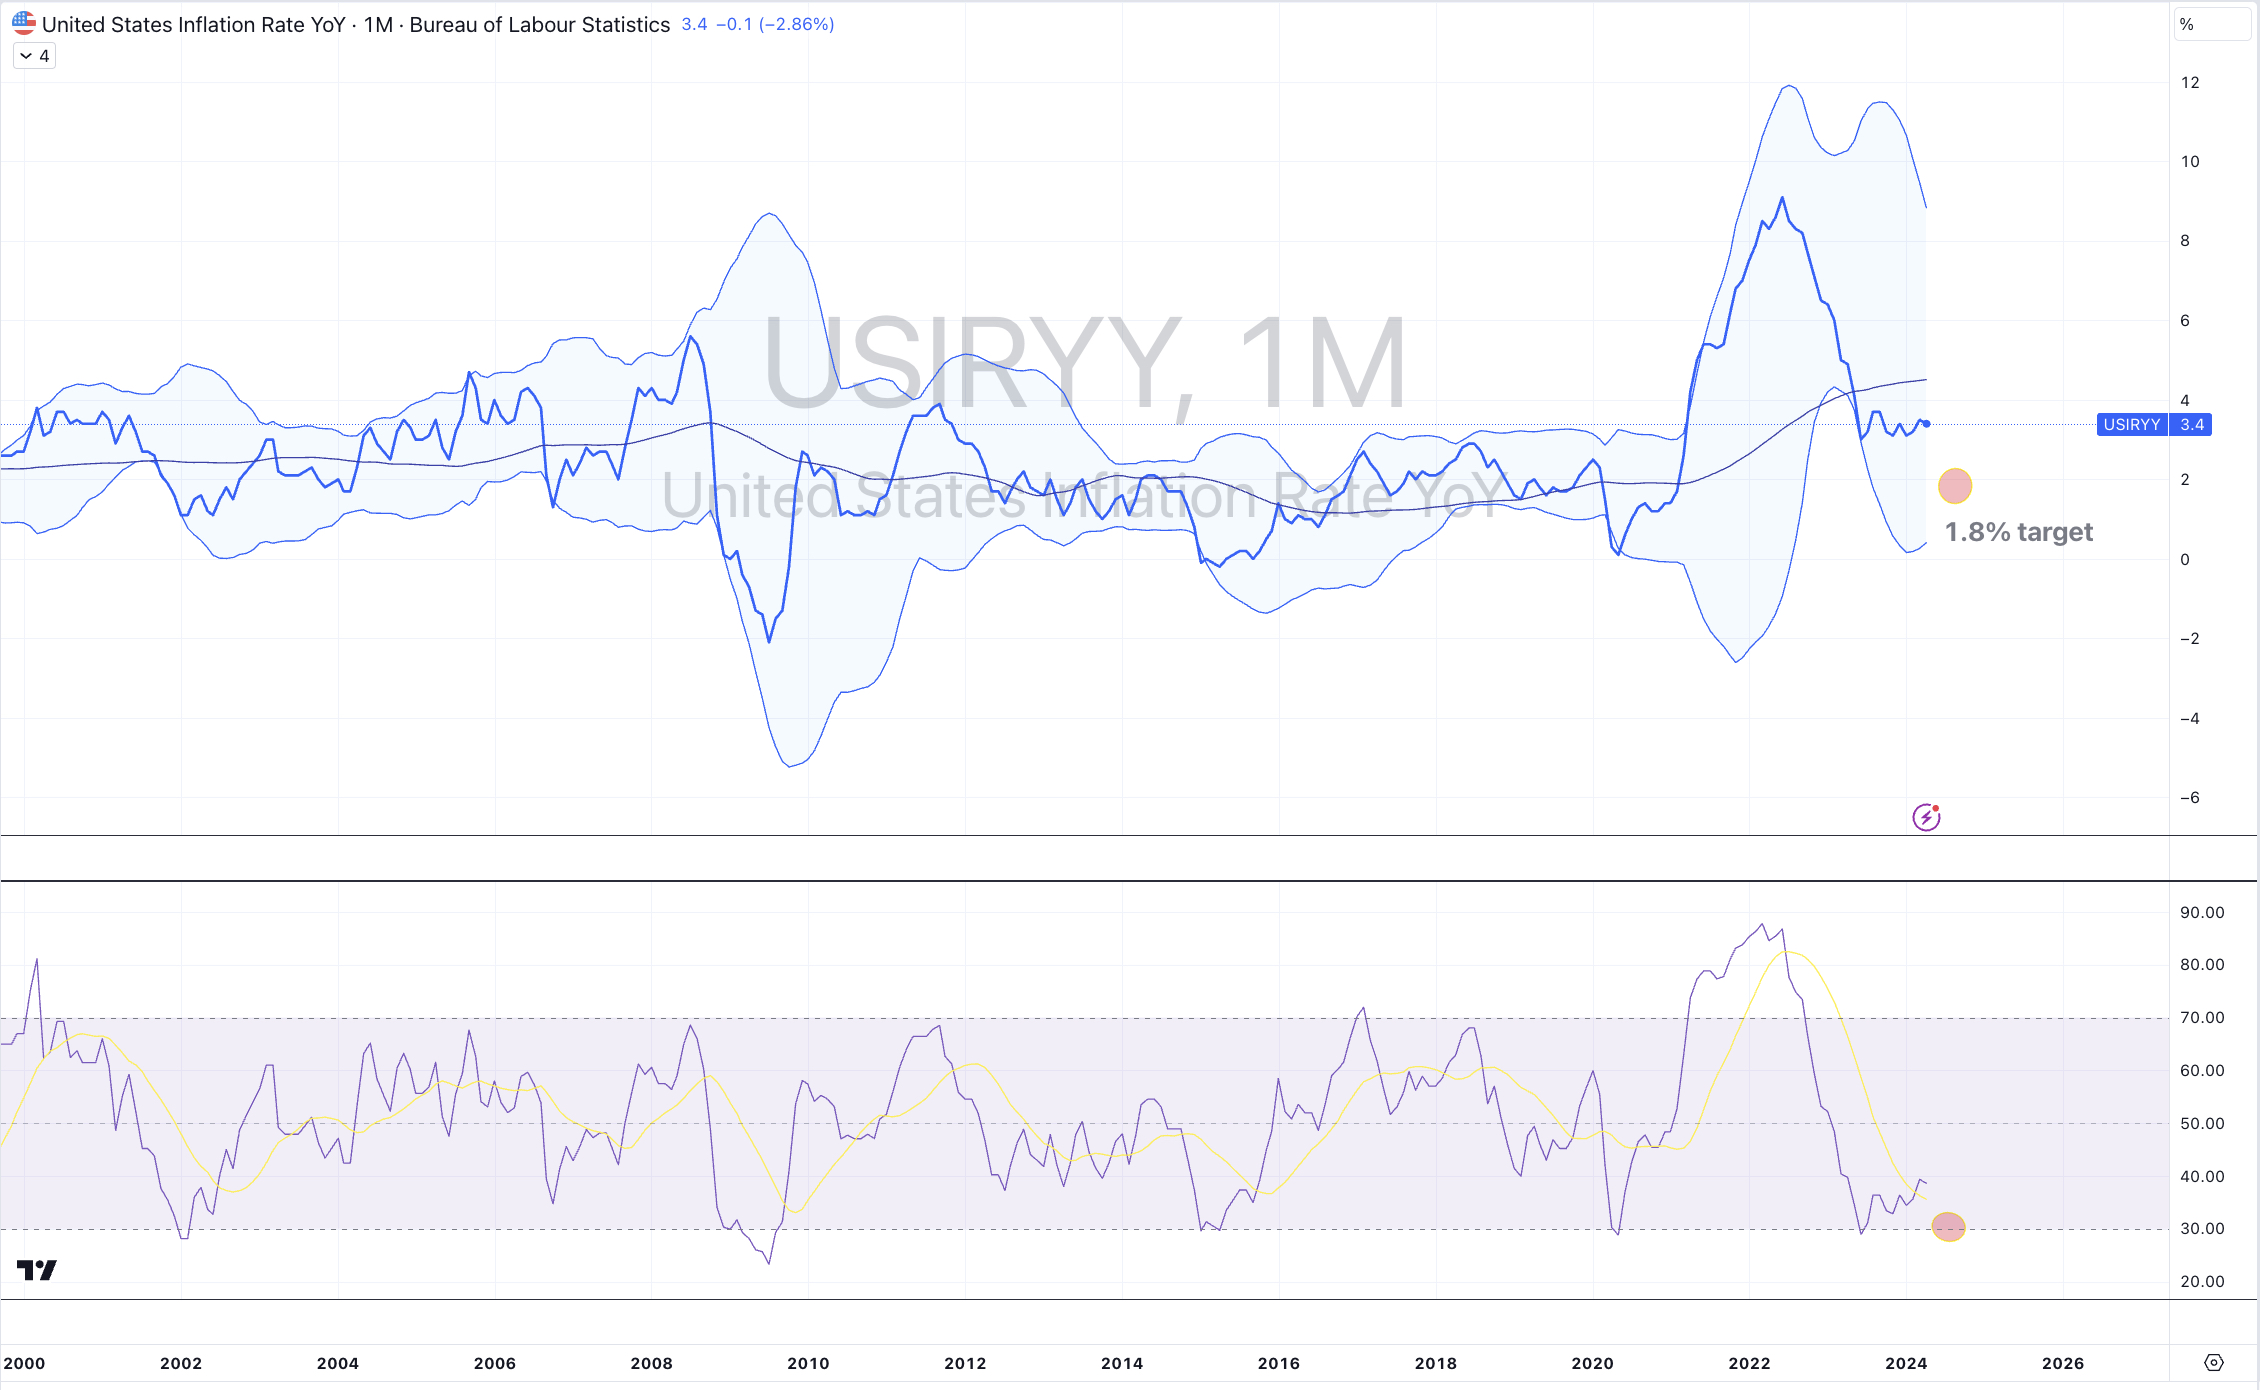
U.S. inflation to halve again

I think U.S. inflation can still decline to the 1.8% mark, somewhere around October 2024……

and all that comes with that for interest rates, commodity prices, growth equities and/or commercial real estate.

May 20, 2024

by Rob Zdravevski

rob@karriasset.com.au

For my past quips, search “inflation” at https://robzdravevski.com/?s=inflation

Screenshot

Macro Extremes (week ending May 17, 2024)

A weekly Macro, Cross Asset review of prices trading at extremes which may generate future investment ideas and opportunities.

The following assets (on a weekly timeframe) either registered an Overbought or Oversold reading and/or have traded more than 2.5 standard deviations above or below its rolling mean.

* denotes multiple week inclusion

Extremes “above” the Mean (at least 2.5 standard deviations)

Copper/Gold Ratio

Nickel

Platinum

Wheat 

AUD/CAD

AUD/JPY

HKD/USD

Hang Seng Index *

S&P Small Cap 600

Helsinki *

And Switzerland’s SMI

Overbought (RSI > 70)

Russian 10 year government bond yield *

Japanese 2 and 5 year government bond yield * 

Silver in AUD

Gold in CAD, CHF, EUR, GBP & USD *

AEX *

Austria’s ATX *

Budapest *

DAX *

MIB *

MOEX

Malaysia’s KLSE *

Pakistan’s KSE Index *

Oslo *

Russell 2000

South Africa 40 *

TAEIX *

TSX

FTSE 100

and Turkiye’s BIST 100 *

The Overbought Quinella (Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)

Copper *

Orange Juice

Silver in USD

Hang Seng China Enterprises Index (HSCEI) *

Extremes “below” the Mean (at least 2.5 standard deviations)

USD/ZAR

Oversold (RSI < 30)

Cotton

Lithium Hydroxide *

Lumber *

North European Hot Rolled Coil Steel *

Urea (Middle East)

The Oversold Quinella (Both Oversold and Traded at < 2.5 standard deviations below the weekly mean)

None

Notes & Ideas:

Government bond yields were lower.

Amongst the week’s relative quiet action, the Copper/Gold Ratio entered overbought terrority which tends to coincide with bonds yields peaking.


Equities were higher again.

The FTSE 100 switches places in oversold land with the FTSE 250.

The American Russell 2000 and S&P SmallCap 600 return to being overbought as has Toronto’s TSX.

Many European indices remain overbought as some of the China and Hong Kong indices.

The HSCEI and Hang Seng have both risen 19% in the past 4 weeks.

The All Word Developed (ex USA) Index is in a 4 week winning streak as it the Dow Jones Industrials and the Nasdaq Composite.

And Italys MIB made an all-time high.

Commodities were mostly stronger.

Coal, Cocoa, Lumber, Sugar, Oats and Grains were weaker.

Metals (Precious and Base), Gases, Oil, Coffee, Cattle and Orange Juice were stronger.

Platinum, Nickel and Orange Juice make a return visit to overbought territory.

Oats are no longer oversold as they broke their 5 week winning streak falling 11% for the week (whilst performing a weekly outside bearish reversal), giving up nearly half of their 26.5% return over that time.

Copper, Silver and Gold are overbought, while Hot Rolled Coil Steel, Lumber and Cotton and Lithium are in the oversold category. 

Lumber has tanked 22% over the past 8 weeks and Cotton has slumped for 11 consecutive weeks.

Most grains eased following 4 weeks of consecutive gains.

Over the past 3 weeks, Platinum has risen 17%.

The Baltic Dry Index fell 13%, giving up half of the 23% gain seen in the prior fortnight.

And Lithium Hydroxide has now spent 44 consecutive weeks in weekly oversold territory.

Currencies saw some action during the week.

The AUD was stronger and as some pairs return to be ing overbought.

And interestingly, the CHF/AUD is nearing overbought territory.

The larger advancers over the past week comprised of;

Aluminium 1.8%, Bloomberg Commodity Index 2.9%, WTI Crude Oil 2.3%, Copper 8.3%, Heating Oil 2.1%, JKM LNG 4.5%, Coffee 2.7%, Cattle 2.7%, JKM LNG in Yen 1.8%, Tin 2.4%, LME Aluminium 3.6%, Natural Gas 16.6%, Nickel 11.9%, Nickel on MCX 3.2%, Orange Juice 13.8%, Palladium 3%, Platinum 8.2%, Gasoline 2.7%, Robusta Coffee 2.3%, Dutch TTF Gas 2.5%, Silver in AUD 10.3%, Silver in USD 11.8%, Gold in CAD 1.9%, Gold in CHF 2.6%, Gold in USD 2.3%, ASX 200 1.7%, MIB 2.1%, HSCEI 3.2%, HSO 3.1%, IBEX 2%, IDX 2.5%, Russell 2000 1.9%, Nasdaq Composite 2.1%, KSE 3.1%, Nasdaq Biotech 2.4%, Nikkei 225 2.1%, Copenhagen 2.7%, SENSEX 1.7%, SMI 2.4%, SOX 3.6%, S&P 500 1.5%, TAEIX 2.7%, Vietnam 2.3%, ASX Materials 2.5% and BIST rose 4.2%.

The group of largest decliners from the week included;

Australian Coking Coal (2.5%) Rotterdam Coal (1.8%), Baltic Dry Index (13.4%), Cocoa (17.4%), China Coking Coal (2.3%), Cotton (1.8%), Lean Hogs (1.9%), Lumber (1.7%), Sugar (6.1%), Corn (3.7%), Oats (11.1%), Rice (3.2%), Wheat (1.9%), Budapest (1.6%) and the ASX Industrials fell 1.8%.

May 19, 2024

by Rob Zdravevski

rob@karriasset.com.au
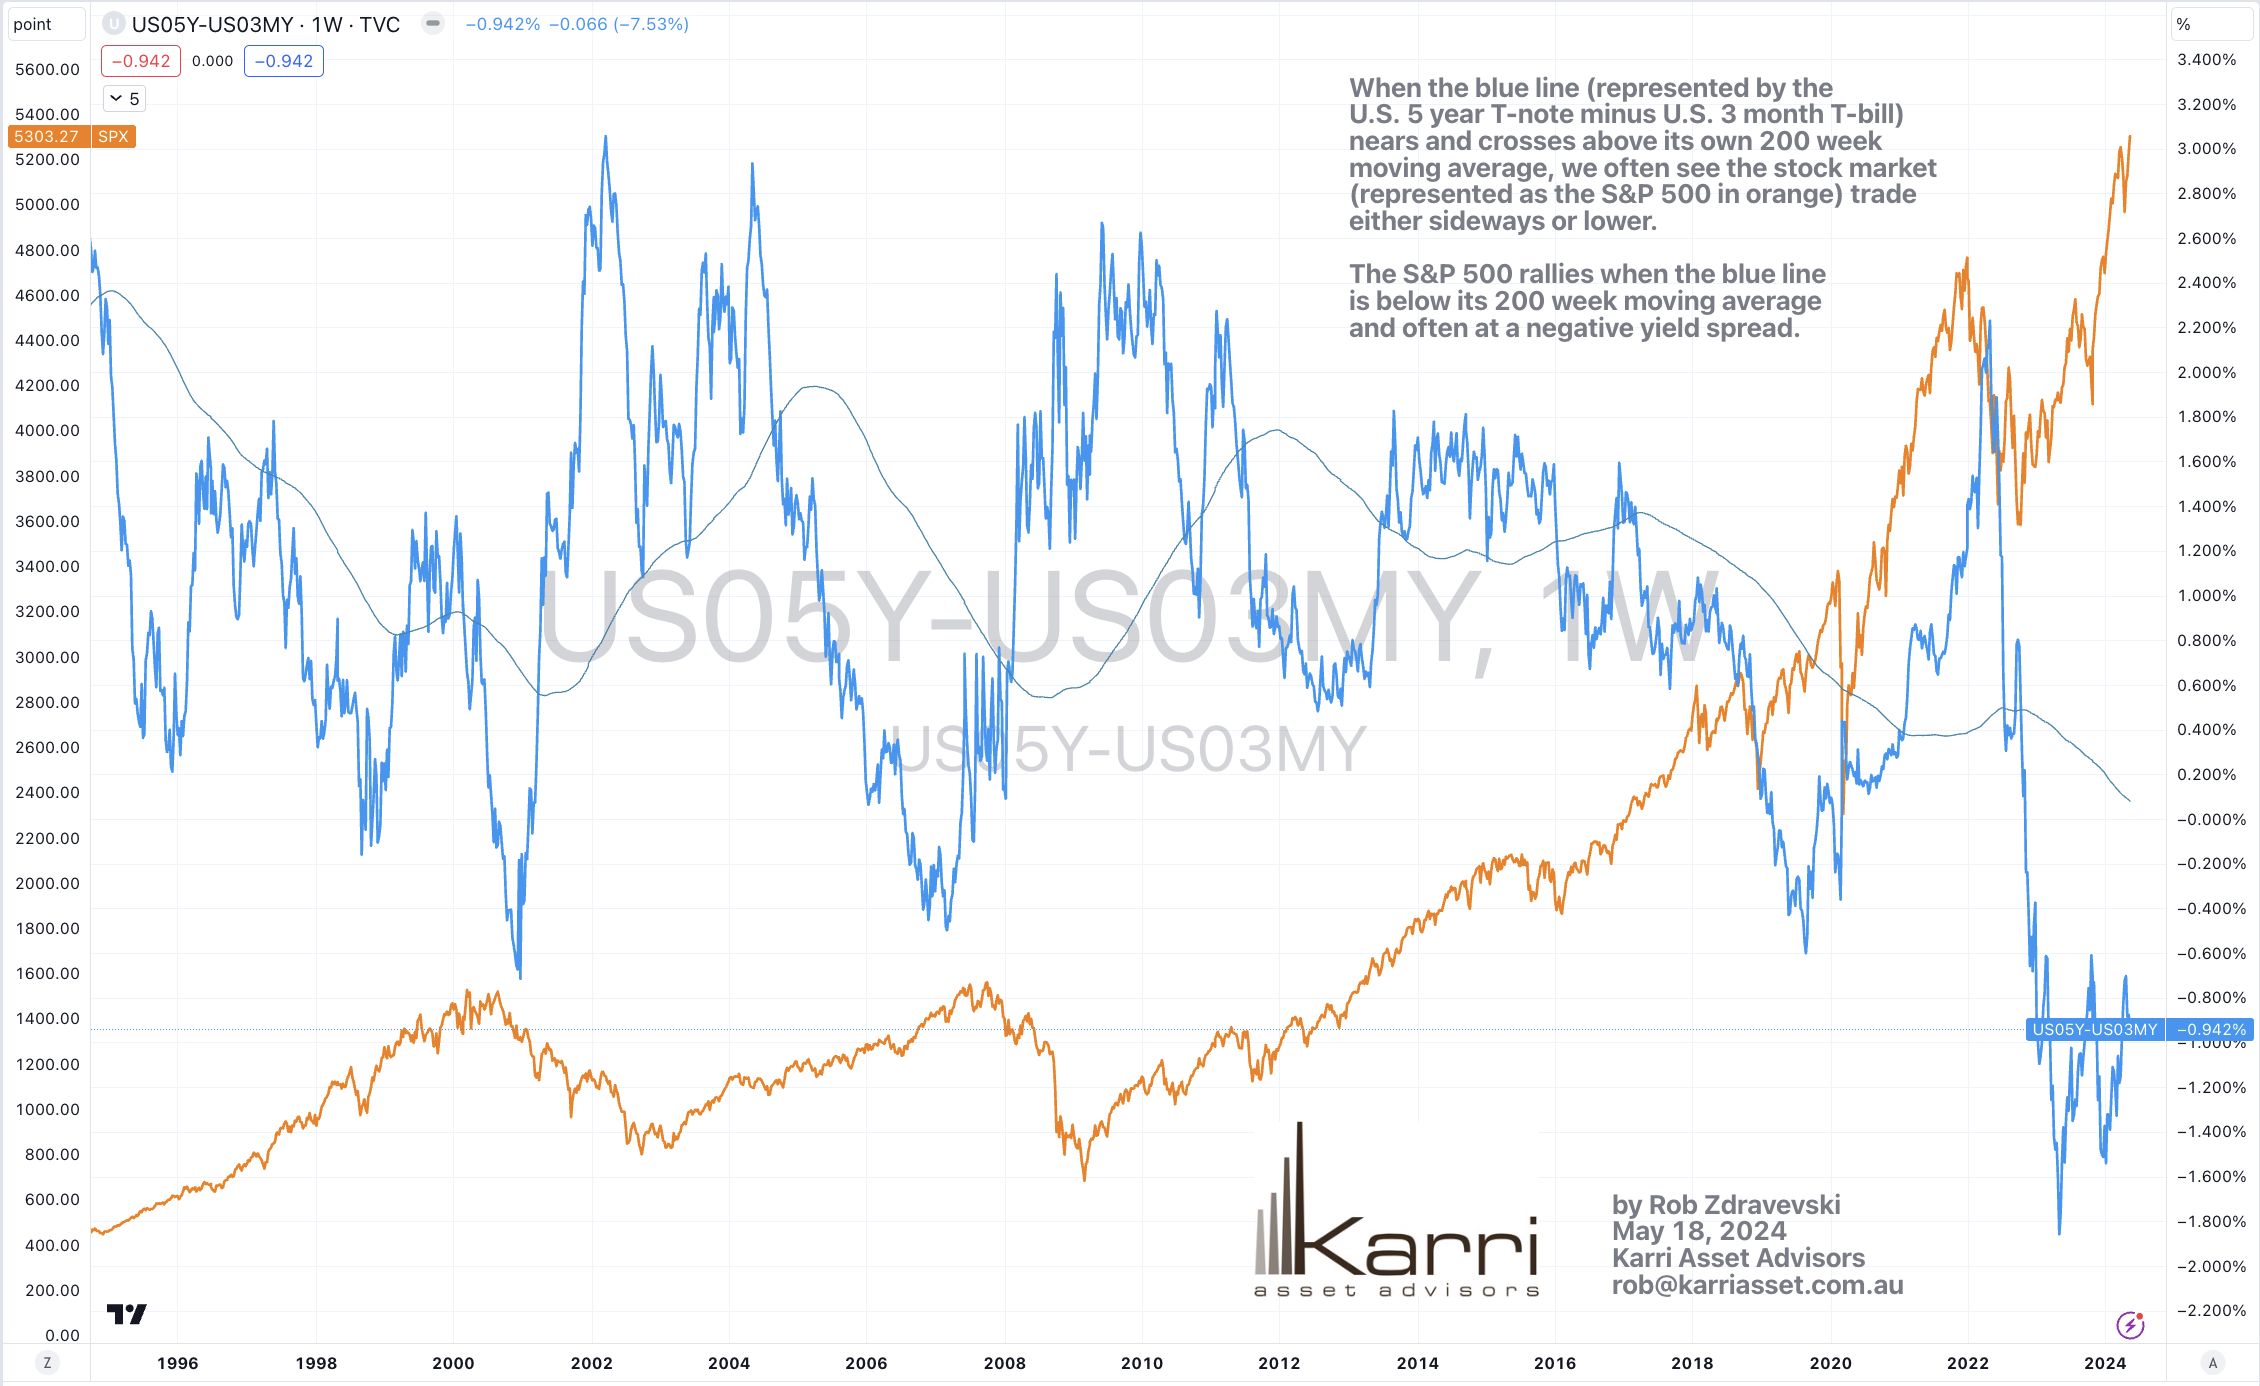
Negative yields spreads leave no alternative

When the blue line (represented by the U.S. 5 year T-note minus U.S. 3 month T-bill) nears and crosses above its own 200 week moving average, we often see the stock market (represented as the S&P 500 in orange) trade either sideways or lower. 

The S&P 500 rallies when the blue line is below its 200 week moving average and often at a negative yield spread.

May 18, 2024

by Rob Zdravevski

rob@karriasset.com.au
Screenshot

AUD/USD remains sideways

Whilst the AUD/USD is currently in a medium and longer term upward trend, I think that it looks constrained around the 0.6750 – 0.6722 mark.

My read is that it needs make a ‘higher high’. If not, the AUD/USD will continue its digestive and consolidation pattern lower.

and so….it would go for commodities and bond yields.

May 16, 2024

by Rob Zdravevski

rob@karriasset.com.au

Screenshot

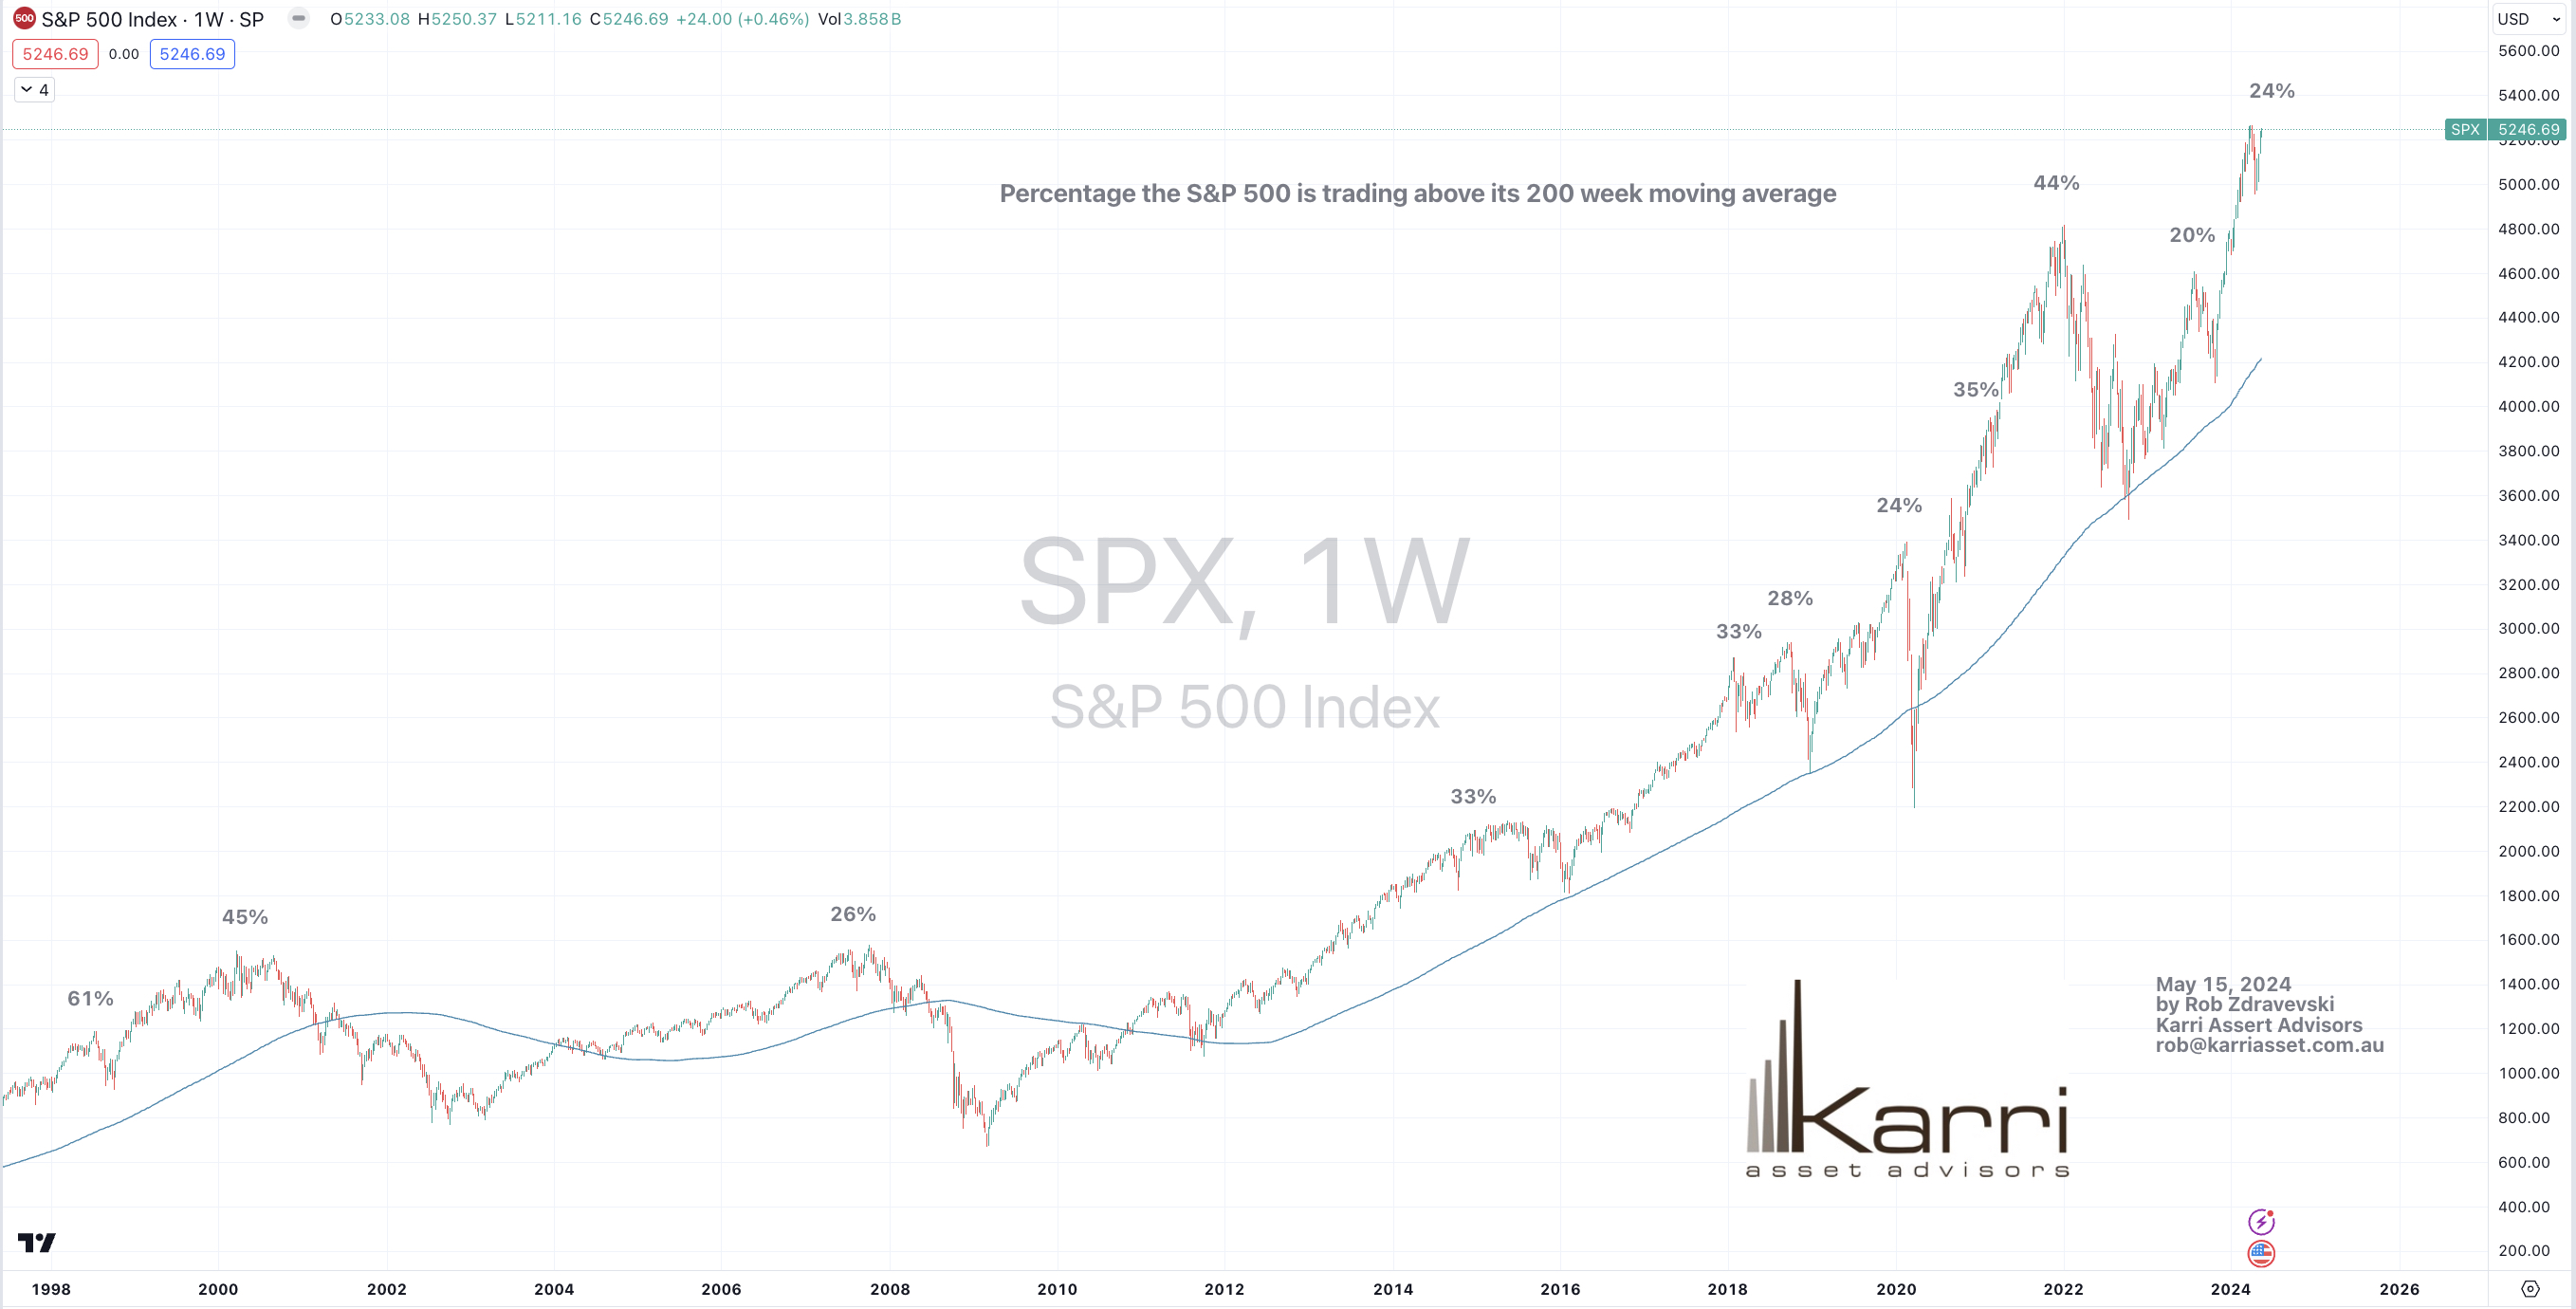
Is it late at the party?

Within the S&P 500 party, it may be 11pm or perhaps midnight but its not 3am

#spx

May 15, 2024

by Rob Zdravevski

rob@karriasset.com.au

Screenshot

Trendless Oil, looking for much lower prices

I haven’t seen any compelling investment opportunity in Crude Oil (or any related equites) over the past 2 years.

I’ve been comfortable with that view as the price of #Oil has mostly traded sideways over that time.

Digestion has been the prevailing trend amongst oil and gas equities.

I’d like to see WTI #CrudeOil trade down to the $64 range before being interested.

At $46, it would become compelling.

This would translate to the share price in Australian energy company, Woodside Energy trading down to $19.65. (it’s currently $28.20)

……and then I ponder the related correlations in currencies etc.

May 14, 2024

by Rob Zdravevski

rob@karriasset.com.au

Macro Extremes (week ending May 10, 2024)

A weekly Macro, Cross Asset review of prices trading at extremes which may generate future investment ideas and opportunities.

The following assets (on a weekly timeframe) either registered an Overbought or Oversold reading and/or have traded more than 2.5 standard deviations above or below its rolling mean.

  • denotes multiple week inclusion

Extremes “above” the Mean (at least 2.5 standard deviations)

Oats *

Hang Seng China Enterprises Index (HSCEI) *

Hang Seng Index *

South Africa 40 *

FTSE 250

Helsinki 

Overbought (RSI > 70)

Russian 10 year government bond yield 

Japanese 2 year government bond yield 

Copper

Gold as priced in USD, GBP, EUR, CHF and CAD

AEX *

Budapest *

DAX

MIB

Stockholm

TAEIX

Malaysia’s KLSE *

Pakistan’s KSE Index *

FTSE 250

and Turkiye’s BIST 100 *

The Overbought Quinella (Both Overbought and Traded at > 2.5 standard deviations above the weekly mean)

Austria’a ATX

Oslo

FTSE 100

Extremes “below” the Mean (at least 2.5 standard deviations)

None

Oversold (RSI < 30)

Lithium Hydroxide *

North European Hot Rolled Coil Steel *

Midwest U.S. Hot Rolled Coil Steel

Lumber *

The Oversold Quinella (Both Oversold and Traded at < 2.5 standard deviations below the weekly mean)

None

Notes & Ideas:

Government bond yields were mixed, with a slight bias higher.

Generally, those yields which were overbought in the recent weeks, fell and those yields that weren’t overbought…rose over the past week.

Equities were mostly higher, with Indian indices amongst the few to decline.

Europe was stronger. Perhaps it was a Eurovision rally?

It has been nearly 3 years since the FTSE 250 has registered an overbought extreme. It has risen 6.5% over the past 3 weeks.

Germany’s DAX, Italy’s MIB, & Stockholm’s OSX 30 are back in overbought territory.

The HSCEI and Hang Seng have both risen 16% in the past 3 weeks.

Furthermore, the Shanghai Composite, CSI 300, the U.S. (KRE) Regional Banks Index and Malaysia’s KLCI Index are in a 4 week winning streaks.

China’s A50 Index and the U.S. KBW Bank Index have risen 7.5% and 8% respectively, over the past 4 weeks.

And the Nasdaq Transports broke its 5 week losing streak.

Commodities were mostly stronger.

Precious Metals, Grains, Gases and Softs were stronger.

Oats are in a 5 week winning streak and have climbed 26.5% over that time.

Urea, Steel and Lumber prices were weaker. Lumber has tanked 20% over the past 7 weeks.

Some of the grains are now seeing 4 weeks of consecutive gains.

Copper and Gold are overbought, while Hot Rolled Coil Steel, Lumber and Lithium are in the oversold category.

Robusta Coffee has fallen 18% over the past fortnight which accounts for nearly half of the 39% rise seen in the prior 10 weeks.

Cotton has fallen for 10 consecutive weeks, sinking 21% over that time and nearing oversold territory.

Over the past fortnight, Platinum has risen 9% while Gasoline has slumped 9%.

The Baltic Dry Index has soared 23% in 2 weeks.

And Lithium Hydroxide has now spent 43 consecutive weeks in weekly oversold territory.

Currencies were generally quiet for the week except for the renewed weakness in the Yen.

The AUD fell against all except the Yen.

The Euro was firmer and the EUR/USD is in a 4 week winning streak.

And the U.S. Dollar rose against everyone except anything called a Peso.

The larger advancers over the past week comprised of;

Baltic Dry Index 13.5%, Cocoa 9.2%, JKM LNG in Yen 6.9%, Tin 6.3%, Natural Gas 5.1%, Orange Juice 6.5%, Palladium 3.5%, Platinum 4.3%, Silver in AUD 6.1%, Gold in AUD 2.6%, Gold in USD 2.5%, Corn 2.1%, Oats 6.1%, Rice 2.7%, Wheat 6.6%, CSI 300 1.7%, AEX 2.6%, ATX 2.7%, KBW 2.7%, Budapest 1.8%, CAC 3.3%, DAX 4.3%, DJ Industrials 2.2%, MIB 3.1%, HSCEI 2.6%, Hang Seng 2.6%, IBEX 2.3%, S&P SmallCap 600 1.7%, Nasdaq Composite 1.1%, KOSPI 1.9%, FTSE 250 2.4%, S&P MidCap 400 2.2%, Nasdaq 100 1.5%, Oslo 3.5%, Copenhagen 2.3%, Helsinki 3.3%, Stockholm 3.5%, SA40 2.7%, SMI 4.3%, SOX 2%, S&P 500 1.9%, TAEIX 1.9%, Nasdaq Transports 2%, TSX 1.7%, FTSE 100 2.7%, Vietnam 1.9%, ASX 200 1.6%, ASX Industrials 1.7%, ASX Small Caps 1.5% and the Tel Aviv 35 rose 3.3%.

The group of largest decliners from the week included;

U.S. Hot Rolled Coil (HRC) Steel (4.1%), Lumber (2.1%), Newcastle Coal (2%), Gasoline (2.2%), Robusta Coffee (2.9%), Urea Middle East (2.3%), NIFTY (1.9%) and India’s SENSEX fell 1.7%.

May 12, 2024

by Rob Zdravevski

rob@karriasset.com.au

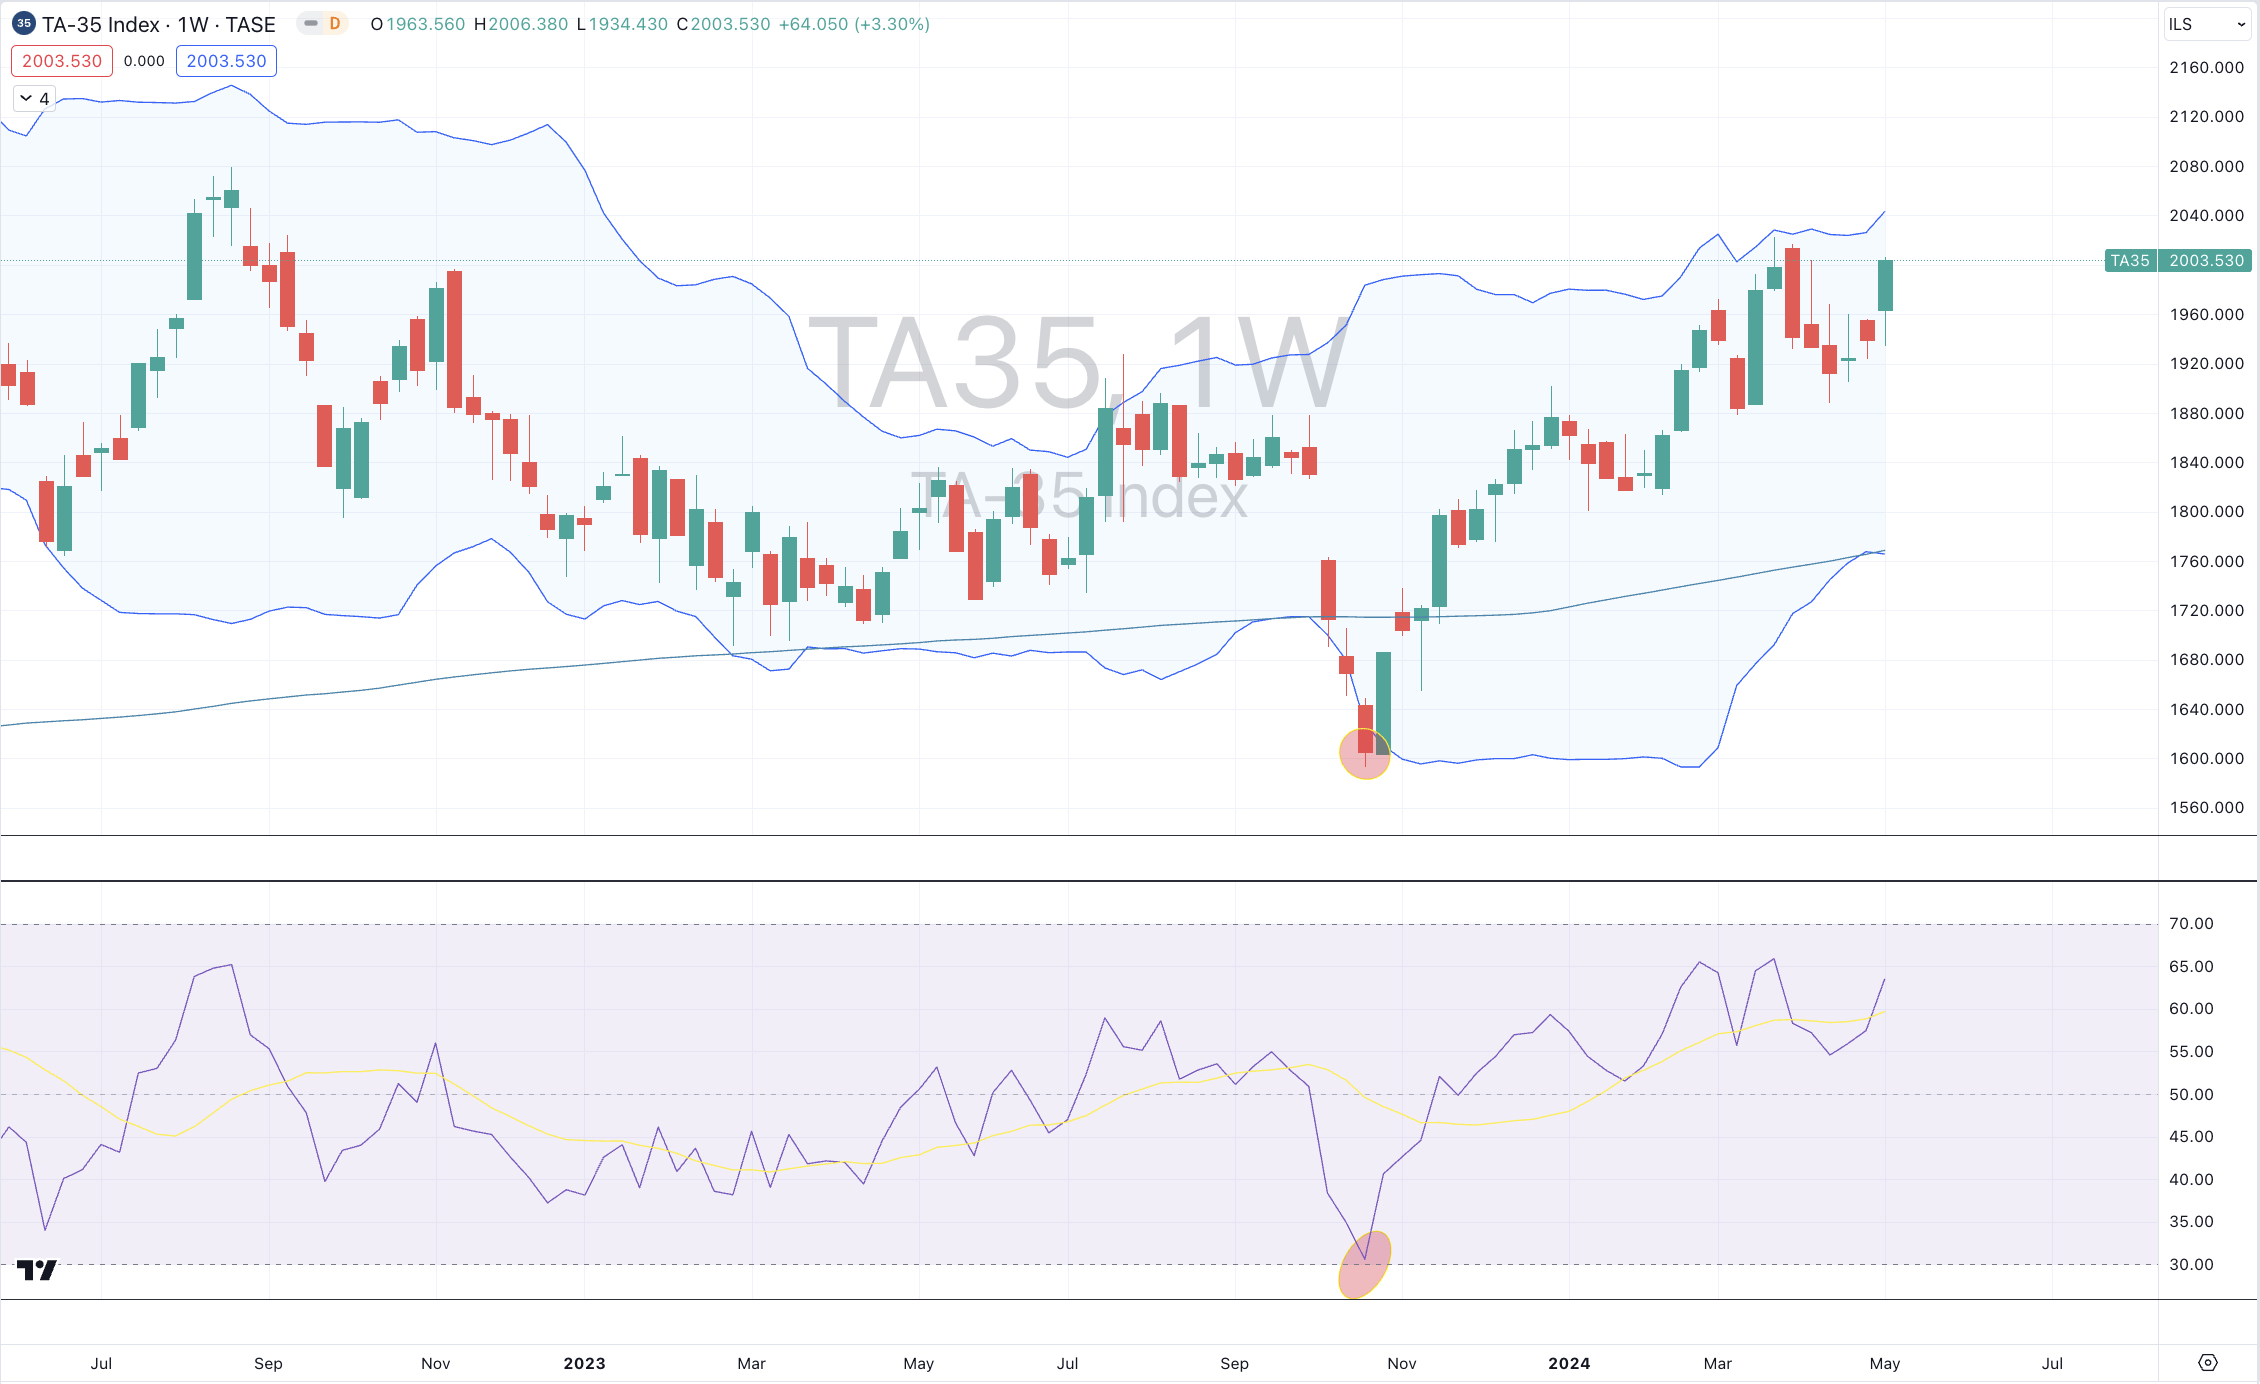
Israel’s gains against the grain

Under the category of being steadfast when buying (or investing) at a time of crisis or intense pessimism….

at the moment when its was both (simultaneously) trading at a weekly oversold level and 2.5 standard deviations below its weekly mean….

Israel’s Tel Aviv 25 equity index has risen 25% within 7 months.

The mind boggles.

Admittedly, this market wasn’t within my focus in October 2023 as many other indices were cratering at the same time.

The TA35 has easily outperformed Australia’s ASX 200 which has risen 14% from its October 2023 trough.

Screenshot